Your standard homeowners insurance policy won’t protect your vacation rental business. Most policies explicitly exclude income from guests and liability claims tied to short-term rentals.

At Direct Insurance Services, we’ve seen hosts lose thousands because they assumed their existing coverage was enough. The gap between what homeowners insurance covers and what vacation rental property coverage actually provides can be devastating.

Why Your Homeowners Policy Won’t Cover Your Rental

Standard Homeowners Insurance Excludes Rental Income

Standard homeowners insurance exists to protect your primary residence, not a business operation. When you rent out a property to guests, you transform that building from a home into a commercial enterprise. The Insurance Information Institute confirms that regularly renting out a second home requires separate business coverage or a landlord policy because personal homeowners policies explicitly exclude income-generating activities. Your insurer will deny claims related to guest injuries, property damage caused by renters, or lost income from cancellations. Hosts face five-figure repair bills after guest incidents because their homeowners policy contains standard exclusions for rental properties. The contract language is clear: coverage terminates the moment you start accepting payment for overnight stays.

Guest Injuries Leave You Personally Liable

Your homeowners liability coverage protects you if someone gets injured at your primary residence, but that protection vanishes with rental activity. A guest who slips on your rental property’s stairs and requires surgery can pursue a lawsuit against you personally. Standard homeowners policies reject these claims outright because they don’t cover business-related liability. Vacation rental property insurance provides up to $1,000,000 in bodily injury coverage depending on the policy. Without it, medical bills, legal fees, and potential settlement costs come directly from your pocket. This risk intensifies if your property has higher-risk features like pools, hot tubs, or multiple stories where accidents become more likely.

Guest Damage Creates a Financial Double Hit

When a guest damages your rental property-whether it’s a broken window, stained carpeting, or destroyed furniture-your homeowners policy won’t cover the repair costs. More importantly, if that damage forces you to close the property for repairs, you lose rental income with zero compensation. A standard homeowners policy has no mechanism to reimburse lost rental income because it never anticipated you’d operate a business from the property. Vacation rental property insurance addresses both problems by covering guest-caused property damage and providing loss of rental income protection during covered repair periods. Hosts without this coverage face a double hit: they pay for repairs while simultaneously losing the revenue that pays their mortgage and property taxes.

What This Means for Your Coverage Strategy

The gap between homeowners insurance and vacation rental protection is substantial. Your existing policy leaves you exposed to liability claims, property damage costs, and lost income-three financial threats that can devastate your rental business. The solution requires moving beyond standard homeowners coverage to policies specifically designed for short-term rental operations. Understanding which types of coverage address these gaps will help you build the protection your rental property actually needs.

Types of Insurance Coverage Vacation Rental Hosts Need

Property Damage Coverage Protects Your Investment

Vacation rental property insurance policies form the foundation of your protection, but they’re not a single monolithic product. Safely offers up to $1,000,000 in bodily injury coverage with claims paid in 4–5 days in 98% of cases, while Proper Insurance provides no limit on guest-damage payouts alongside $1,000,000 liability coverage. CBIZ Vacation Rental Insurance includes $2,000,000 general liability with bed bug coverage up to $25,000 and loss of rental income protection.
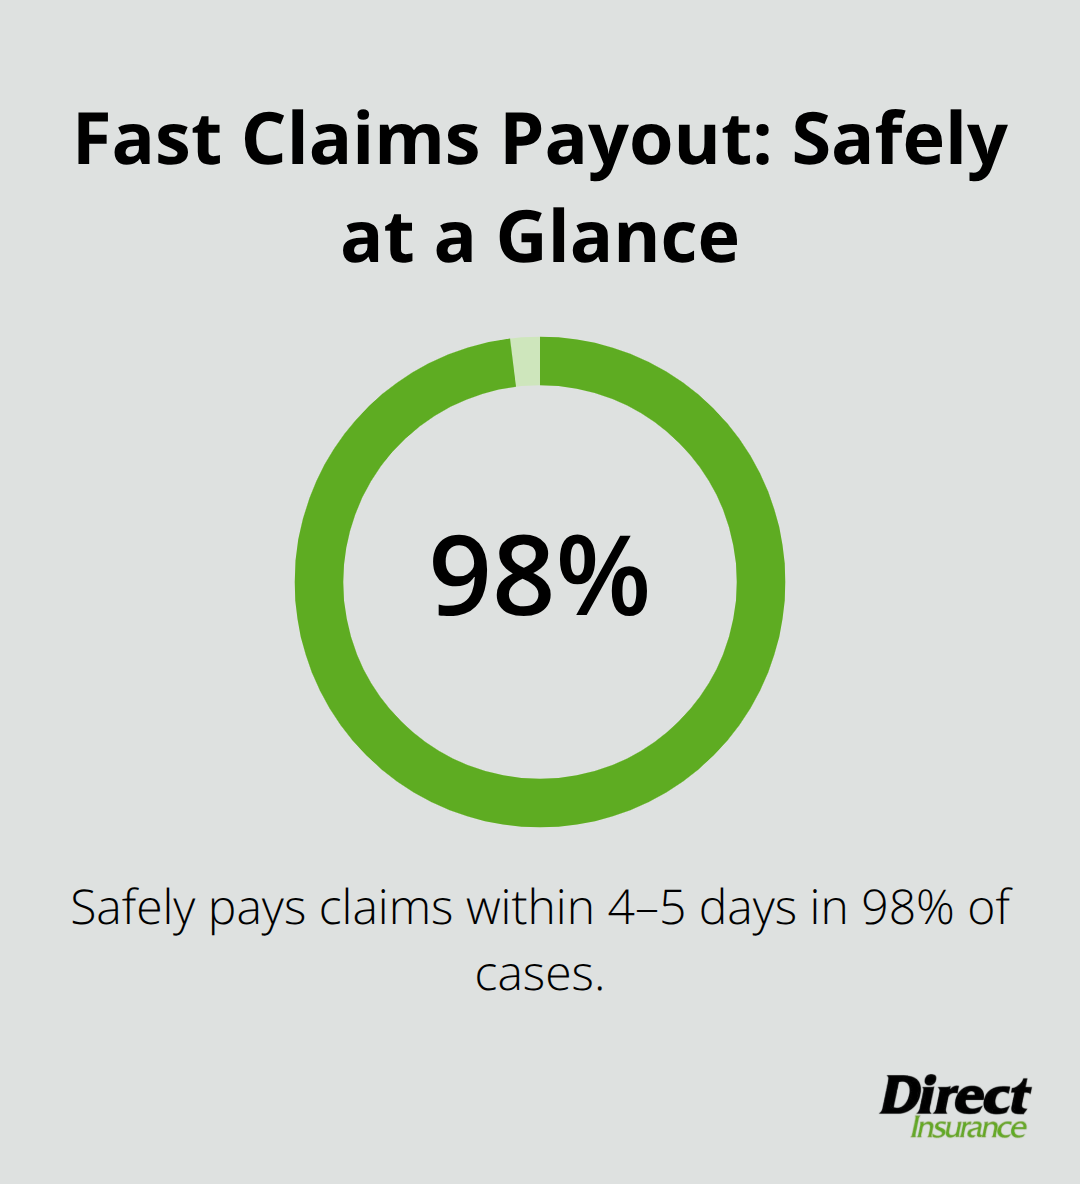
Visualization showing that Safely pays claims within 4–5 days in 98% of cases for vacation rental hosts.

The key difference between these providers lies in their claims speed and damage caps-Safely prioritizes rapid payouts for hosts who need immediate reimbursement, while Proper Insurance attracts hosts with high-value properties by removing damage caps entirely.

Liability Coverage Protects You from Guest Injuries

Liability coverage for guest accidents operates separately from property damage protection, though most vacation rental policies bundle them together. When a guest sustains a serious injury at your rental, your liability coverage covers their medical expenses, legal fees, and settlement costs up to your policy limit. Without this protection, you personally defend the lawsuit and pay damages from your own assets. Your property type determines which carrier serves you best-a single-family home with a pool needs different coverage than a downtown condo, and providers like Obie offer digital quotes tailored to diverse property types across all 50 states.

Loss of Rental Income Protection Replaces Your Revenue

Loss of rental income protection reimburses you for revenue lost during covered repair periods. If a guest damages your kitchen and repairs require two weeks of closure, this coverage replaces the booking income you would have earned. Most hosts overlook this component, assuming property damage coverage alone suffices, but the financial impact of lost occupancy often exceeds repair costs. Costs can range from as little as $40 per year for limited add-ons to over $4,000 for high-end or high-risk properties, making income protection an affordable addition that prevents catastrophic revenue loss.

How These Three Pillars Work Together

The combination of property damage, liability, and income protection creates a complete financial safety net that standard homeowners policies simply cannot provide. Each component addresses a specific financial threat-repairs, lawsuits, and lost bookings-that can devastate your rental business independently. When you stack these three coverage types together, you eliminate the gaps that leave hosts vulnerable.
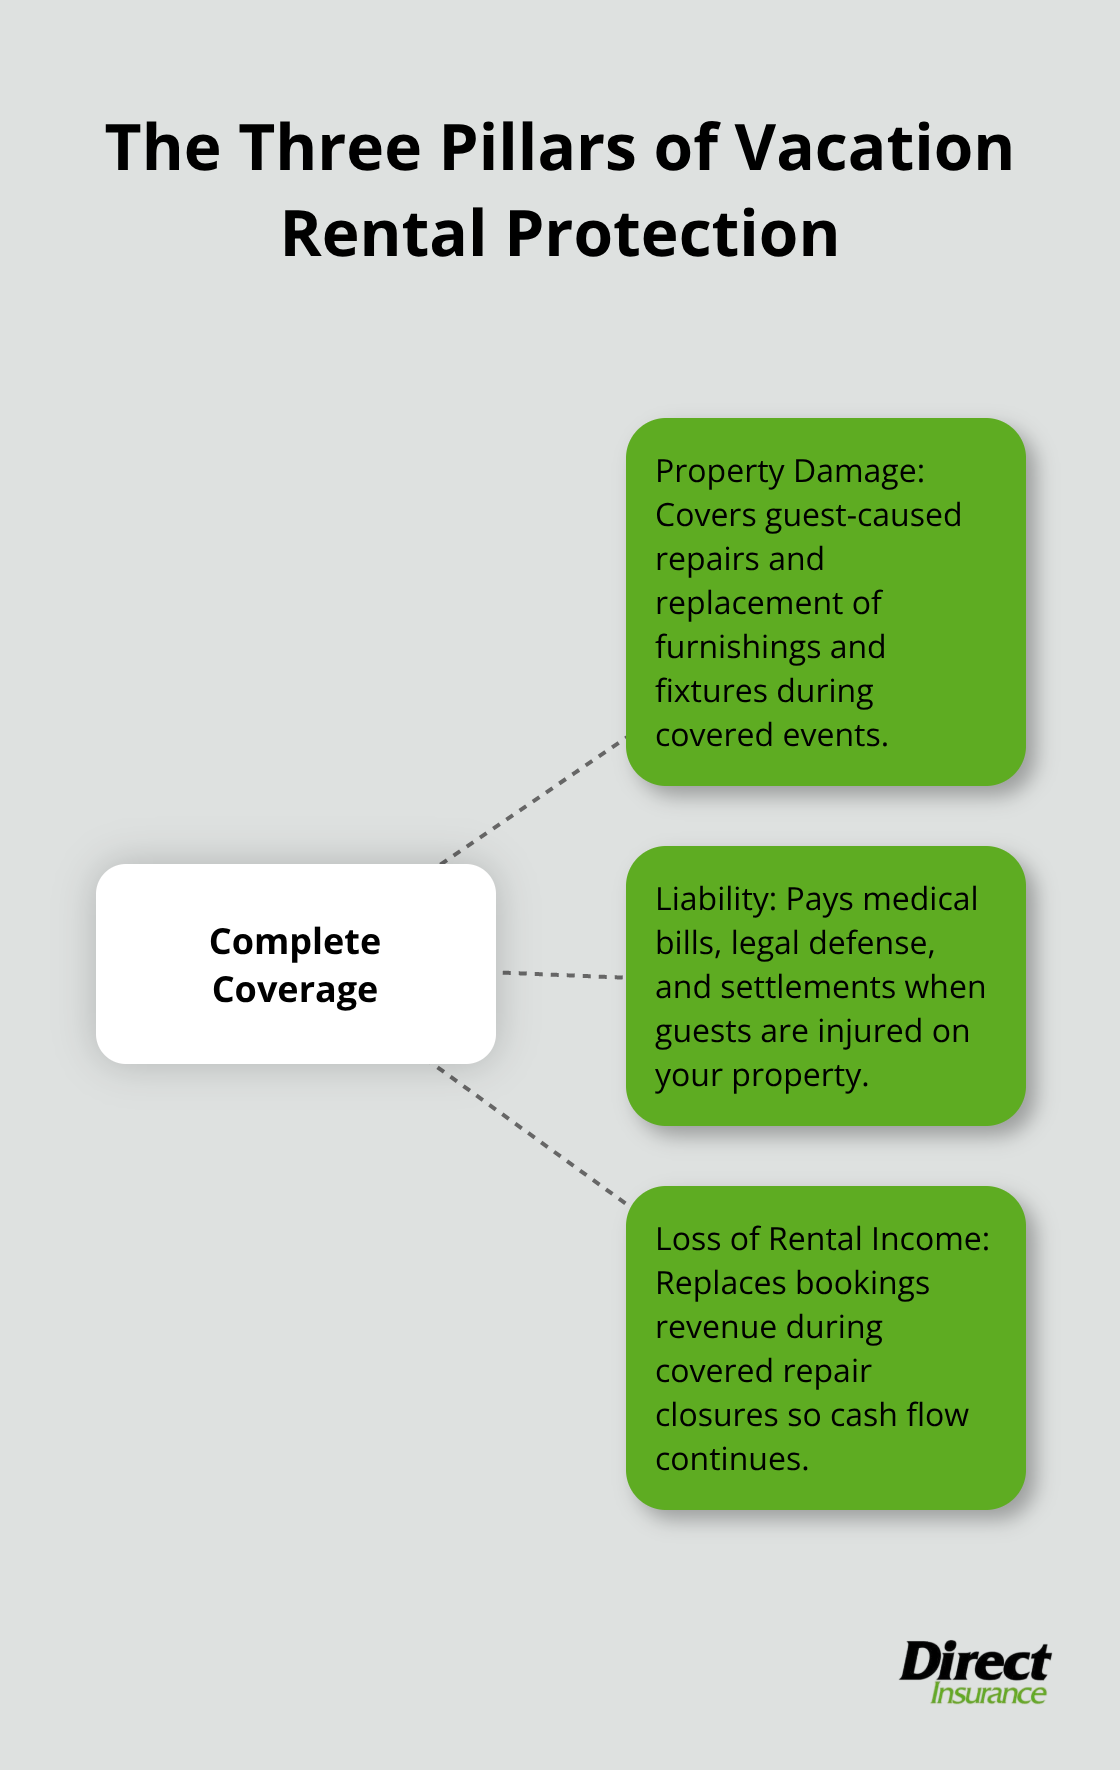
Hub-and-spoke diagram showing property damage, liability, and loss of rental income protection working together for vacation rental hosts. - vacation rental property coverage

The next step involves selecting the right policy limits and deductibles for your specific situation, which requires understanding your property’s unique risk profile and guest patterns.

Selecting the Right Coverage Limits for Your Rental

Match Coverage Limits to Your Property’s Risk Profile

Property type and occupancy patterns determine which coverage limits actually protect your rental business. A single-family home with a pool hosting 40 guests annually needs different protection than a downtown condo with 120 annual bookings, yet many hosts simply accept whatever limits their insurer suggests. Safely’s $1,000,000 bodily injury coverage works well for moderate-risk properties, but Proper Insurance’s unlimited guest-damage payouts serve hosts with high-end furnishings or luxury amenities where a single incident could exceed standard caps. Your mortgage lender requires minimum coverage amounts before they’ll approve your loan, and this requirement often exceeds what casual hosts assume they need. CBIZ Vacation Rental Insurance includes $2,000,000 general liability, which provides substantial protection but costs more than policies with liability limits of $1,000,000.

The Insurance Information Institute notes that property value, location, guest turnover, and safety features directly influence both your premium and the appropriate coverage ceiling. A $500,000 property with annual bookings totaling 200 nights faces higher exposure than a $300,000 property rented only 60 days yearly, which means your policy limits should reflect actual occupancy and risk, not just property value.
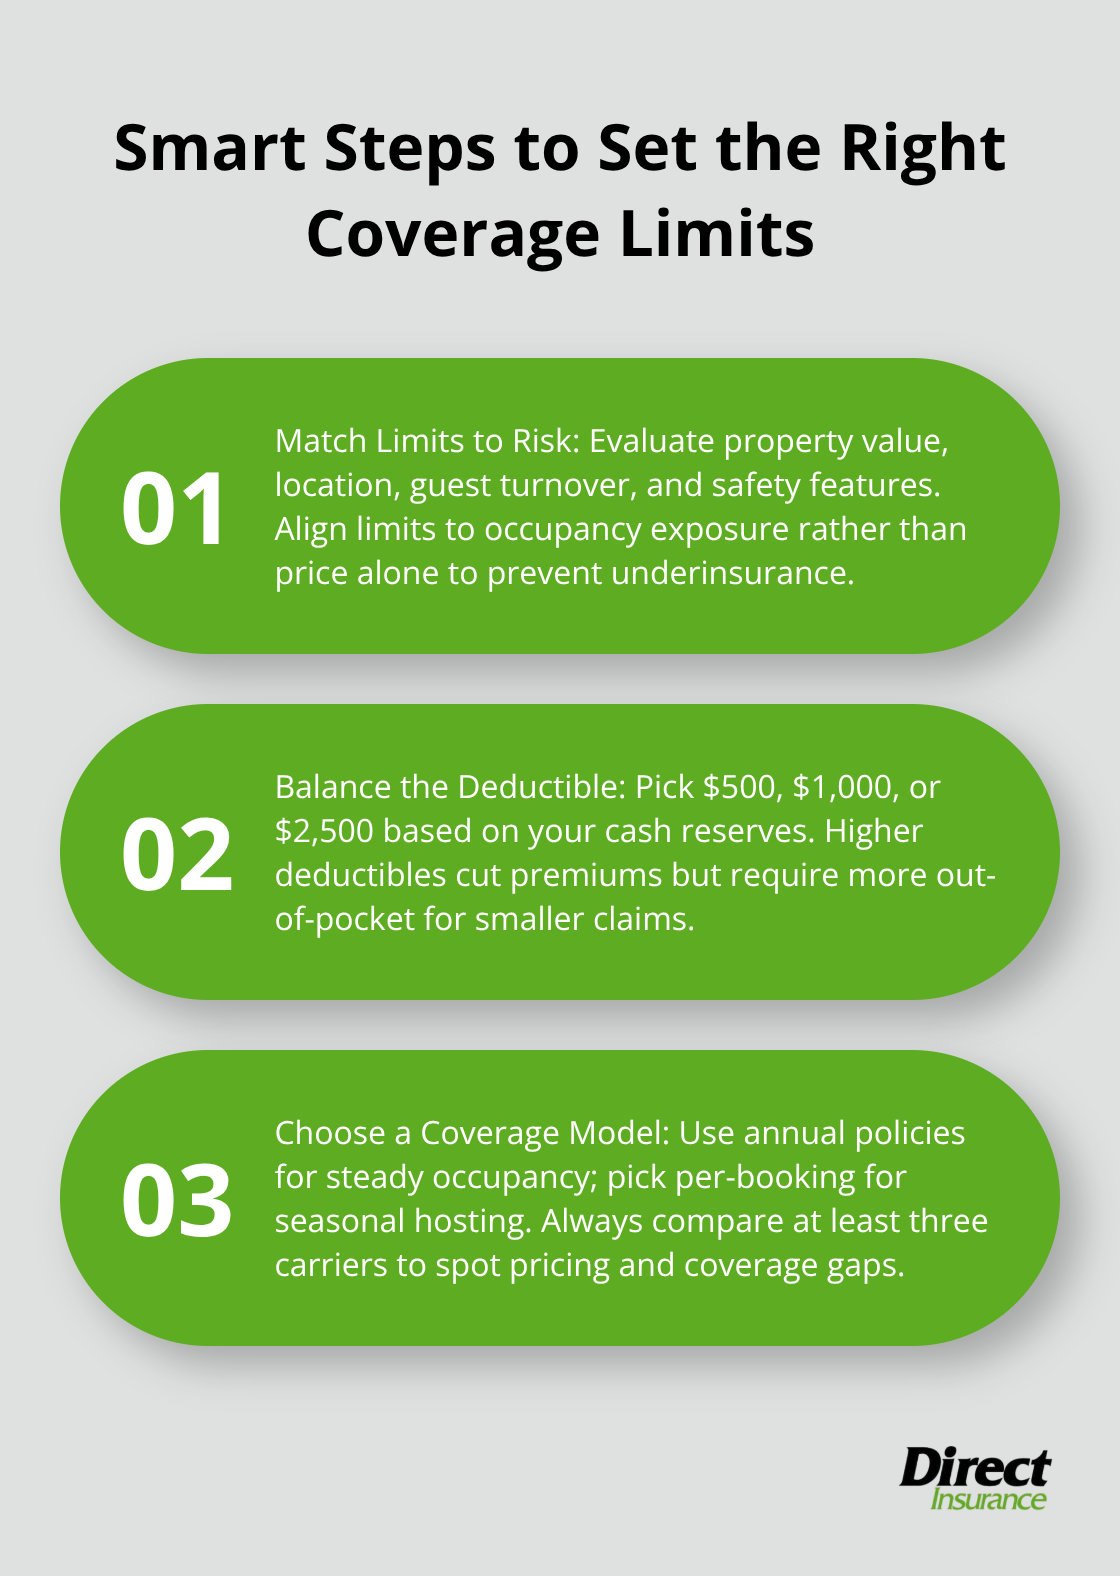
Three-step guide to matching coverage limits, deductibles, and coverage models for vacation rentals. - vacation rental property coverage

Balance Your Deductible Against Your Cash Reserves

Deductibles function as your financial threshold before coverage kicks in. You can select between a $500, $1,000, or $2,500 deductible, and this choice requires balancing monthly premiums against your cash reserves. Higher deductibles reduce premiums substantially but force you to absorb smaller claims from your own funds, making this decision critical for hosts with limited emergency savings.

Verify Your Lender’s Insurance Requirements

Your lender’s insurance requirements appear in your mortgage documents and typically mandate replacement-cost coverage at 80 to 100 percent of your property value, plus minimum liability limits of $300,000 to $500,000. Many hosts discover their chosen policy doesn’t satisfy these requirements only after a claim denial or during a loan review, creating expensive gaps at the worst possible time.

Contact your lender before purchasing any vacation rental policy to confirm exact coverage minimums, and request their written insurance requirements so you have documentation. Obie offers quick digital quotes across all 50 states plus DC, allowing you to compare multiple carriers against your lender’s specific demands without scheduling agent calls. Some carriers like Allstate HostAdvantage provide landlord-style coverage starting around $300 to $800 annually, which appeals to budget-conscious hosts but may fall short of lender requirements for higher-value properties.

Choose Between Annual and Per-Booking Coverage Models

Truvi operates on a per-booking model starting at £13.80 per booking, making it economical for hosts with seasonal or sporadic rental activity who don’t want annual premiums for months of vacancy. The choice between annual policies and per-booking coverage hinges on your occupancy rate-annual policies favor consistent hosts, while per-booking options benefit those with irregular schedules.

Compare Quotes From Multiple Carriers

Obtain quotes from at least three carriers before committing, since premium variations for identical properties can exceed $1,000 annually depending on each insurer’s risk assessment methodology. This comparison process reveals which carriers align with your property type, occupancy patterns, and lender requirements without forcing you into inadequate or overpriced coverage.

Final Thoughts

Protecting your vacation rental property requires three essential coverage types working together. Property damage coverage handles guest-caused repairs and destruction, liability coverage shields you from medical bills and lawsuits when guests get injured, and loss of rental income protection replaces revenue during forced closures. Standard homeowners insurance abandons you across all three fronts, leaving your rental business exposed to financial devastation that can exceed tens of thousands of dollars annually.

Your property type, occupancy rate, location, and lender requirements determine which policy limits actually protect your business rather than leaving dangerous gaps. Contact your mortgage lender first to confirm their minimum coverage demands, then gather quotes from at least three carriers to compare how each addresses your unique risk profile. Carriers like Safely, Proper Insurance, and CBIZ offer different strengths-some prioritize rapid claims processing while others eliminate damage caps for high-value properties-so comparing options prevents you from overpaying or underinsuring your vacation rental property coverage.

A single guest injury lawsuit or major property damage incident can wipe out years of rental income if you lack proper protection. We at Direct Insurance Services help hosts throughout Utah navigate these complexities by connecting you with carriers that match your needs and budget. Contact us to review your current situation and build the protection your rental business actually requires.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
Your vacation rental generates income, but standard homeowners insurance won’t protect it. A short term rental policy fills the gaps that leave your property and income vulnerable when guests stay on your property.

At Direct Insurance Services, we’ve seen too many rental property owners discover coverage holes only after a claim. This guide walks you through the protection you actually need.

Why Standard Homeowners Insurance Won’t Protect Your Rental Income

Standard Policies Exclude Rental Activity

Standard homeowners insurance explicitly excludes rental activity. Your insurer views paying guests as a business operation, not personal use, and refuses to cover property damage, guest injuries, or lost income from that activity. If you file a claim without disclosing your rental activity, the insurer can deny the claim entirely, cancel your policy, or refuse to renew it. The Insurance Information Institute confirms that regular rentals require separate business coverage or a landlord policy because personal policies simply don’t account for the higher risk exposure that comes with transient guests.

The Real Cost of Unprotected Damage

Water damage from a guest-caused incident alone can cost $20,000 to $50,000 if multiple floors are affected, yet your standard policy treats this as your personal loss to absorb. A single guest injury lawsuit can reach six figures in liability costs, and your homeowners policy won’t touch it. Short-term rental policies exist specifically because the risk profile of a vacation rental-frequent turnover, strangers in your home, higher claim frequency-demands different protections than a primary residence.

How Coverage Gaps Appear in Real Situations

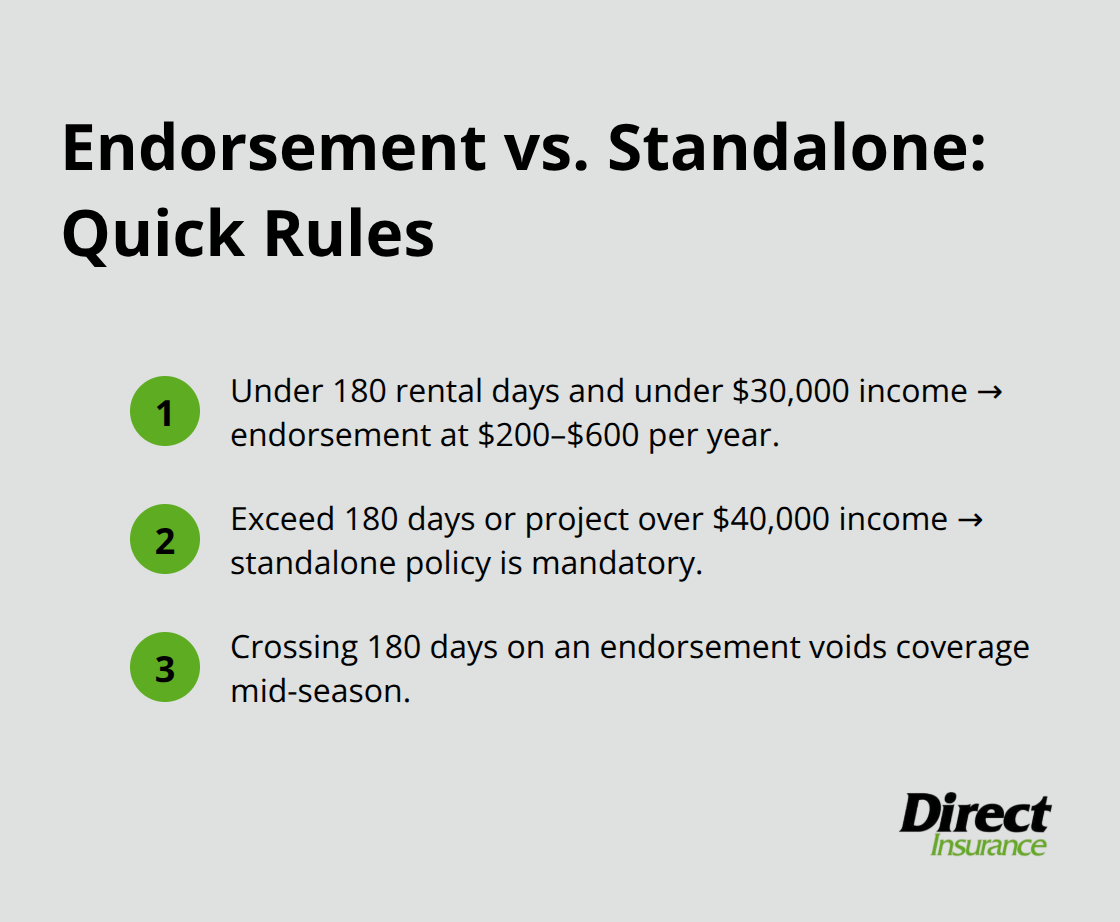
The gaps appear quickly when claims happen. You rent your property for 120 days and a guest damages the kitchen during a cooking accident. Your homeowners insurer denies the claim because you failed to disclose rental use. You lose $8,000 in repairs plus three weeks of bookings while fixing the damage. Alternatively, you purchase an endorsement to your existing policy, which typically costs $200 to $600 annually and caps your rental activity at 180 days per year. Cross that threshold by even one day, and your coverage vanishes.

Why Endorsements Fall Short for Active Rentals

For properties that generate $40,000 to $60,000 annually in rental income, losing coverage mid-season creates catastrophic exposure. Endorsements work for secondary rental activity, but they impose restrictions that serious rental operations cannot tolerate. Standalone policies remove the 180-day restriction entirely, making them suitable for year-round rentals or properties owned through a business entity.

The Three Essential Coverages You Need

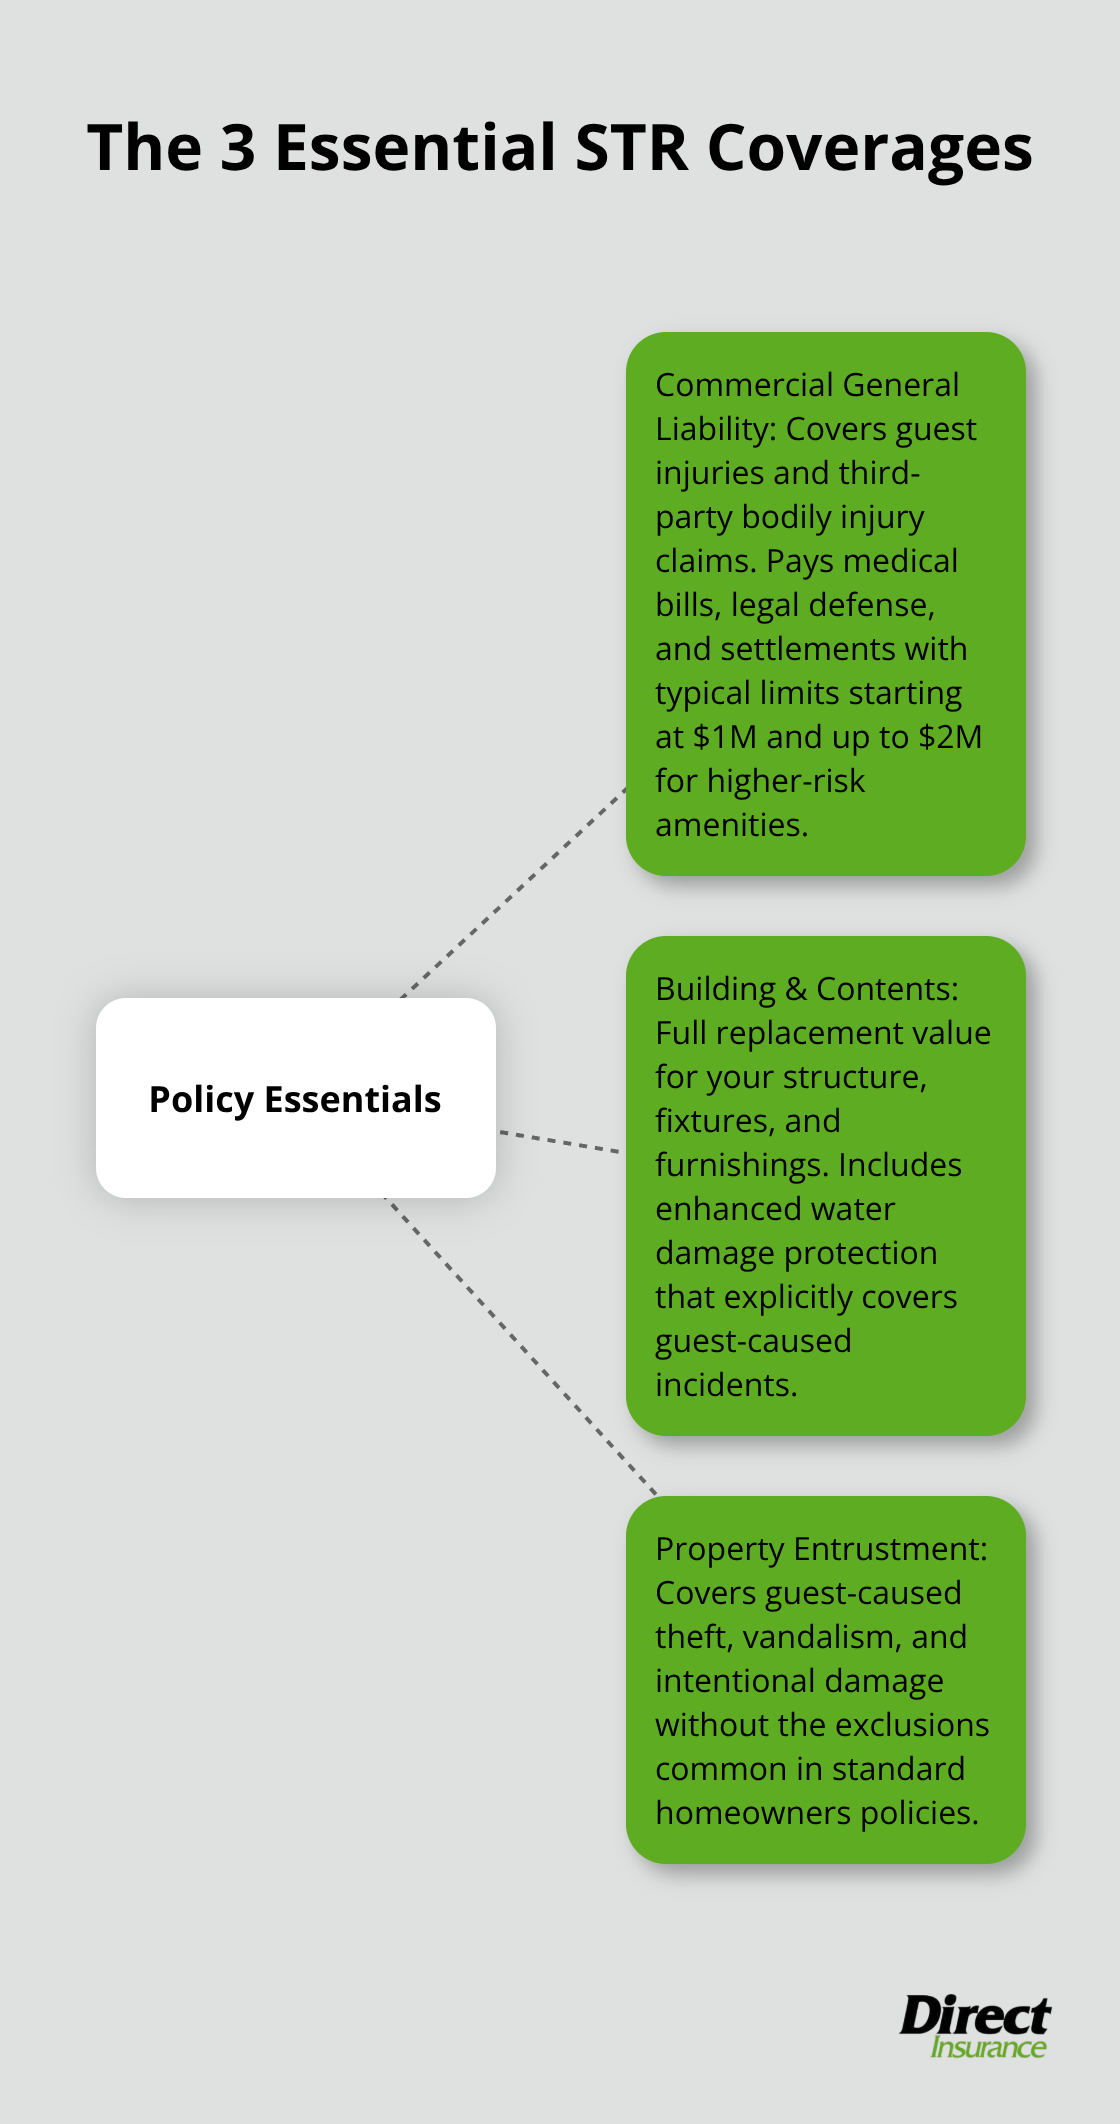
Short-term rental policies address these gaps with three essential coverages: Commercial General Liability with at least $1 million in limits, Building and Contents protection with full replacement value, and Property Entrustment coverage that handles guest-caused theft and vandalism without exclusions. The cost difference between an endorsement and a standalone policy reflects the actual risk you transfer to the insurer. Understanding which type fits your operation determines whether you have adequate protection or face another coverage disaster when the next claim arrives.

Infographic showing the three essential short-term rental insurance coverages radiating from a central hub. - short term rental policy

What Coverage Actually Protects Your Rental Property and Income

Three Essential Layers of Protection

Short-term rental policies deliver three distinct layers of protection that standard homeowners insurance refuses to touch. Commercial General Liability covers guest injuries and third-party bodily injury claims, with minimum limits starting at $1 million and extending to $2 million for properties with higher-risk amenities like pools or hot tubs. This coverage pays medical expenses, legal defense costs, and settlement amounts if a guest is injured on your property and holds you responsible. A single personal liability lawsuit from a guest injury reaches six figures routinely, which is why the liability limit you select directly determines your financial exposure.

Building and Contents Protection

Building and Contents coverage protects the physical structure, fixtures, and your furnishings with full replacement value, including enhanced water damage protection that explicitly covers guest-caused incidents. Water damage from a guest-caused accident costs $20,000 to $50,000 when multiple floors are affected, and your standard homeowners policy will deny the claim if rental activity remains undisclosed. Property Entrustment and Guest Damage Coverage handles theft, vandalism, and intentional damage by guests without the exclusions that plague standard policies. Unlike endorsements that cap rental activity at 180 days annually, standalone policies remove this restriction entirely, making them mandatory if you rent year-round or own the property through a business entity.

Matching Coverage to Your Property

The coverage limits and deductibles you select should reflect your property value and occupancy rate-a $400,000 home with 60% annual occupancy requires different protection than a $1.2 million property rented nearly every week. Loss of income coverage calculates payouts based on the fair market value of rentals in your area, including long-term rentals. This protection runs continuously without time limits, which separates legitimate rental policies from inadequate endorsements that terminate coverage once you exceed 180 rental days. If a guest causes damage requiring three weeks of repairs, your policy covers the lost bookings during that period rather than forcing you to absorb $3,000 to $5,000 in lost revenue depending on your nightly rate.

Deductibles and Platform Requirements

Deductibles for short-term rental policies typically range from $500 to $2,500 per claim, and your choice affects both premiums and out-of-pocket costs when claims occur. Higher deductibles lower annual premiums but increase your personal liability when damage happens, so align this decision with your cash reserves and risk tolerance. Platform requirements from Airbnb, Vrbo, and similar services often mandate proof of insurance, and lacking proper coverage can trigger suspension or lost bookings before you even know a gap exists.

Finding the Right Policy for Your Operation

Specialized STR insurance brokers can provide quotes within 24 hours and identify coverage gaps faster than traditional agents unfamiliar with rental operations. The cost difference between an endorsement at $200 to $600 annually and a standalone policy reflects the actual protection you receive-standalone policies cost more because they remove restrictions and cover the full spectrum of rental activity without artificial limitations. When you work with an independent agency, you gain access to multiple carriers and personalized guidance that matches your specific rental operation to the right coverage structure. The next step involves assessing your property’s unique risk profile and comparing the specific limits and exclusions that separate adequate protection from dangerous gaps.

Choosing the Right Policy for Your Rental Operation

Calculate Your Rental Days and Income

Start by calculating your actual rental days and annual income, because these numbers determine whether an endorsement or standalone policy fits your situation. If you rent fewer than 180 days annually and your property generates under $30,000 in yearly rental income, an endorsement to your existing homeowners policy at $200 to $600 per year makes financial sense. However, if you exceed 180 rental days or project annual income above $40,000, a standalone policy becomes mandatory-crossing the 180-day threshold with an endorsement voids your coverage mid-season, leaving you completely unprotected.

Compact list summarizing when to use an endorsement versus a standalone STR policy.

Match Coverage to Property Value and Amenities

The second critical factor is your property value and amenities. A $300,000 home with standard furnishings requires different liability limits than an $800,000 oceanfront property with a pool and hot tub. Properties with pools, hot tubs, or other high-risk features should carry minimum liability limits of at least $1 million, because these amenities increase guest injury exposure significantly.

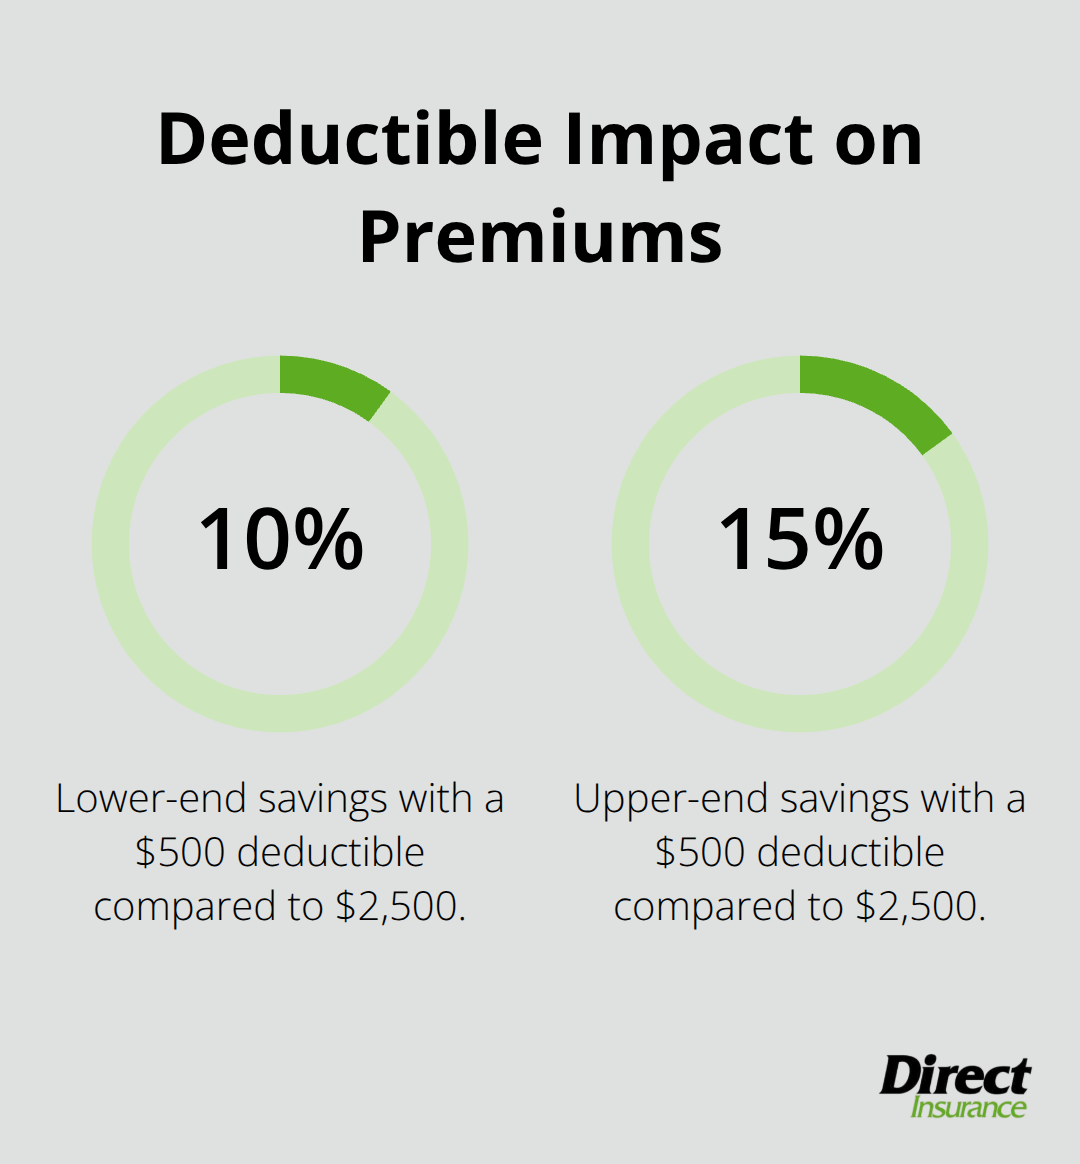
Your deductible choice directly impacts both your premium and out-of-pocket costs when claims happen. A $500 deductible saves roughly 10-15% on annual premiums compared to a $2,500 deductible, but it also means you pay $500 out of pocket for every claim regardless of size. If your property experiences one guest-caused damage incident per year on average, the lower deductible pays for itself immediately. Conversely, if you maintain excellent guest screening and have never experienced property damage, the higher deductible reduces your annual costs without meaningful risk.

Percentage savings on annual premiums with a $500 deductible versus a $2,500 deductible. - short term rental policy

Verify Platform Requirements and Coverage Details

Third, verify what your hosting platform actually requires before purchasing coverage. Airbnb and Vrbo mandate proof of insurance naming them as additional insured parties, and some policies exclude platform liability or communicable disease coverage that these platforms now require. Contact your potential insurer and confirm they cover your specific hosting platform and allow the platform to be added as an additional insured without restrictions.

Fourth, examine the specific exclusions that separate adequate policies from dangerous gaps. Ask your broker whether the policy covers intentional guest damage without exclusions, whether water damage covers guest-caused incidents explicitly, whether loss of income coverage runs continuously without time limits, and whether eviction costs and legal defense are included if a guest refuses to leave. Many policies cap loss of income at 30 or 60 days, which is insufficient if major repairs take eight weeks.

Compare Quotes and Work with Specialized Brokers

Specialized STR insurance brokers can provide quotes within 24 hours and identify coverage gaps that traditional agents miss entirely. Compare at least three quotes from different carriers, because premium differences for identical coverage can exceed $400 annually depending on the insurer’s appetite for rental risk in your specific location. An independent agency works with top-rated carriers to ensure you access the best coverage options without one-size-fits-all limitations.

Update Coverage as Your Operation Expands

Finally, update your policy annually when your property changes. Adding rooms, upgrading amenities, or expanding to additional platforms all increase your risk profile and may require higher liability limits or additional coverage riders. Policies that worked last year may create gaps this year if your rental operation expands.

Final Thoughts

Short-term rental policies protect what standard homeowners insurance refuses to cover, and your vacation rental income depends on guest safety, property protection, and continuous operation. Without proper coverage, a single water damage claim, guest injury lawsuit, or forced closure eliminates months of profit and leaves you financially exposed. The three essential coverages-Commercial General Liability, Building and Contents protection, and Property Entrustment coverage-address the specific risks that endorsements and standard policies ignore.

Your choice between an endorsement and a standalone short term rental policy depends on your rental days and annual income. If you exceed 180 rental days or generate more than $40,000 annually, a standalone policy becomes mandatory because endorsements terminate coverage mid-season. Liability limits of at least $1 million, full replacement value for your furnishings, and loss of income coverage without artificial time limits form the foundation of adequate protection.

The next step involves calculating your actual rental days, property value, and platform requirements, then comparing quotes from at least three carriers. Specialized STR insurance brokers provide quotes within 24 hours and identify coverage gaps that traditional agents miss, understanding the specific exclusions that matter-intentional guest damage coverage, water damage for guest-caused incidents, continuous loss of income protection, and eviction costs if a guest refuses to leave. Contact our team today to review your current coverage and identify gaps in your short-term rental policy.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
Running a contracting business in Utah means navigating specific insurance rules. State law requires certain coverage types, and skipping them puts your business at serious financial risk.

At Direct Insurance Services, we help contractors understand exactly what contractor insurance requirements Utah demands. Getting the right coverage protects your assets and keeps your license valid.

What Coverage Does Utah Law Actually Require?

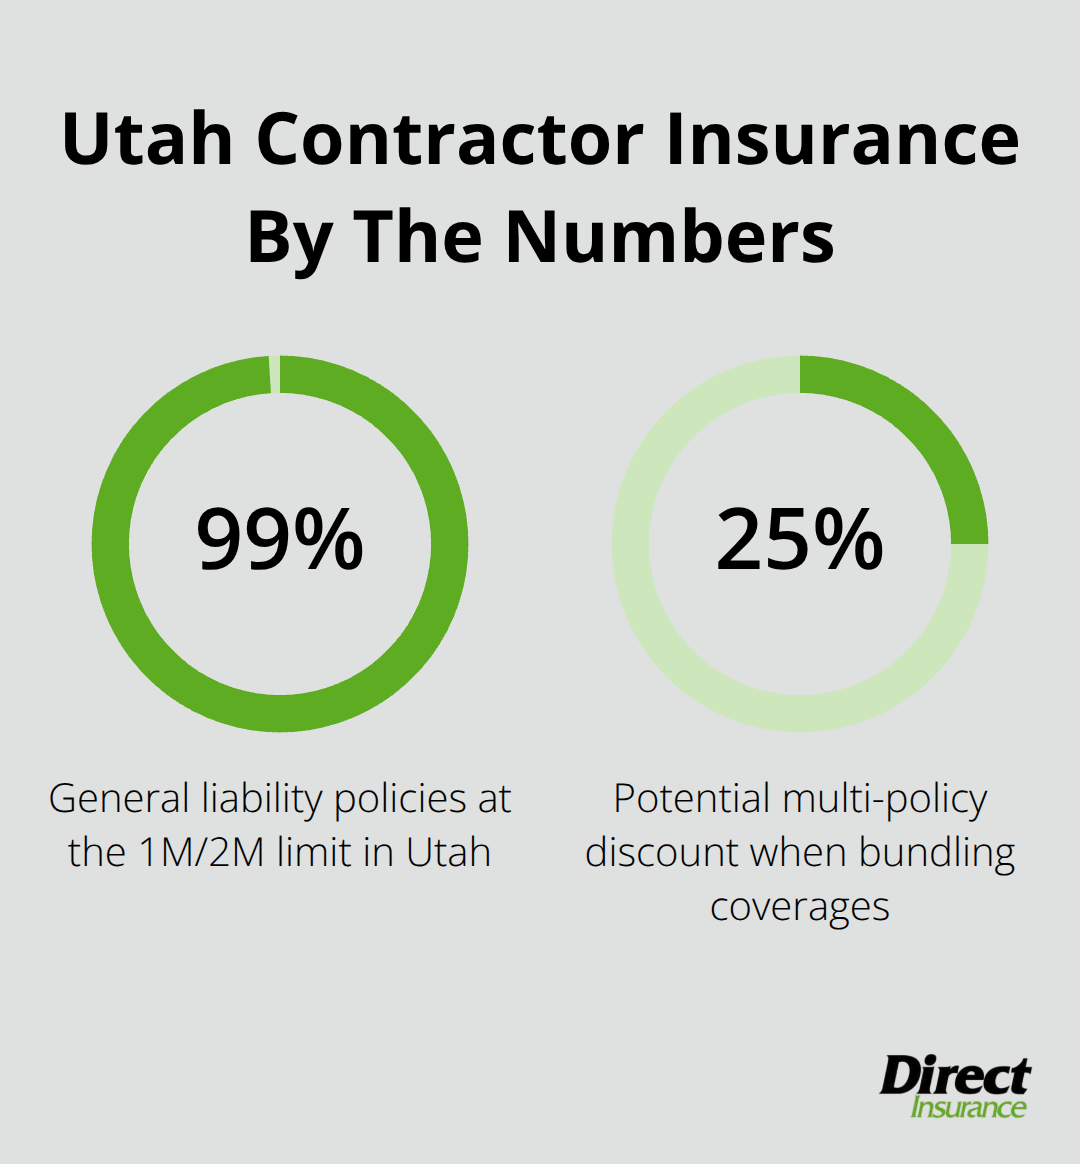
Utah’s construction industry operates under strict insurance mandates, and there’s no flexibility here. If you’re running a contracting business in Utah, state law requires general liability insurance as baseline protection. This coverage protects against bodily injury, property damage, and personal/advertising injury claims on the job site. The standard minimum coverage level in Utah is 1,000,000 per occurrence and 2,000,000 aggregate, commonly written as 1M/2M. About 99% of general liability policies sold in Utah sit at this exact level because it satisfies both state requirements and client demands from project owners and lenders.

Key percentages shaping contractor insurance choices for Utah contractors - contractor insurance requirements Utah

Workers’ Compensation Becomes Mandatory With Employees

Hiring even a single employee in Utah triggers a legal requirement for workers’ compensation insurance. This isn’t optional-the state mandates it, and operating without it exposes you to massive financial liability. Workers’ compensation covers medical expenses, lost wages, and potential permanent disability for injured workers. Without this coverage, you personally absorb these costs out of pocket. Medical bills can reach tens of thousands of dollars for serious injuries, and wage replacement obligations continue for months. The actual cost of workers’ comp varies significantly by trade. Roofers and demolition contractors pay substantially more than painters or landscapers because their work carries higher injury risk. Your payroll size also matters; a solo contractor pays far less than a business with five employees on the same trade classification.

Commercial Auto Insurance for Business Vehicles

Any vehicle you use for business purposes in Utah must carry commercial auto insurance rather than personal coverage. This is non-negotiable. Personal auto policies specifically exclude business use, so you remain completely uninsured if something happens while you transport materials or visit a job site. Commercial auto typically includes property damage, bodily injury, and liability coverage. Most Utah contractors benefit from collision and comprehensive coverage as well, especially if you transport expensive equipment or tools. A recommended auto liability limit is 1,000,000 Combined Single Limit for both bodily injury and property damage combined.

License Requirements Connect to Insurance Proof

Utah requires licensed general and specialty contractors to carry general liability insurance as a condition of maintaining their license. This means your insurance isn’t just financial protection-it’s a legal requirement to operate legally. When you bid on projects or secure permits, clients and government agencies frequently request ACORD certificates as proof of current coverage. These standardized documents show your coverage is active and at adequate limits. You should keep a current ACORD certificate on hand at all times. Beyond general liability, if you hire subcontractors or employees, you’ll need workers’ compensation documentation as well. Some projects demand additional coverages like builders risk insurance for construction projects or professional liability for design-build work.

Coverage Limits Scale With Project Risk

Higher-risk situations justify higher coverage limits. A $5 million commercial project requires different protection than a $50,000 residential job. The complexity and value of your work determine how much coverage you actually need to protect your business from catastrophic loss. Understanding these distinctions helps you avoid both underinsurance and unnecessary overpayment. Once you know what Utah law requires, the next step involves finding the right carrier and comparing quotes to lock in competitive rates.

The Three Core Coverages Every Utah Contractor Must Understand

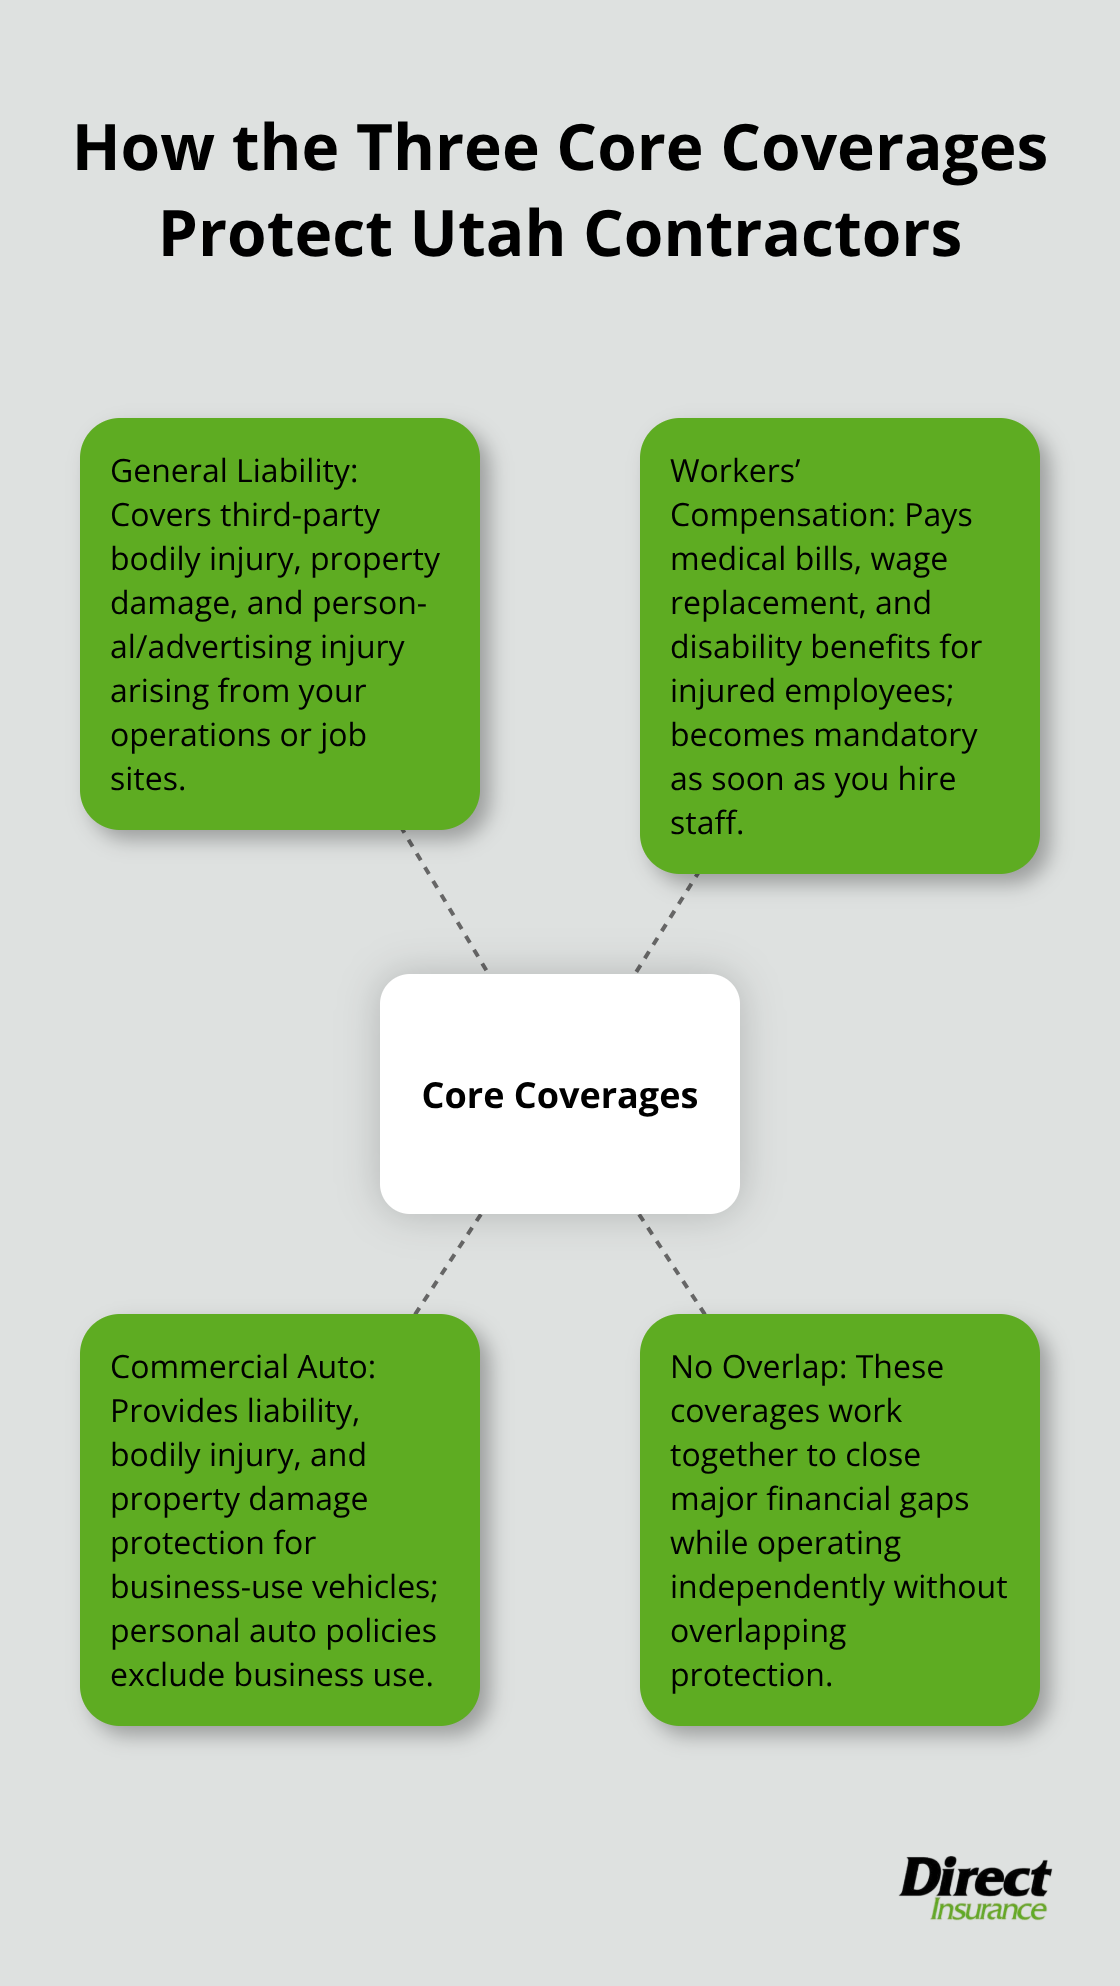
General liability, workers compensation, and commercial auto form the foundation of contractor insurance in Utah, but each serves a completely different purpose and protects against distinct financial threats. General liability shields your business when someone claims you damaged their property or caused them bodily injury on a job site. A $500,000 property damage claim from a client whose home you accidentally flooded during renovation work would devastate an uninsured contractor. Workers compensation covers your employees when they get hurt, and this is where contractors often underestimate their actual exposure. A single serious injury can generate $100,000 or more in medical bills and wage replacement costs spanning months. Commercial auto insurance is mandatory whenever you use a vehicle for business, and personal auto policies explicitly exclude business use, leaving you completely exposed if you’re in an accident while transporting materials or traveling between jobs. These three coverages work together to prevent catastrophic financial loss, but they operate independently and none overlaps with the others.

Diagram showing general liability, workers’ compensation, and commercial auto roles for contractors - contractor insurance requirements Utah

General Liability Costs Less Than You Think

General liability insurance for contractors typically costs between $750 and $2,500 annually for small-to-mid-sized contractors with a standard $1M/$2M policy. The actual premium depends on your trade classification, with lower-risk trades like painting and landscaping paying substantially less than higher-risk work like roofing or demolition. A solo painter might pay less per year while a roofing contractor with three employees could pay toward the higher end for the same coverage limits. The 1M/2M standard that dominates Utah contracting exists because it satisfies state requirements, client demands, and lender requirements simultaneously, so shopping for lower limits rarely saves money and creates serious gaps in protection. Some contractors attempt to avoid general liability by working as solo operators, but this strategy fails instantly when a client demands ACORD certificates before you start work or when a single incident threatens your business existence.

Workers Compensation Varies Dramatically by Trade and Payroll

Workers compensation insurance costs fluctuate wildly depending on what type of work you perform and how many employees you have. A roofing contractor with five employees pays significantly more than an electrician with the same crew size because roofing carries higher injury frequency and severity. HVAC contractors, plumbers, and electricians typically fall in the moderate-cost range, while general contractors overseeing multiple trades often pay premium rates. Payroll size matters enormously-your premium scales directly with how much you pay your employees, so adding a second worker increases your cost substantially. A contractor with $200,000 in annual payroll pays roughly double what a solo operator pays for the same coverage. Clean claims history reduces your rates, so avoiding worker injuries directly saves money on future premiums. Many Utah contractors overlook that workers compensation covers not just medical expenses but also permanent disability benefits, which can run into hundreds of thousands of dollars for catastrophic injuries.

Commercial Auto Insurance Requires Specific Business Endorsements

Personal auto insurance explicitly excludes business use, which means you have zero coverage if you’re involved in an accident while transporting equipment or traveling to a job site. Commercial auto policies provide the coverage you actually need, including property damage, bodily injury, and liability protection. A 1,000,000 Combined Single Limit protects both bodily injury and property damage combined, which is the standard most Utah contractors should carry. Collision and comprehensive coverage protects your own vehicle from damage, and contractors with expensive equipment or tools in their vehicles should absolutely carry these additions. Your premium depends on the vehicle type, driving records of anyone operating company vehicles, and the distance you travel for work. A contractor who drives five miles across town occasionally pays far less than someone who travels statewide regularly. If you have employees driving company vehicles, their driving records affect your rates, so hiring safe drivers directly reduces your insurance costs.

Finding the Right Coverage for Your Situation

The three core coverages protect different aspects of your contracting business, but determining the right limits and add-ons requires honest assessment of your actual operations. Your trade classification, payroll size, vehicle usage, and project types all influence what you truly need. Once you understand these fundamentals, the next step involves comparing quotes from multiple carriers to find coverage that matches both your requirements and your budget.

Getting Contractor Insurance in Utah

At Direct Insurance Services, we work with contractors daily who struggle with the actual mechanics of purchasing insurance. The process feels overwhelming, but breaking it into concrete steps eliminates the confusion. You need to know exactly what to expect when shopping for coverage, how to compare quotes accurately, and what policy language actually means for your business protection.

Start With an Independent Agent Who Understands Utah Contracting

An independent insurance agent changes everything because they represent your interests, not a single insurance company’s bottom line. An independent agent in Utah accesses multiple carriers and shows you real premium differences across providers for identical coverage. This matters enormously because general liability rates for the same 1M/2M policy can vary by 30 to 40 percent between carriers, meaning an agent can save you hundreds of dollars annually just through carrier selection.

When you call an agent, have your business details ready: your trade classification, annual payroll if you have employees, number of years in business, and your claims history. Agents who specialize in contractor insurance understand Utah’s specific requirements and know which carriers offer the best rates for your particular trade. A roofing contractor needs an agent who understands roofing risks, not someone selling generic commercial policies.

Ask potential agents directly how many contractor clients they serve and whether they work with carriers that specialize in construction trades. An agent should explain why one carrier costs more than another for seemingly identical coverage, usually because of underwriting philosophy or claims experience in your specific trade. Utah contractors report that working with someone who understands their work reduces confusion and prevents coverage gaps that emerge later when claims happen.

Gather Quotes From Multiple Carriers

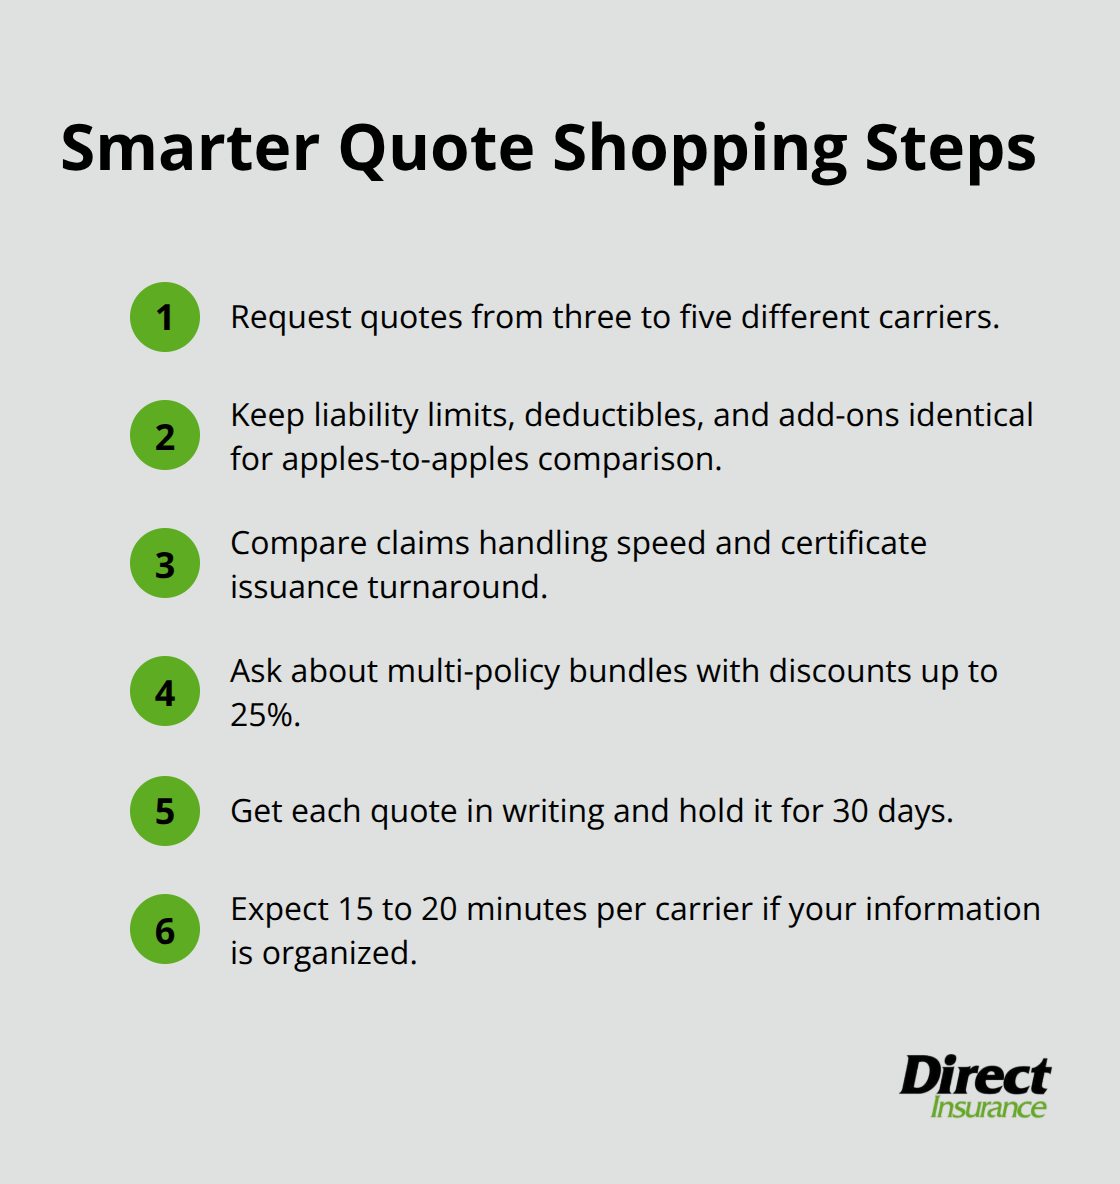
Never accept the first quote you receive because premium variation between carriers is substantial and predictable. Request quotes from three to five different carriers using identical coverage specifications: same liability limits, same deductibles, same add-on coverages. This forces apples-to-apples comparison instead of getting confused by different policy structures.

Compact checklist for comparing contractor insurance quotes in Utah

When you receive quotes, the lowest price isn’t automatically the best choice because some carriers are aggressive on pricing but slower on claims handling, while others charge more but have superior customer service records. Ask each carrier about their average claim response time and whether they offer same-day certificate issuance, which matters when you need ACORD documents quickly for permit applications or job starts.

Some carriers bundle general liability, workers compensation, and commercial auto together at discounts reaching 25 percent compared to purchasing policies separately, so always ask about multi-policy discounts. Get a quote in writing and keep it for at least 30 days while you make your decision. Expect the quote process to take 15 to 20 minutes per carrier if your information is organized. Online quote tools work for general liability but workers compensation and commercial auto typically require direct agent interaction because the underwriting involves more questions about your specific operations.

Understand What Your Policy Actually Covers and What It Excludes

Policy language determines whether you’re protected or exposed when claims happen, but most contractors never read their actual policies. After you select a carrier, request a specimen policy and read the coverage sections, exclusions, and conditions before signing anything.

General liability policies exclude certain work like waterproofing, asbestos work, and pollution liability, so understand whether your specific services are covered or require endorsements. Workers compensation has few exclusions in Utah, but independent contractors and sole proprietors are typically excluded from coverage even if you hire them, meaning you need different protection structures if you use subcontractors regularly. Commercial auto policies exclude coverage for contractors who operate as common carriers or haul materials for hire, which matters if you transport materials as part of your service offering.

Ask your agent to explain three specific things: what happens if someone claims you caused injury but the injury wasn’t immediately obvious, what the process is for filing a claim, and whether coverage limits apply per occurrence or annually. Some contractors discover too late that their policy has a contractual liability exclusion, meaning they can’t claim coverage for damages they contractually promised to cover in their project agreements.

Request endorsements like contractual liability coverage, hired and non-owned auto coverage if employees drive personal vehicles for work, and tools and equipment coverage if you leave equipment on job sites. The policy document itself is the contract, not the marketing materials or agent explanations, so understanding it prevents nasty surprises when you actually need coverage.

Final Thoughts

Utah’s contractor insurance requirements protect your business from financial catastrophe, and skipping coverage exposes you to claims that exceed six figures. A single serious injury to an employee or property damage claim from a client destroys contracting businesses operating without proper protection. General liability, workers compensation, and commercial auto insurance satisfy state law, client demands, and lender requirements simultaneously, making them non-negotiable investments in your business survival.

Working with an independent agent who understands Utah contracting saves hundreds of dollars annually because premium variation between carriers for identical coverage reaches 30 to 40 percent. Read your actual policy documents before signing anything because exclusions determine whether you’re protected or exposed when claims happen. Request endorsements like contractual liability coverage and tools and equipment protection based on your specific operations and job site risks.

We at Direct Insurance Services help Utah contractors secure the contractor insurance requirements Utah demands while matching your business needs and budget. Get a quote today and protect your contracting business with coverage that actually works when you need it.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
Teen drivers face insurance premiums that are significantly higher than adult drivers. At Direct Insurance Services, we know that parents and teens need practical strategies to find affordable auto insurance for teens without sacrificing protection.

This guide walks you through why rates are steep, which discounts actually work, and how to pick coverage that fits your budget and keeps your family safe.

Why Teen Drivers Cost More to Insure

Teen drivers represent a measurable risk that insurers cannot ignore. The statistics are stark: drivers aged 16 to 19 have a fatal crash rate almost three times as high as drivers ages 20 and older per mile driven, according to data from the CDC. When a crash happens, teen drivers are more likely to suffer serious injury or death. This isn’t opinion-it’s the foundation of how insurance companies calculate premiums. Insurers use decades of accident data to determine that a 16-year-old behind the wheel costs them significantly more in claims than a 40-year-old.

Three key reasons teen auto insurance rates are higher than adults

Age alone matters because it correlates directly with crash risk. A teen’s brain is still developing the judgment and impulse control that safe driving requires. They take more risks, react more slowly to hazards, and underestimate dangerous situations. Insurance companies price accordingly because they know the statistical reality: younger drivers file more claims, and those claims tend to be larger.

Experience Gaps That Show Up in Premiums

Experience matters enormously, and teens have none. An adult driver with 20 years of clean driving history has proven they can handle unexpected road situations. A 16-year-old with a learner’s permit has not. Insurance companies weight this heavily-they cannot predict how a teen will perform once they’re driving independently. Limited track records mean insurers must assume worst-case scenarios and price accordingly. A 25-year-old driver with five years of clean driving receives better rates than a 17-year-old, even if both have accident-free records, because time on the road builds credibility. The longer a driver goes without an accident, the more confident insurers become. Teens simply haven’t had enough time to build that confidence, so they pay more.

How Age-Based Calculations Actually Work

Insurance companies don’t charge teen rates arbitrarily-they use actuarial tables built from millions of claims. These tables show that a 16-year-old pays roughly double what a 25-year-old pays for identical coverage. The decline happens gradually. Premiums drop year after year as teens age, especially if they maintain a clean driving record, often continuing until around age 25 when the brain’s risk-assessment regions fully mature. This is why a teen turning 18 might see a modest rate decrease, but the biggest drops happen between ages 19 and 25. Some states have different calculations, and some insurers adjust rates differently, but the pattern remains consistent: youth equals higher cost. The good news is this situation improves predictably. A teen who avoids accidents will see their rates decline noticeably each year, making insurance more affordable as they age and build their record.

What This Means for Your Family’s Budget

Understanding why teen insurance costs more helps you prepare financially and make smarter decisions. You can’t eliminate the age factor, but you can control other variables that insurers consider (vehicle choice, coverage levels, and available discounts). The next section shows you exactly which discounts work and how to lower your teen’s premiums without leaving your family underprotected.

How to Actually Cut Teen Insurance Costs

The age factor is locked in, but nearly everything else about your teen’s insurance is negotiable. The difference comes down to three concrete actions: qualifying for the discounts that actually exist, choosing the right vehicle, and bundling intelligently.

Good Student Discounts Reward Academic Performance

Start with the good student discount, which delivers real money. State Farm offers up to 25% savings for teen drivers with a 3.0 GPA or higher, ranking in the top 20% of their class, or making the Dean’s List or Honor Roll, with savings extending until age 25. If your teen’s base premium runs $1,800 annually, a 25% reduction saves $450 per year. The catch is simple: your insurance company needs proof. Request official transcripts from your teen’s school and submit them to your agent before the policy starts. Update the discount if your teen’s grades improve mid-policy. Many families leave this money on the table because they assume their insurer will automatically know their teen’s academic standing. They won’t. You must tell them and provide documentation.

Defensive Driving Programs and Telematics Monitoring

Defensive driving courses deliver measurable value beyond the classroom. A teen who completes an approved driver education course qualifies for a driver training discount, and some states offer additional savings through programs like Steer Clear or Drive Safe & Save. These programs monitor actual driving behavior through a mobile app or a small device plugged into your vehicle’s diagnostic port, rewarding safe habits with discounts up to 30% for users of telematics programs like RightTrack. If your teen drives safely and earns a 20% discount through a monitoring program, that’s $360 off a $1,800 premium. Your teen’s driving score improves as they practice, and their confidence grows alongside the proof of their safe habits.

Percentage savings from common teen driver discounts - auto insurance for teens

Vehicle Selection Impacts Insurance Costs Significantly

Vehicle selection matters more than most parents realize. A 2020 Honda Civic costs far less to insure than a 2020 Dodge Charger because repair costs and safety ratings differ dramatically. Insurance companies know that a Civic’s parts are cheaper and its safety features stronger. When shopping for your teen’s first car, try vehicles with high safety ratings from the National Highway Traffic Safety Administration, proven reliability records, and reasonable repair costs. A $12,000 used Honda Accord might have a lower insurance premium than a $10,000 used sports coupe.

Bundle Policies for Maximum Savings

Finally, bundle your auto and home policies. Customers who bundle auto and home insurance save over $950 annually according to industry data, with potential additional savings when adding other products like umbrella coverage. If you’re not bundling yet, contact your agent immediately. This single move often outpaces any individual discount in raw dollars saved. Once you’ve locked in these savings, the next step involves selecting the right coverage levels for your teen’s specific situation and driving patterns.

What Coverage Do Teen Drivers Actually Need

Utah’s Liability Requirements and Why Minimums Fall Short

Utah requires every driver to carry liability insurance with minimum limits of 25/65/15, meaning $25,000 for bodily injury per person, $65,000 for bodily injury per accident, and $15,000 for property damage. These minimums exist because they cover the legal threshold, but they fall short in real-world accidents. A single serious injury can rack up $100,000 in medical bills alone, leaving your family exposed if you stick with state minimums. Higher limits cost only slightly more than minimums but protect your assets far better. If your teen causes an accident that injures two people with $60,000 in medical costs each, the 25/65/15 minimum leaves you personally liable for $55,000 after insurance pays out. We recommend carrying at least 100/300/100 coverage to eliminate that gap.

Collision, Comprehensive, and Medical Payments Coverage

Collision coverage protects your teen’s vehicle when they hit another car or object, while comprehensive coverage handles theft, weather, vandalism, and animal strikes. If your teen’s car is financed or leased, your lender requires both. If you own the vehicle outright, collision and comprehensive become optional, but dropping them on a $15,000 car makes sense only if you can absorb a total loss. For a $5,000 used car, skipping these coverages or raising your deductible to $1,000 saves real money monthly without creating catastrophic risk.

Medical payments coverage pays your teen’s medical bills regardless of fault, up to your chosen limit, typically $1,000 to $5,000. Uninsured and underinsured motorist coverage protects your teen if hit by a driver with insufficient insurance or no insurance at all, covering injuries and vehicle damage.

Hub-and-spoke showing essential coverages for Utah teen drivers - auto insurance for teens

In 2022, 14.0 percent of motorists, or about one in seven drivers, were uninsured, making this coverage genuinely valuable.

How Usage-Based Insurance Programs Reward Safe Driving

Usage-based insurance programs track your teen’s actual driving through a mobile app or a small plug-in device, rewarding safe habits with concrete discounts. RightTrack, offered through major carriers, can save safe teen drivers up to 30% on premiums. The program monitors acceleration, braking, speed, and time of day, scoring your teen’s performance continuously. A teen who drives safely receives lower rates; one who speeds or accelerates aggressively sees higher premiums or no discount at all. This creates immediate incentive alignment: your teen benefits financially from driving safely, not just from avoiding accidents.

The feedback loop works because teens see their score improve in real time, making safe driving tangible and rewarding. Steer Clear and Drive Safe & Save operate similarly with varying availability by state and coverage type. These programs typically require opt-in and work best for families committed to monitoring their teen’s habits. Some parents hesitate because they worry about invasion of privacy, but the financial incentive shifts teen behavior measurably. A teen earning a 20% discount through safe driving habits saves $360 annually on an $1,800 base premium, money that adds up over multiple years of clean driving. Start with the program your teen’s insurance company offers, then evaluate whether the discount justifies the monitoring for your family’s comfort level.

Final Thoughts

You now have a clear roadmap for finding affordable auto insurance for teens without sacrificing protection. Three concrete actions drive real savings: claim every discount your teen qualifies for, select a vehicle with lower insurance costs and strong safety ratings, and bundle your policies to unlock immediate savings. A teen with a 3.0 GPA who completes a defensive driving course and drives a safe, reliable vehicle will pay substantially less than one who skips these steps, with the good student discount alone saving hundreds annually.

Balancing affordability with adequate protection means rejecting Utah’s minimum liability limits in favor of higher coverage that actually protects your family’s assets. Choose collision and comprehensive coverage on financed vehicles, and evaluate whether dropping these coverages on older cars makes financial sense. Enroll your teen in a usage-based insurance program if your carrier offers one-this turns safe driving habits into measurable discounts that reward behavior you want to encourage anyway.

Contact Direct Insurance Services to discuss your teen’s auto insurance for teens needs and receive a personalized quote tailored to your specific situation. Our team understands Utah’s insurance landscape and works with top-rated carriers to find coverage that fits your budget and protects your family. We help you navigate discounts, compare coverage options, and build a policy that makes sense for your household.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
Utah homeowners face unique insurance challenges due to the state’s diverse climate and terrain. From wildfire risks in certain regions to hail damage in others, your coverage needs differ from those in other states.

At Direct Insurance Services, we’ve helped countless Utah residents find the right balance between solid protection and affordable premiums. This guide walks you through practical homeowners insurance tips for Utah so you can make informed decisions about your policy.

What Utah Homeowners Insurance Actually Covers

The Four Pillars of Standard Utah Coverage

A standard Utah homeowners policy protects you across four essential areas: your dwelling structure, personal property inside it, liability protection if someone is injured on your property, and additional living expenses if you need temporary housing after a covered loss. The dwelling coverage helps cover the cost of repairing or rebuilding your home if it’s damaged by certain hazards, while personal property coverage reimburses you for damaged belongings like furniture, electronics, and clothing. Personal liability protection shields you if you’re found responsible for someone’s injury or property damage, and medical payments to others covers minor injuries on your property without requiring fault.

Diagram showing the four core protections in a standard Utah homeowners policy: dwelling, personal property, liability, and additional living expenses. - homeowners insurance tips Utah

What’s Covered and What Isn’t

Wind and hail damage fall under standard coverage in Utah, as do losses from fallen trees, structural collapse from heavy snow or ice, and wind-driven rain. However, standard policies explicitly exclude flood damage, water backup from sewers or drains, and earthquake damage-these require separate endorsements or policies. Water damage presents a particular challenge: interior water from a storm receives coverage only if exterior damage occurs first, but frozen pipe damage may not be covered if your negligence caused it, such as failing to maintain adequate heat during winter months. The National Association of Insurance Commissioners notes that understanding these boundaries prevents costly surprises when you file a claim.

Utah’s Unique Climate Risks

Utah’s climate and terrain create specific coverage gaps you must address. Flash flooding occurs regularly across the state’s desert regions, especially after heavy rainfall, yet flood insurance isn’t included in standard policies and must be purchased separately through the National Flood Insurance Program. Wildfire risk varies significantly by county and elevation, affecting both your coverage needs and premium costs. Summit County residents, for example, face median annual premiums of $2,829.61 by 2026 according to recent data, compared to the statewide average of $1,541, largely because higher elevations and terrain increase exposure to weather-related losses.

Replacement Cost Versus Actual Cash Value

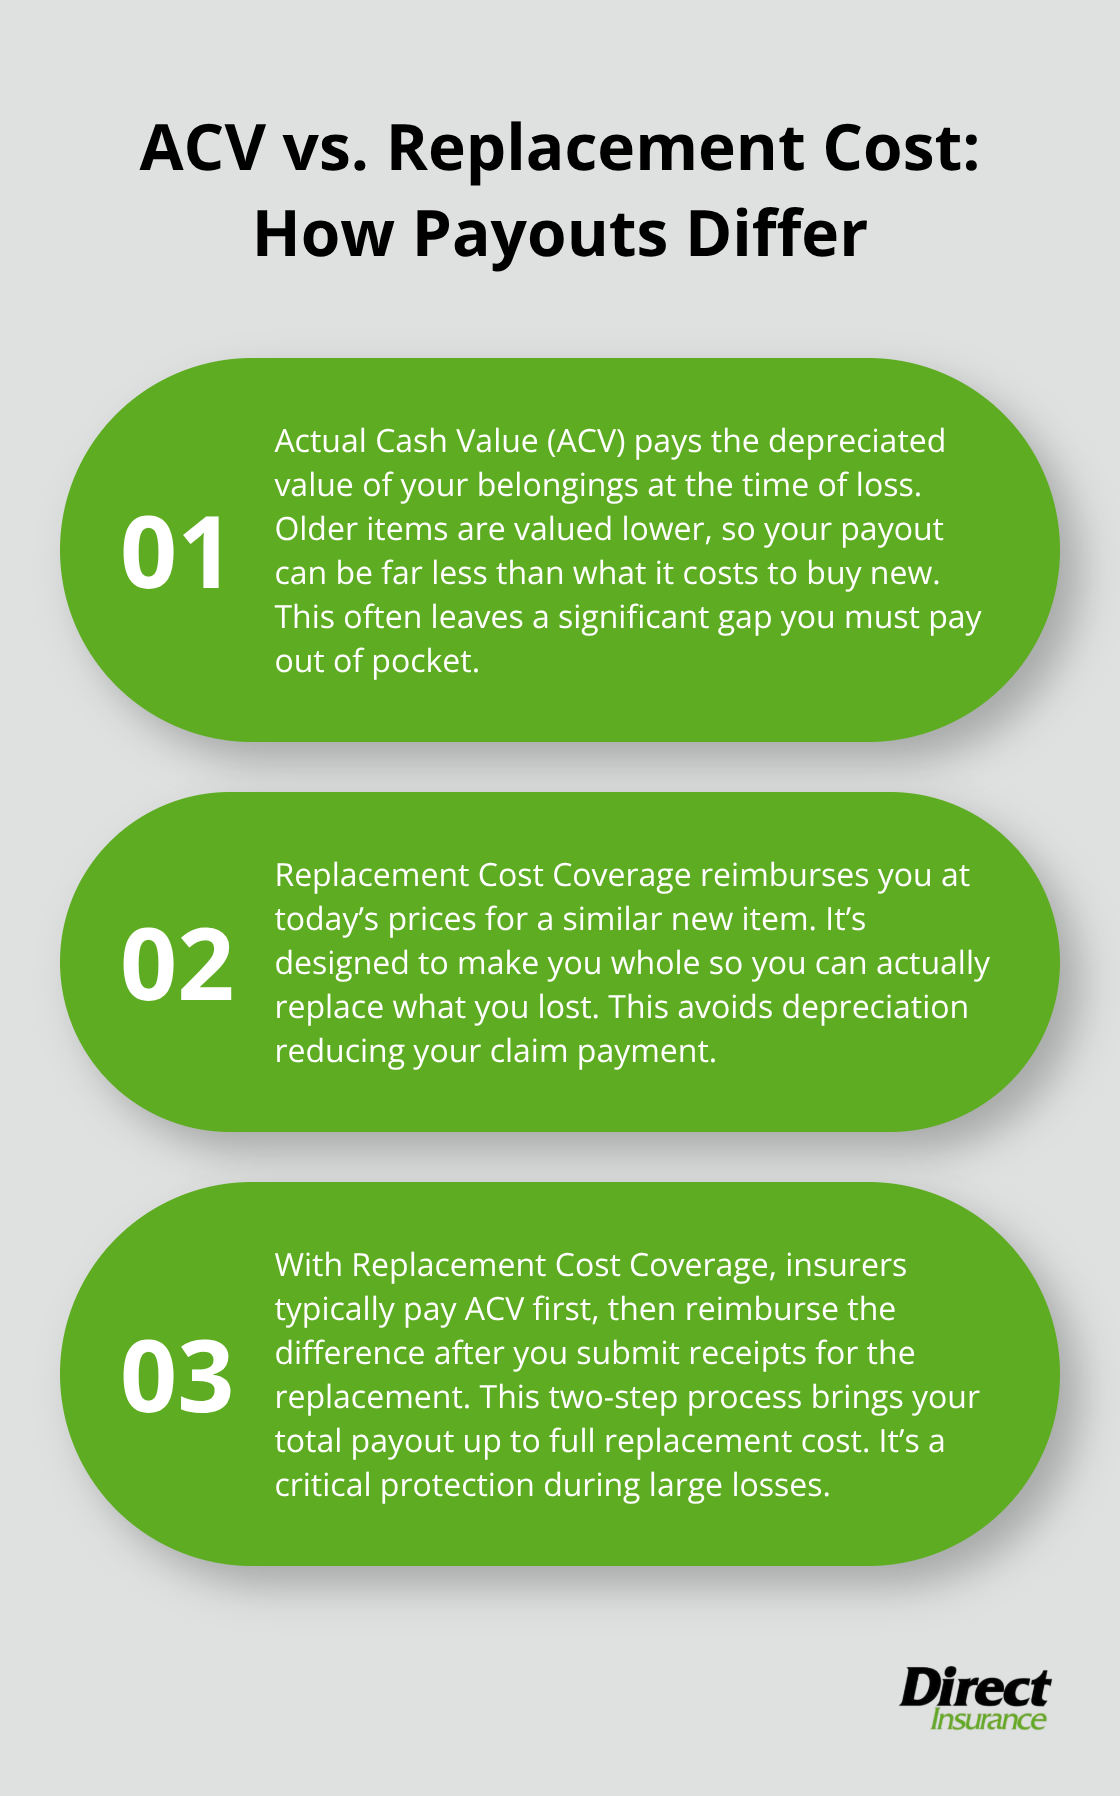
Ask whether your policy includes replacement cost value or actual cash value for contents-replacement cost pays to replace items with new equivalents, while actual cash value deducts depreciation, making a significant difference in claim payouts. A $10,000 water damage claim might net you $7,000 with actual cash value but $10,000 with replacement cost coverage. This distinction directly impacts what you receive when you file a claim, so clarify this detail before you purchase your policy.

Tailoring Coverage to Your Property

Winter hazards like ice dams and frozen pipes demand that you maintain consistent home heating and proper attic ventilation to qualify for full coverage. Before you purchase a policy, request a detailed comparison of what each insurer covers for wind, hail, water damage, and winter-related losses, since coverage terms vary between companies. Work with a local agent to identify endorsements for high-risk areas on your property, such as sump pump backup coverage if your basement floods regularly or water damage from sewer backups if your neighborhood experiences drainage issues. These targeted additions address the specific vulnerabilities of your Utah home and help you avoid protection gaps that could prove expensive later.

How to Cut Your Utah Homeowners Insurance Costs

Combine Your Policies for Immediate Savings

Bundling your homeowners and auto policies with the same insurer delivers the most direct path to lower premiums. Utah homeowners who combine both policies save approximately $950 depending on coverage details and the insurer you choose, according to industry data. When you shop for quotes, request the bundled rate explicitly-some insurers advertise bundling but don’t automatically apply the discount. Verify the total savings across both policies rather than focusing on the homeowners rate alone, since some companies offer a modest home discount but substantial auto savings, or vice versa. The bundling discount typically ranges from 10 to 25 percent depending on the carrier, but the actual dollar savings matters more than the percentage. Start with quotes from at least three insurers and compare the combined annual cost for both policies side by side.

Qualify for Safety and Security Discounts

Monitored security systems, burglar alarms, smoke detectors, and deadbolt locks reduce your risk profile in the eyes of underwriters and qualify you for measurable premium reductions. Sprinkler systems also qualify for discounts in many cases. Request specific discount amounts from each insurer before you install anything, since the savings vary depending on your insurance provider, your policy, and the type of security system you have. The upfront cost of a monitored security system typically ranges from $300 to $500 plus monthly monitoring fees of $10 to $25, so calculate whether the annual discount justifies the investment over multiple years. If you upgrade your home’s heating, plumbing, wiring, or roof, inform your insurer immediately since these improvements often qualify you for preferred or discounted rate programs, particularly for older homes that previously didn’t qualify for better pricing.

Adjust Your Deductible Strategically

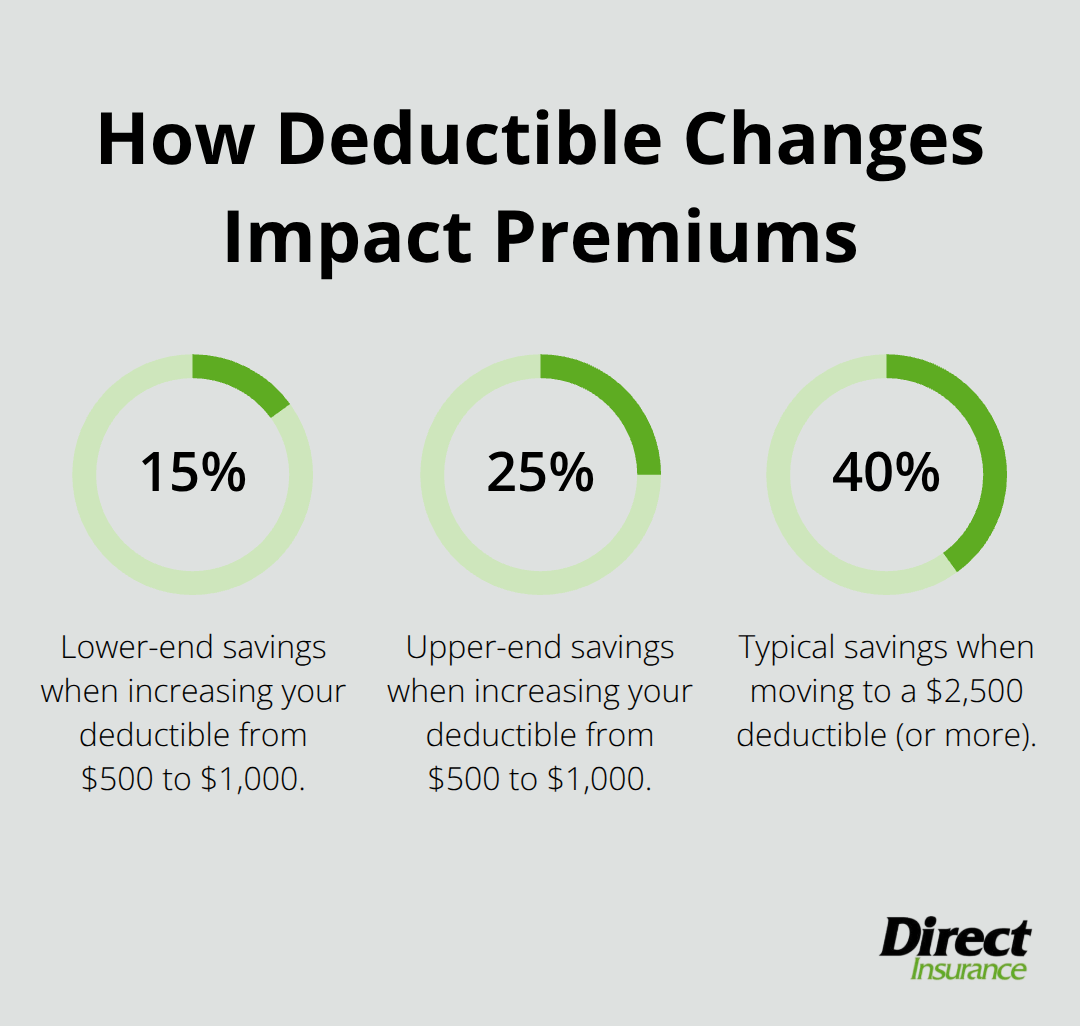
Raising your deductible directly lowers your premium, but only if you have sufficient savings to cover the higher out-of-pocket cost when you file a claim. Moving from a $500 deductible to $1,000 typically reduces your annual premium by 15 to 25 percent, while jumping to a $2,500 deductible can cut costs by 40 percent or more. However, this strategy backfires if a hail storm damages your roof and you lack $2,500 in accessible funds to pay before your insurer reimburses you.

Percentage reductions in homeowners premiums from common deductible increases.

Set your deductible at the highest level you can genuinely afford to pay within 30 days of a loss, not the amount you hope to have someday. Homeowners in Summit County paying median premiums of $2,829.61 annually might save $400 to $700 through this adjustment, making it particularly valuable in high-cost regions.

Maintain Your Home to Protect Your Coverage

Regular maintenance directly affects your insurability and premium. Insurers increasingly deny coverage for water damage from frozen pipes if they determine you failed to maintain adequate heat during winter, effectively voiding a claim when you need it most. Inspect your roof every two years and replace it before it reaches 20 years of age, since older roofs trigger higher premiums or coverage restrictions at renewal. Keep gutters clear, trim tree branches away from your home, and address any foundation cracks or water intrusion issues before they worsen. Document your maintenance with photos and receipts-this evidence supports your claim if damage occurs and demonstrates responsible homeownership to your insurer at renewal time.

Know What Affects Your Premium Beyond Your Control

Your location, claims history, and home characteristics determine much of what you pay. Fire protection class (determined by your distance to a fire hydrant and your local fire department’s quality) influences your premium significantly, as does your insurance score, which is a credit-based rating that Utah insurers use to assess risk. Construction and repair costs continue to rise, especially in densely populated areas with limited supply, pushing premiums higher across the state. Extreme weather events are becoming more frequent and severe, increasing the risk of home damage and claims in Utah. These factors explain why Summit County residents face substantially higher premiums than those in other regions-terrain, elevation, and weather exposure create genuine cost differences that no discount can fully offset. Understanding these realities helps you set realistic expectations as you shop for coverage and plan your insurance budget.

Right Coverage Amounts for Your Utah Home

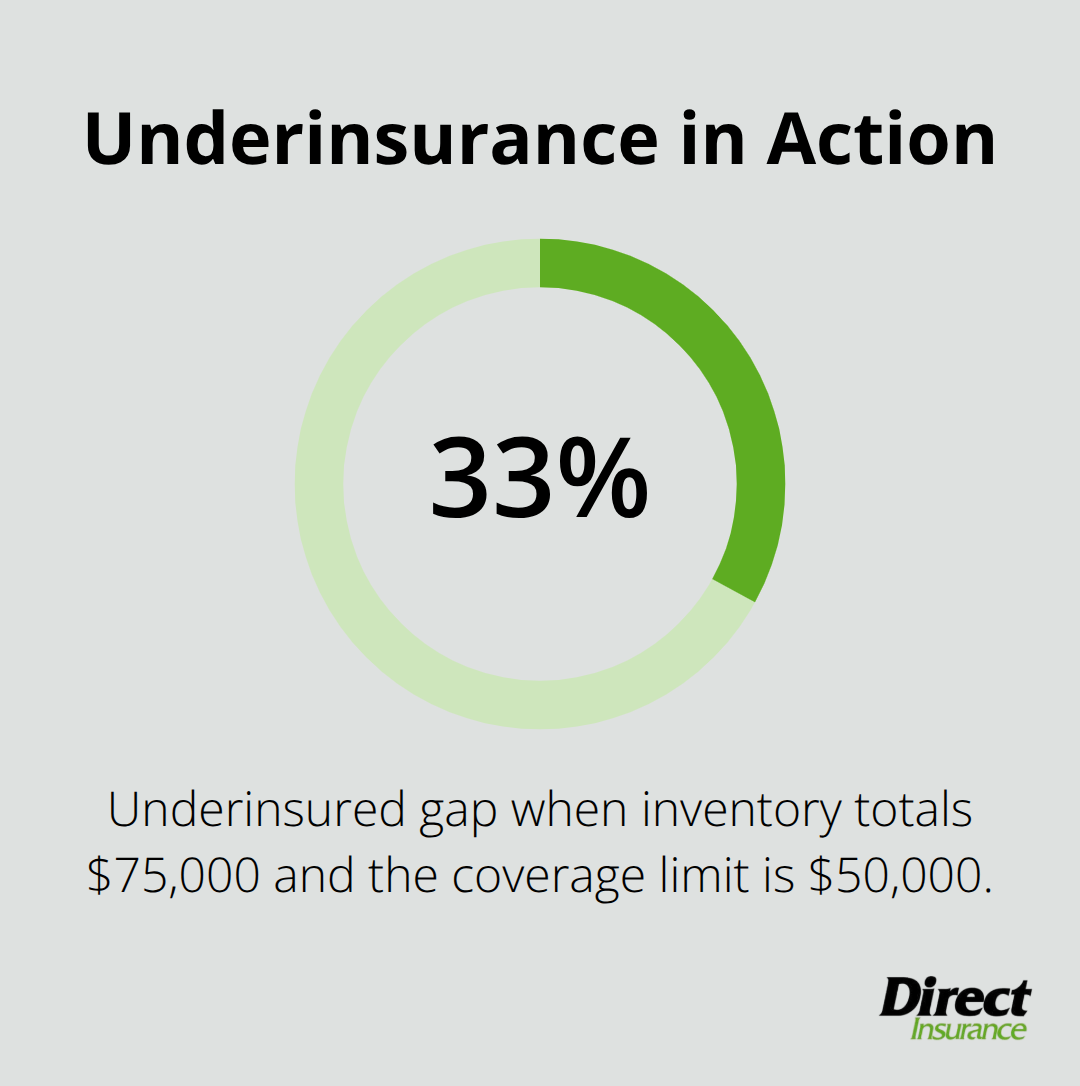
Determining the correct coverage limits requires honest assessment of what you actually own and what it costs to rebuild. Homeowners regularly underinsure their dwellings because they confuse home market value with replacement cost. A $400,000 home in Salt Lake County might require $500,000 in dwelling coverage if construction costs run $175 per square foot for a 2,000 square foot rebuild, especially as material and labor costs continue climbing across Utah. The National Association of Insurance Commissioners emphasizes that replacement cost reflects what you’ll spend to rebuild with comparable materials, excluding land value. Start with a detailed rebuild estimate from a local contractor or use online calculators that factor in Utah’s current construction costs.

Compact checklist of steps to calculate an accurate dwelling coverage limit in Utah. - homeowners insurance tips Utah

Then add 10 to 20 percent as a safety buffer since inflation consistently outpaces initial estimates. Your mortgage lender’s appraisal shows market value, not rebuild cost, so don’t use that number when setting dwelling limits.

Personal Property Coverage Must Match Your Actual Possessions

Standard personal property coverage limits typically run 50 to 70 percent of your dwelling coverage, which often leaves high-income earners significantly underinsured. If your dwelling limit is $500,000, standard coverage might provide only $250,000 to $350,000 for contents, yet you could own $400,000 in furniture, electronics, art, and clothing. Walk through your home and photograph every room, then create a spreadsheet listing items with approximate purchase prices. Electronics, appliances, and furniture depreciate rapidly, so replacement cost coverage for contents matters far more than actual cash value, particularly for newer purchases. The cost difference between ACV and replacement cost on personal property is typically 5 to 15 percent of your annual premium-a worthwhile investment when a single claim could exceed your coverage limits. Request a specific dollar amount for your contents coverage limit rather than accepting the standard percentage-based calculation, and ensure your policy states replacement cost value rather than actual cash value.

High-Value Items Demand Separate Protection

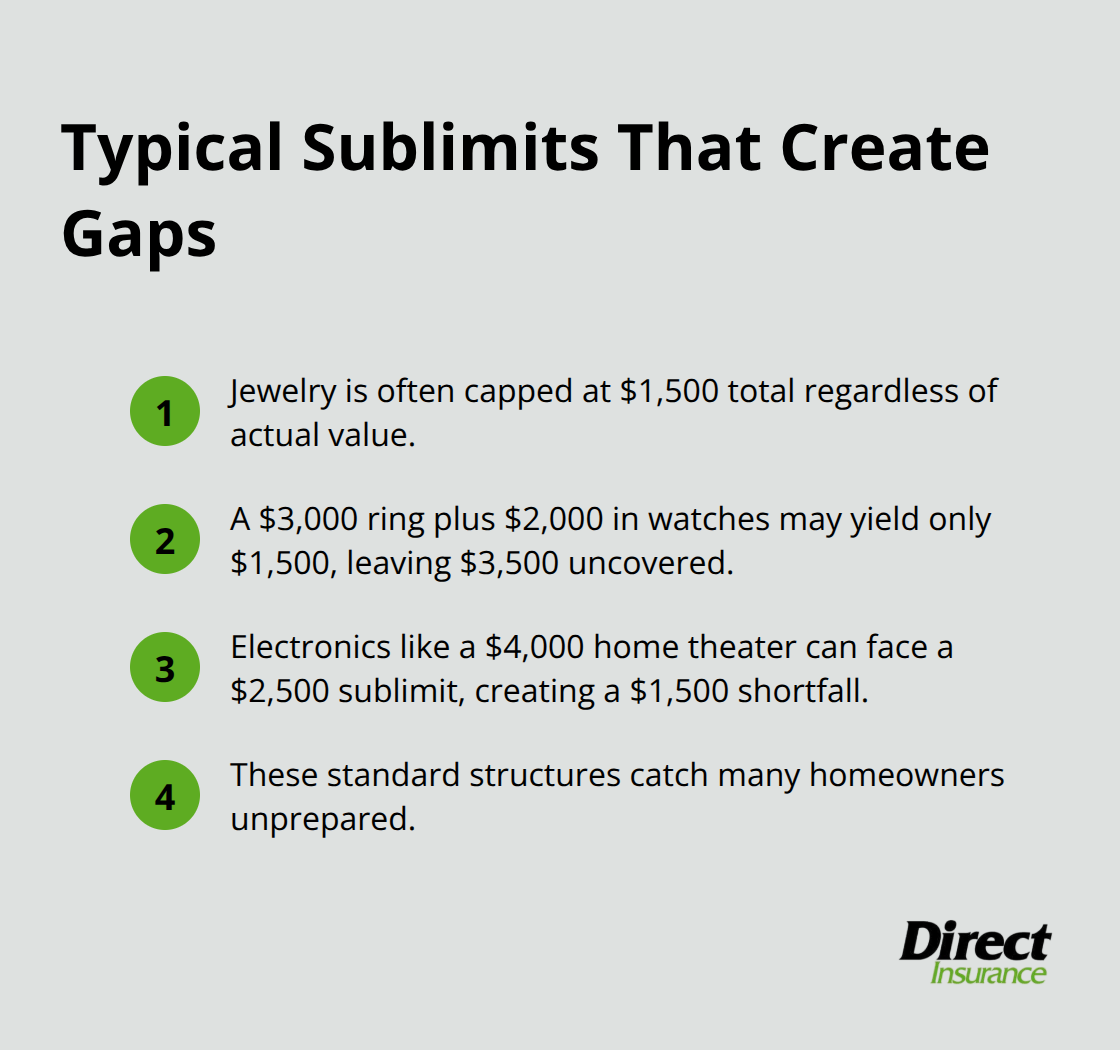
Jewelry, fine art, collectibles, and high-end electronics face strict sublimits under standard homeowners policies, meaning your standard coverage might reimburse only $1,500 to $2,500 for all jewelry even if you own a $15,000 engagement ring. Blanket jewelry coverage removes these sublimits and covers items at full replacement cost without requiring receipts for each piece, costing roughly $100 to $300 annually depending on total value. Similarly, fine art, antique collections, and high-end cameras need scheduled personal property endorsements that list specific items and their values. Document everything with photographs, professional appraisals, and purchase receipts stored outside your home (ideally in a safe deposit box or cloud storage). For items under $10,000 in total value, blanket coverage proves more practical than scheduling each piece individually, but anything exceeding that threshold warrants itemized scheduling. Ask your agent about coverage for business property kept at home, since standard homeowners policies exclude equipment used for income generation.

Final Thoughts

Balancing protection and cost requires three practical decisions: understanding what your home actually costs to rebuild, choosing coverage limits that match your real possessions, and implementing the specific discounts available to Utah homeowners. Replacement cost matters far more than market value, bundling policies saves roughly $950 annually, and raising your deductible strategically cuts premiums without leaving you vulnerable if you maintain adequate emergency savings. The homeowners insurance tips Utah homeowners need most involve honest assessment rather than guesswork-photograph your belongings, get a contractor’s rebuild estimate, and request specific dollar amounts instead of accepting percentage-based calculations.

Your next step is straightforward: gather your current policy documents and compare them against what you’ve learned here. Check whether you have replacement cost or actual cash value coverage, verify your dwelling limit against current construction costs in your county, and identify any protection gaps for high-value items or winter-related risks. Request quotes from at least three insurers and compare the bundled rates for both auto and homeowners policies, not just the home premium alone.

If your policy is more than two years old, the rates have almost certainly changed-Utah counties saw median premium increases ranging from 51 percent in Salt Lake County to 96.8 percent in Summit County between 2020 and 2023, so shopping around isn’t optional anymore. Start your review with Direct Insurance Services to find coverage that actually fits your needs and budget, or call to discuss your current policy with someone who knows Utah homeowners insurance inside and out. Our team understands Utah’s specific risks, from flash flooding in desert regions to ice dam damage in mountain communities, and we work with top-rated carriers to help you navigate these decisions without pressure.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
Getting auto insurance quotes online puts the power in your hands. You can compare coverage options and prices from multiple insurers without stepping foot in an office.

At Direct Insurance Services, we’ve seen firsthand how this approach saves customers both time and money. The key is knowing what to look for when you’re reviewing those quotes.

Why Online Quotes Beat the Traditional Route

Speed and Convenience Transform Your Shopping Experience

Real-time quotes from multiple insurers let you compare rates side-by-side in minutes instead of days. You control the pace, review options on your schedule, and spot savings opportunities that would never surface in a single conversation with one agent. Individual rates vary dramatically-sometimes by hundreds of dollars per month for identical coverage.

Price Variation Demands Comparison

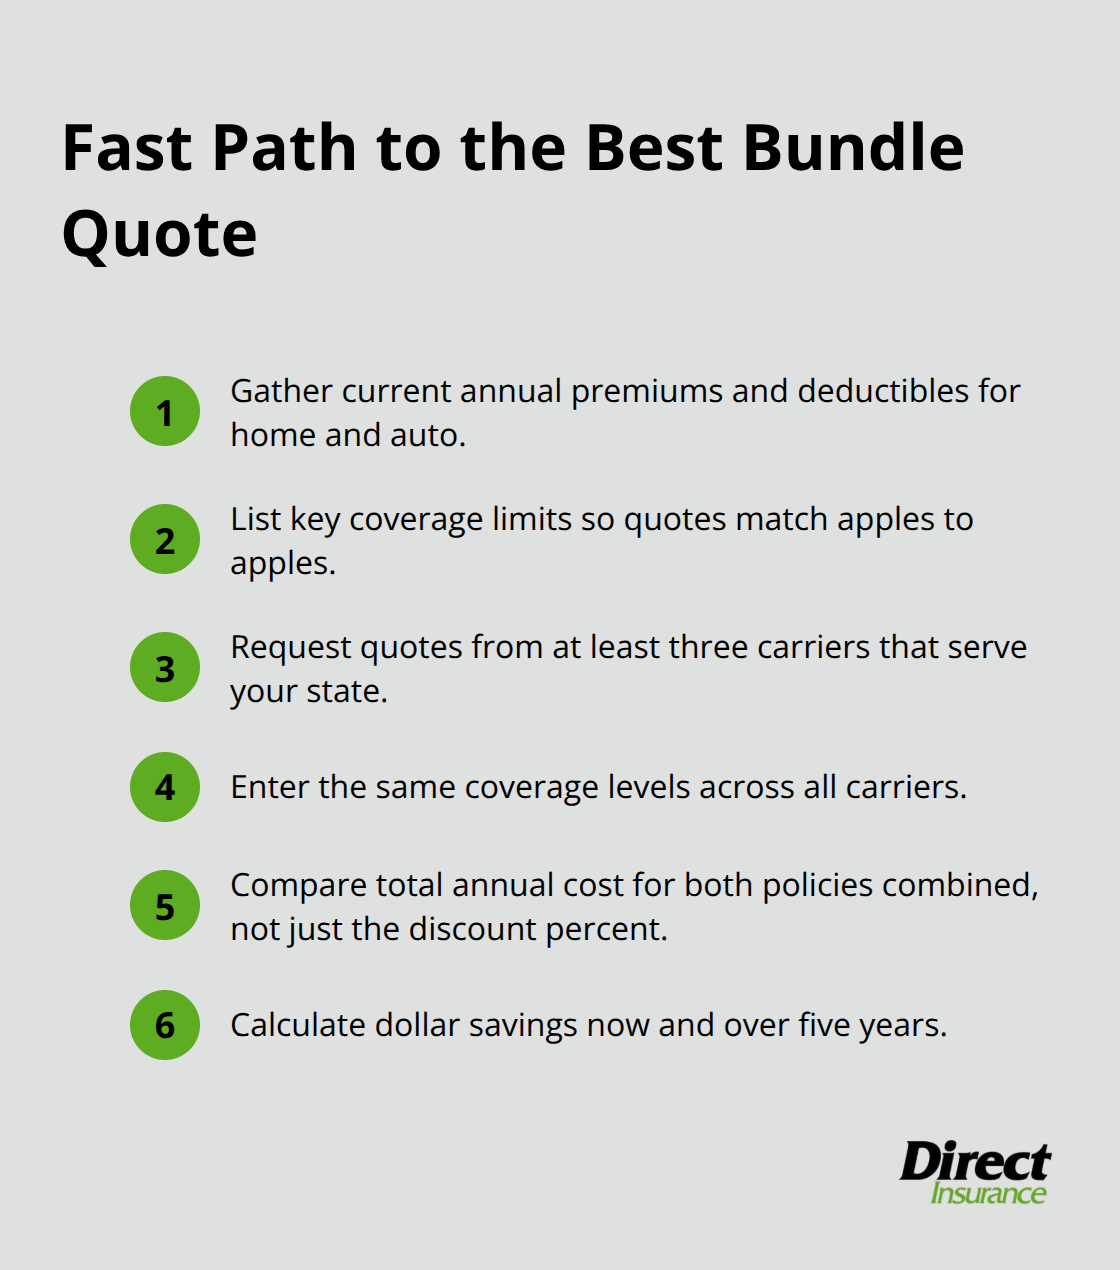
A driver in one ZIP code might pay significantly different rates with different insurers for the same profile. This variation is exactly why comparing multiple quotes matters. When you gather quotes online using the same coverage levels across all insurers, you eliminate the guesswork. Input your vehicle details, driving history, and desired coverage limits once, then compare apples-to-apples pricing. This approach prevents the common trap of selecting the cheapest option without understanding what you’re actually getting.

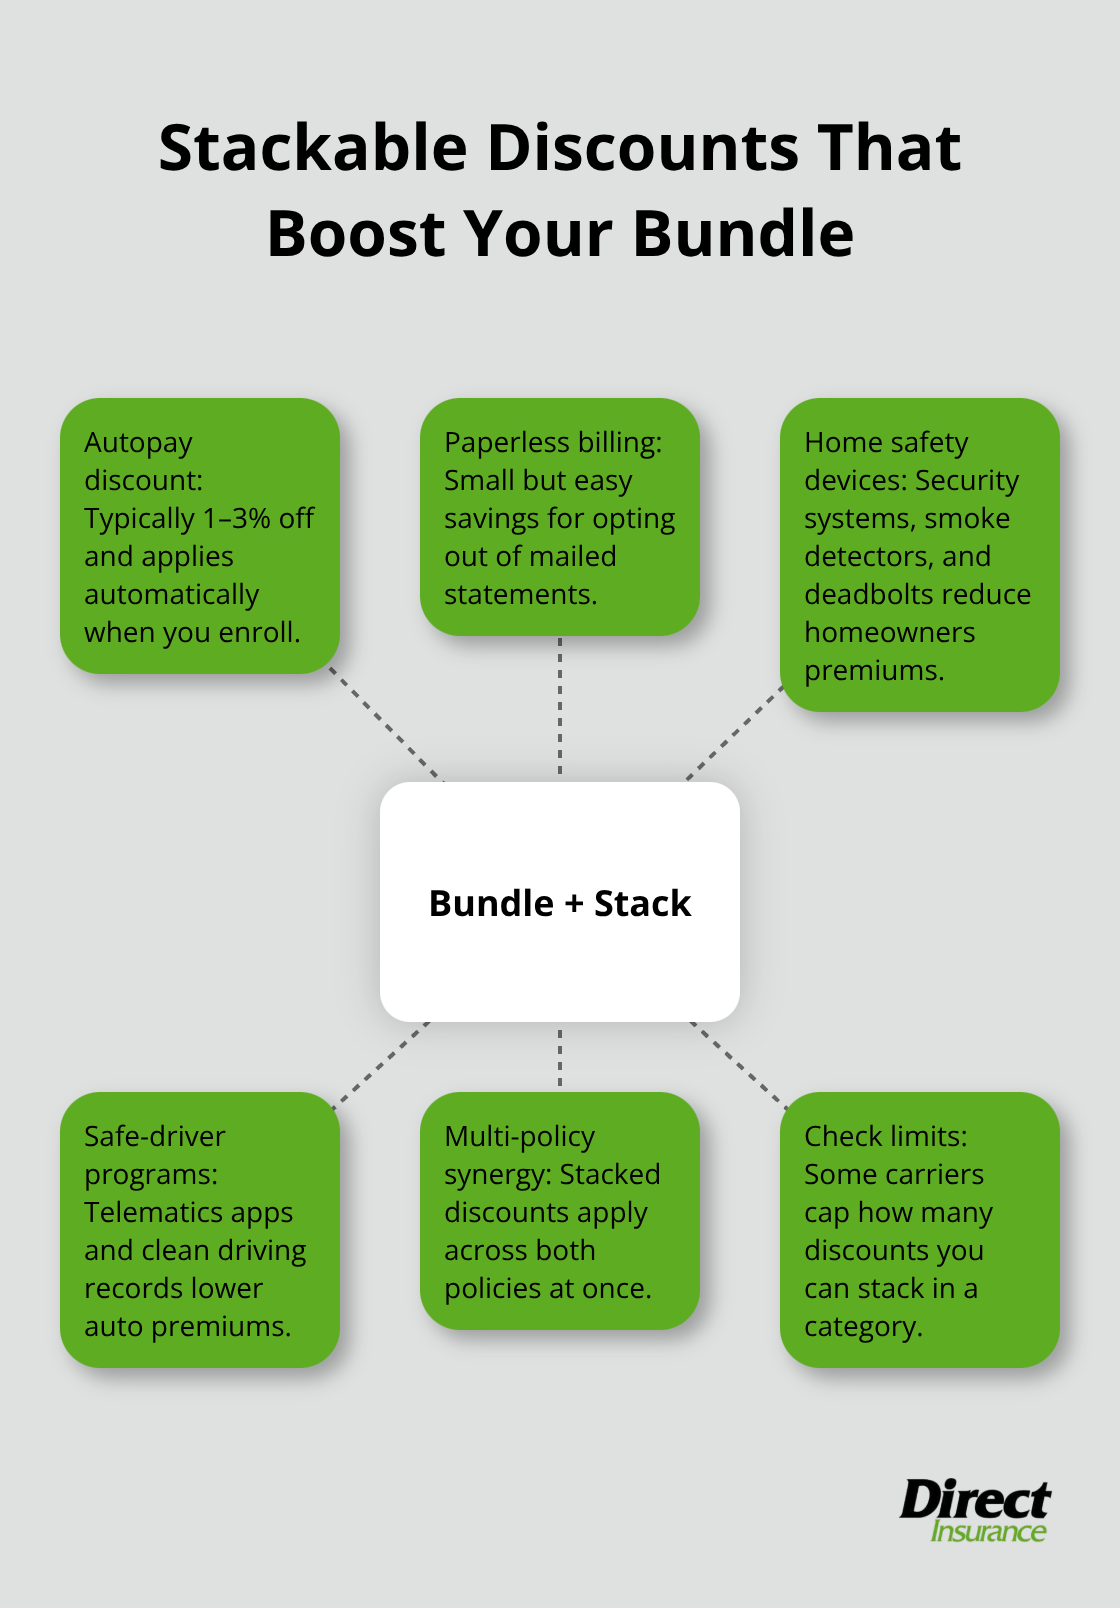
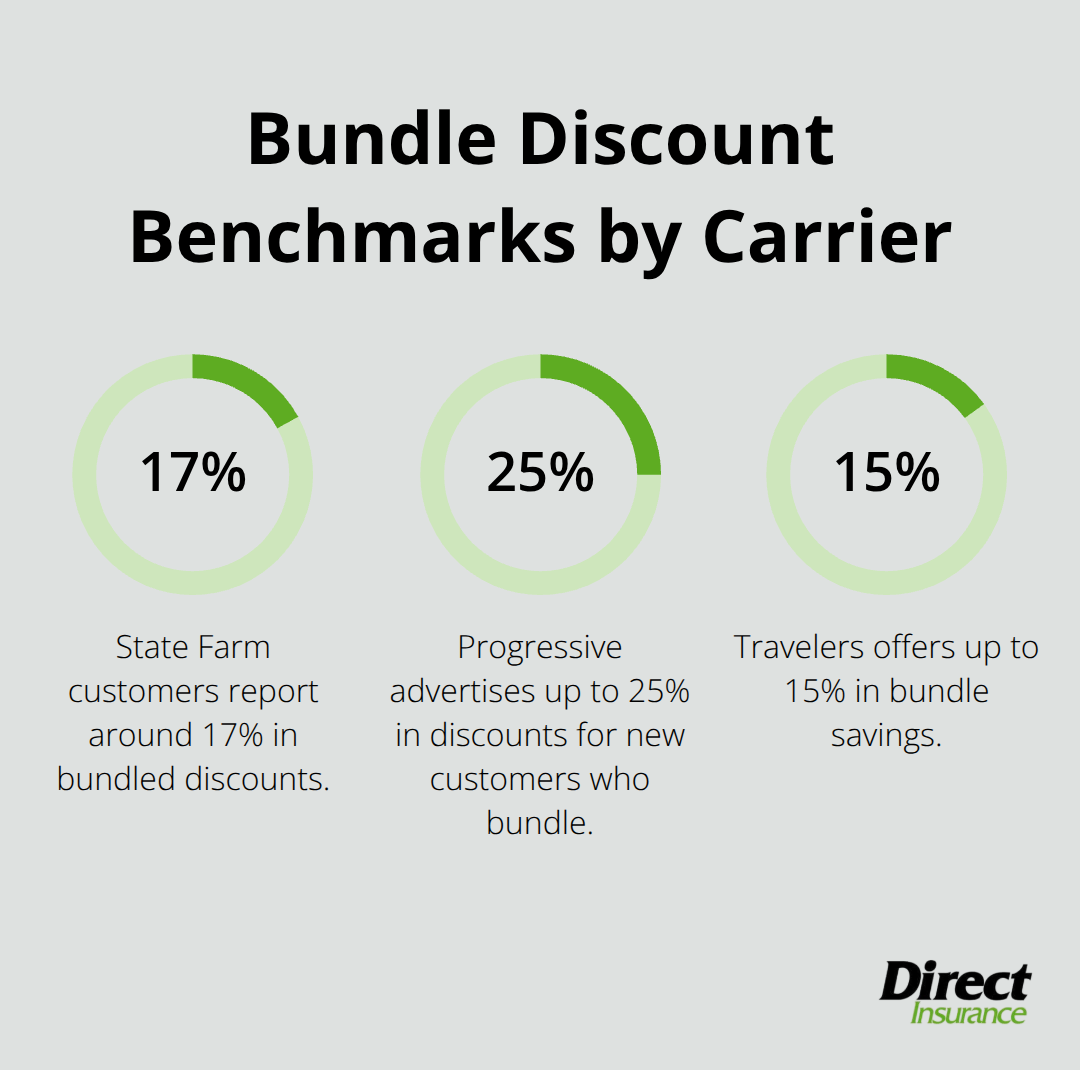
Drivers who compare quotes from at least three insurers save substantially compared to those who accept the first quote. The real power emerges when you recognize bundling opportunities. Bundling auto with home or renters insurance can provide meaningful savings according to industry data. State Farm, Allstate, and Nationwide lead the bundling market in 2026, but you won’t know your best option without comparing quotes across multiple carriers.

Discounts Hide in Plain Sight

Online quote tools expose discounts you might otherwise miss-auto-pay discounts, good driver discounts, multi-vehicle discounts, and safety feature discounts vary significantly between insurers. Some carriers offer discounts for paperless billing while others offer nothing. The difference between your highest and lowest quote often comes down to which insurer values your specific profile most favorably. Once you’ve identified your top options based on price and coverage, the next step involves understanding what information you actually need to provide for accurate quotes.

What Information You Need for Accurate Quotes

Accurate quotes require you to provide the right information upfront. Start with basics: your driver’s license, current address, birth date, and the vehicle identification number for each car you’re insuring. You’ll also need the year, make, model, and trim of your vehicle since repair costs vary dramatically between models. A 2024 Honda Civic costs significantly less to repair than a 2024 BMW 3 Series, which directly affects your premium.

Compact checklist of the key information you need to enter to receive accurate auto insurance quotes online.

Vehicle Details Shape Your Rate

Annual mileage matters significantly-drivers logging 15,001+ miles annually pay roughly $152 per month for full coverage compared to $146 for those driving 10,001–15,000 miles. Your driving history, including any accidents, tickets, or DUIs from the past three to five years, influences every quote you receive. Insurance companies also request information about your prior coverage and claims history, so have that documentation ready.

Credit score impacts pricing in most states, though California, Hawaii, and Massachusetts prohibit using it. Ownership status-whether you own, lease, or finance the vehicle-matters because leased and financed cars typically require full coverage with lower deductibles, which increases costs.

Match Coverage Levels Across All Quotes

The biggest mistake drivers make is comparing quotes with different coverage levels, making price differences meaningless. Full coverage with a $1,000 deductible averages around $129 monthly, but liability-only coverage drops to roughly $98 monthly. These aren’t comparable quotes.

Start by deciding what coverage you actually need. If your vehicle is worth more than $4,000, full coverage makes financial sense. If you’re financing or leasing, your lender requires it anyway. Once you’ve decided on coverage, input the exact same liability limits, deductible amounts, and optional coverages into every quote tool. Don’t mix a $500 deductible from one insurer with a $1,000 deductible from another. This consistency reveals which insurers genuinely offer better rates for your profile versus which ones simply quoted different coverage.

Track the quotes in a simple spreadsheet listing the insurer name, monthly premium, coverage limits, and deductible. This visual comparison exposes rate variations that would be invisible otherwise. Some insurers price aggressively for drivers in specific ZIP codes or with particular profiles while others don’t, so the cheapest option varies by person.

Evaluate Service Quality Beyond Price

Choosing based purely on price ignores what happens when you actually need your insurer. The Better Business Bureau rating and J.D. Power customer satisfaction scores reveal how different carriers treat claims. State Farm and GEICO consistently rank highest for claims satisfaction, but regional carriers sometimes outperform national companies in specific states.

Check recent customer reviews on Trustpilot and the BBB website-look specifically for comments about claims processing speed and how fairly the company handled disputes. An insurer that processes claims in three days versus three weeks creates vastly different experiences during stressful situations. Some companies offer 24/7 claims reporting while others have limited hours.

These service differences justify paying slightly more for a carrier with proven reliability. After identifying your top three quotes based on price and coverage match, spend fifteen minutes researching how each company actually performs when customers file claims. This final step prevents selecting an insurer that will frustrate you when you need them most. Once you’ve narrowed your options, the next phase involves understanding which discounts actually apply to your specific situation.

Common Mistakes When Comparing Online Quotes

The moment you select the lowest-priced quote without verifying coverage matches, you’ve already made a costly mistake. Drivers compare an $89 monthly quote against a $156 monthly quote and declare victory without realizing one includes full coverage with a $500 deductible while the other is liability-only with a $1,000 deductible. These aren’t comparable prices. A $67 monthly difference disappears instantly when you file a claim and discover your cheaper option leaves you exposed. The Zebra data shows that full coverage with a $1,000 deductible averages $129 monthly, but liability-only drops to $98 monthly-a 26% difference driven entirely by coverage, not by which insurer offers better rates for your profile.

Percentage chart showing the average 26% price difference between liability-only and full coverage with a $1,000 deductible.

Before celebrating any savings, verify that every quote you’re reviewing includes identical liability limits, identical deductibles, and identical optional coverages like collision and comprehensive. This single step prevents selecting an insurer based on an incomplete picture.

Coverage Mismatches Hide True Costs

Comparing quotes with different coverage levels produces meaningless price differences. You must input the exact same liability limits, deductible amounts, and optional coverages into every quote tool. Don’t mix a $500 deductible from one insurer with a $1,000 deductible from another. This consistency reveals which insurers genuinely offer better rates for your profile versus which ones simply quoted different coverage. Track the quotes in a simple spreadsheet listing the insurer name, monthly premium, coverage limits, and deductible. This visual comparison exposes rate variations that would be invisible otherwise. Some insurers price aggressively for drivers in specific ZIP codes or with particular profiles while others don’t, so the cheapest option varies by person.

Bundling Discounts Multiply Your Savings

Ignoring bundling opportunities costs drivers thousands annually. State Farm, Allstate, and Nationwide lead the bundling market in 2026 because they offer substantial savings when you combine auto with homeowners or renters insurance.

Percentage chart showing that 61% of American homeowners bundle home and auto insurance while 36% do not. - auto insurance quotes online

61% of American homeowners bundle their home and auto insurance policies with the same carrier, while 36% do not. Yet most drivers comparing online quotes focus solely on their auto insurance cost and never check whether that insurer offers better bundling rates than competitors. You might find a slightly cheaper auto-only quote from one carrier, but once you factor in bundling your home and auto policies together, a different insurer becomes substantially cheaper overall. Pull quotes for both auto and home insurance from your top three candidates before deciding. A $5 monthly difference on auto insurance becomes irrelevant when bundling saves you $40 monthly across both policies. Additionally, some insurers offer bundling discounts that stack with other discounts like auto-pay or good driver status, multiplying your savings further.

Service Quality Matters More Than Price Alone

Choosing based purely on price ignores what happens when you actually need your insurer. The Better Business Bureau rating and J.D. Power customer satisfaction scores reveal how different carriers treat claims. State Farm and GEICO consistently rank highest for claims satisfaction, but regional carriers sometimes outperform national companies in specific states. Check recent customer reviews on Trustpilot and the BBB website-look specifically for comments about claims processing speed and how fairly the company handled disputes. An insurer that processes claims in three days versus three weeks creates vastly different experiences during stressful situations. Some companies offer 24/7 claims reporting while others have limited hours. These service differences justify paying slightly more for a carrier with proven reliability. After identifying your top three quotes based on price and coverage match, spend fifteen minutes researching how each company actually performs when customers file claims. This final step prevents selecting an insurer that will frustrate you when you need them most.

Life Changes Require Fresh Quote Comparisons

Your information changes, and outdated details produce inaccurate quotes that lead to wrong decisions. Moving to a new address changes your rate significantly because location-based risk factors and state regulations vary dramatically. A relocation from a low-crime suburban ZIP code to an urban center can increase premiums substantially. Purchasing a vehicle, adding a teenage driver, or getting married all trigger rate recalculations that your old quotes don’t reflect. Drivers who compare quotes once and then delay shopping again for three years miss opportunities to switch when rates drop or lock in savings when their profile improves. If you received a ticket or an accident-free milestone passes, your rate should improve, but only if you’re comparing fresh quotes. We recommend gathering new quotes every six months because market rates shift constantly even when your personal situation remains stable. Some insurers price aggressively for your current profile while others don’t, and that competitive landscape changes throughout the year. Your previous research becomes outdated quickly, so treating quote comparisons as a one-time event rather than an ongoing process costs you money over time.

Final Thoughts

Comparing auto insurance quotes online puts you in control of one of your biggest household expenses. You’ve learned how to gather accurate information, match coverage levels across insurers, and evaluate service quality beyond price alone. The process takes minutes, but the savings compound over years.

Your next step is straightforward: gather quotes from at least three insurers using identical coverage levels, track them in a spreadsheet, and research how each company handles claims before deciding. Don’t settle for the lowest price without verifying coverage matches, and don’t ignore bundling opportunities that could save you hundreds annually. Market rates shift constantly, and your personal circumstances change too, so revisit quotes every six months to stay aligned with the best available rates for your profile.

At Direct Insurance Services, our team works with top-rated carriers to help you find coverage that fits both your needs and budget. We’re an independent agency serving Utah, which means we’re not tied to any single insurer and can help you compare options without pressure. Visit Direct Insurance Services to discuss your coverage needs with someone who understands your local market and can answer questions that online quote tools leave unanswered.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
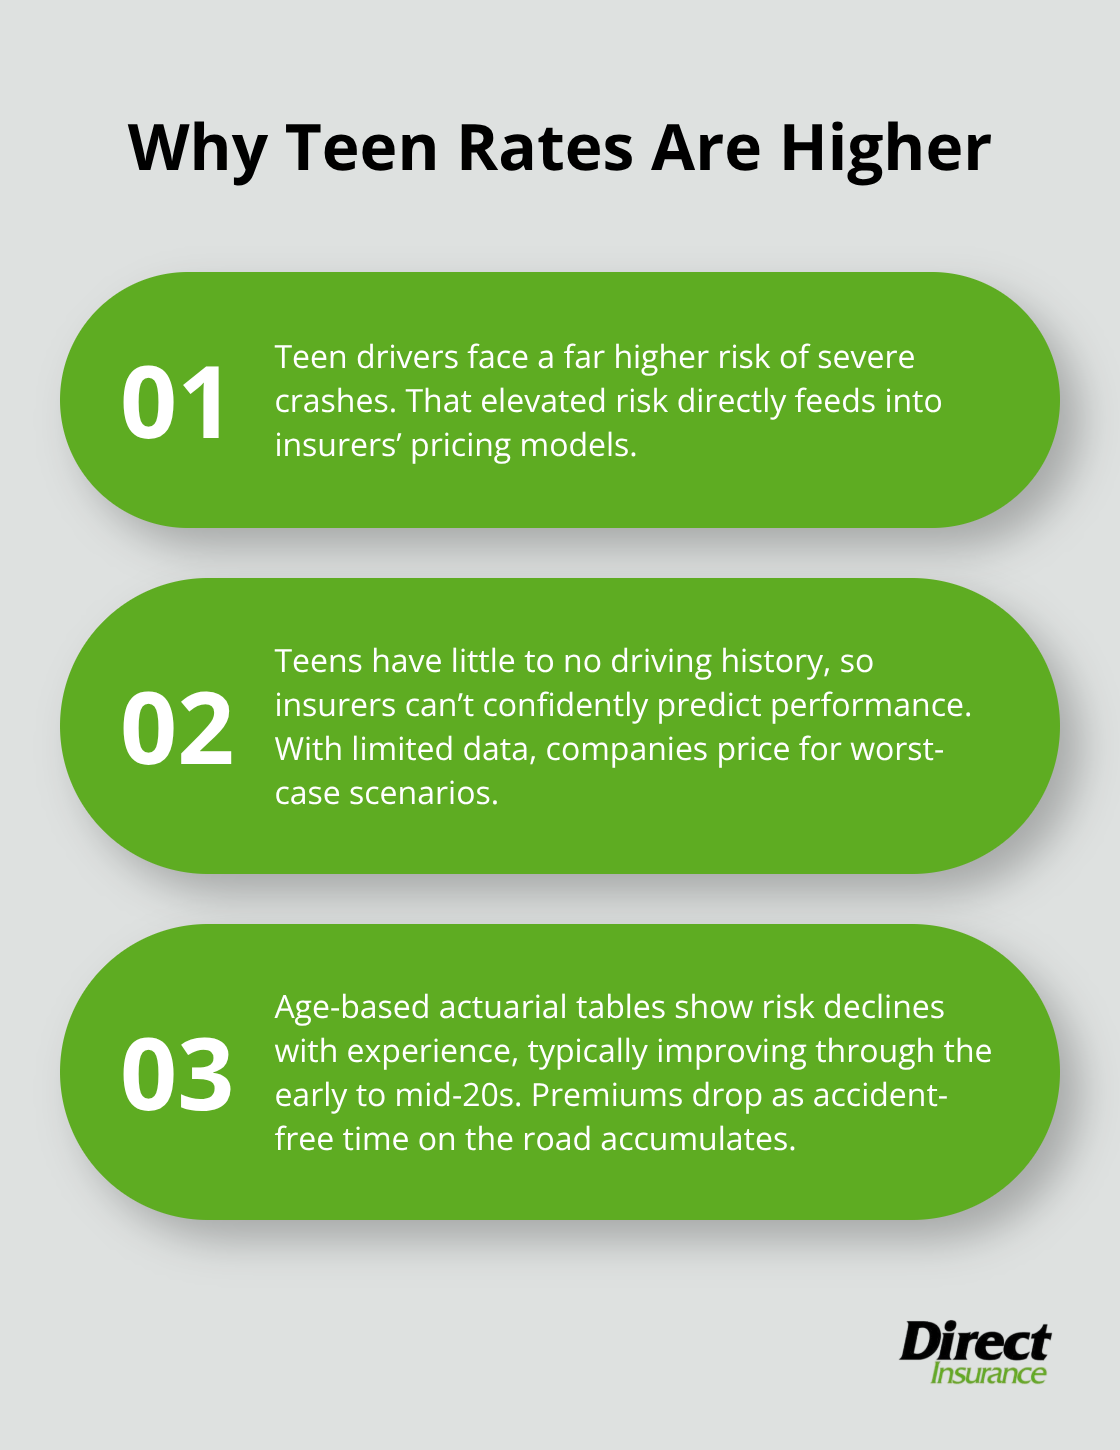
One accident on a job site can cost you thousands in medical bills, legal fees, and lost time. Contractor liability coverage is the safety net that protects your business when things go wrong.

At Direct Insurance Services, we’ve seen firsthand how a single claim can derail a contractor’s finances. That’s why understanding what this coverage actually does-and what gaps might exist in your current policy-matters so much.

What Contractor Liability Coverage Actually Covers

Contractor liability coverage protects against accidents, property damage, and lawsuits that arise from your work. When a client, passerby, or property owner files a claim for bodily injury or property damage caused by your operations, this coverage handles medical expenses, repair costs, and legal defense fees. The Hartford reports that a typical $1,000,000 general liability policy costs around $69 per month, though premiums vary based on your trade, location, claims history, and project scope. This isn’t optional paperwork-it’s the foundation of a functional contracting business. Many clients and contracts require proof of liability insurance before work begins, and some jurisdictions won’t issue permits without it. Personal or home insurance explicitly excludes claims that arise from contracting work, which means operating without a business-specific liability policy leaves you completely exposed.

What Your Coverage Actually Pays For

Contractor liability covers bodily injury (medical bills from on-site accidents), property damage (damage to a client’s structure or belongings during your work), legal defense costs (attorney fees and court expenses), and completed operations (claims that surface after a project finishes). Advertising injury and defamation claims also fall under coverage, protecting you if a client alleges copyright issues in your marketing or slander related to your business. The coverage limits you choose matter significantly-a $1,000,000 limit is standard, but larger commercial projects often require $2,000,000 or higher. Your deductible also affects your premium; choosing a $2,500 deductible instead of $1,000 can lower your annual cost materially. Common exclusions include employee injuries (handled by workers’ compensation), damage to your own tools and equipment (covered separately through inland marine or tools floaters), and professional mistakes on design-build projects (addressed by professional liability insurance). Read your policy’s exclusions carefully because coverage gaps can appear where you least expect them, especially on specialized projects involving mold, environmental discharge, or value engineering decisions.

Why Your Personal Business Insurance Falls Short

Standard business policies and home-based business riders don’t cover liability from contracting activities. A homeowners policy specifically excludes work-related claims, and a basic commercial general liability policy from a non-specialist carrier often includes restrictive language that denies coverage on complex claims. Contractors face unique on-the-job risks-fall hazards, equipment operation, property access, and third-party interactions-that generic policies don’t address. Your trade also matters; plumbers, electricians, and roofers face different risk profiles than handymen, and insurers price accordingly. Additionally, clients increasingly require additional insured endorsements, which add your client to your policy as a covered party on that specific project. A standard commercial policy may not allow this endorsement, or the insurer may charge extra. Subcontractors complicate coverage further; if a subcontractor causes damage, your policy may not cover their actions unless they’re specifically added as additional insureds or carry their own coverage. Many contractors discover gaps only after a claim is filed, which is far too late.

What Happens When Coverage Gaps Emerge

The real danger appears when you assume your policy covers something it doesn’t. A mold remediation case illustrates this perfectly: a subcontractor lacked pollution coverage, and recovery stopped at $120,000 despite remediation costs exceeding $700,000 plus $50,000 in legal expenses. On another design-build apartment project, initial mold estimates of $180,000 grew to over $400,000, with the insurer paying $400,000 and the policyholder absorbing a $50,000 self-insured retention plus $20,000 in legal fees. These aren’t rare scenarios-they’re warnings about what happens when contractors operate without comprehensive protection. Your policy language governs what actually gets paid, not your assumptions about coverage. Professional liability insurance, pollution liability coverage, and tools floaters each address specific gaps that standard contractor liability leaves open. Understanding these distinctions now prevents financial devastation later. The next section walks through real claims that expose these gaps and shows how proper coverage would have changed the outcome.

How Your Coverage Protects You When Claims Happen

Contractor liability coverage operates in three distinct ways that matter to your bottom line. It pays medical expenses and lost wages when someone gets injured on your job site-no negotiation, no waiting for your cash reserves to absorb the cost. It covers property damage you cause during your work, plus legal defense fees that accumulate even when you win a case. It protects you after a project finishes, which is critical because defects and damage claims often surface months or years later.

Infographic showing the three core protections of contractor liability coverage: medical expenses, property damage with legal defense, and completed operations.

The Hartford reports that a typical $1,000,000 general liability policy costs around $69 per month, but that investment prevents a single serious injury claim from bankrupting your operation. Most contractors underestimate how quickly legal fees accumulate; even a straightforward bodily injury case can cost $15,000 to $50,000 in attorney time before settlement. Your coverage pays those fees regardless of whether you’re found liable, which means your business stays operational while the claim resolves.

Bodily Injury Claims Stop Draining Your Business Account

When a client, employee, or third party gets hurt on your job site, the medical bills arrive first and the lawsuit follows. Contractor liability coverage pays emergency room visits, ongoing medical treatment, physical therapy, and wage replacement for time the injured person cannot work. If the injury is permanent, coverage includes settlement amounts for loss of earning capacity and pain and suffering. The real protection here is that your business does not hemorrhage cash while the claim processes. A fall from scaffolding or an electrical accident can generate $100,000 to $500,000 in medical costs plus legal expenses, and without coverage you remain liable for the full amount. Your policy limits determine the maximum your insurer pays-a $1,000,000 limit covers most residential and light commercial projects, but larger commercial work often requires $2,000,000 or higher. Many contractors assume their clients’ insurance covers injuries that happen on the job site, which is a dangerous misconception. Your coverage is primary, meaning it pays first, and your client’s insurance only covers additional exposure beyond your limits. This distinction matters enormously when you negotiate contracts and understand who bears financial responsibility.

Property Damage Coverage Protects Your Clients and Your Reputation

Contractor liability covers damage you cause to a client’s property during your work-a roof leak from improper flashing installation, a wall damaged during interior demolition, or landscape damage from equipment operation. The coverage also includes legal defense costs, which means your insurer pays your attorney to defend you even if the claim turns out to be frivolous. This is critical because defense costs can exceed the actual settlement amount. A hotel roof leak case that settled for around $610,000 shows why proper coverage matters; the policyholder paid approximately $340,000 out of pocket plus $145,000 in legal expenses, which demonstrates how self-insured retention amounts and deductibles compound quickly. Your deductible choice directly affects your premium-a $2,500 deductible typically costs 20-30% less annually than a $1,000 deductible, but you need to carry enough cash reserves to cover that deductible if a claim happens. Many contractors choose higher deductibles to reduce premiums, then face a shock when they cannot actually pay the deductible when a claim occurs.

Chart showing that choosing a $2,500 deductible instead of $1,000 can reduce annual premiums by 20% to 30%. - contractor liability coverage

Completed Operations Coverage Extends Protection Beyond Project Completion

The coverage also handles completed operations, which means claims that surface after you finish a project and leave the job site remain protected. Defects discovered three months or six months after completion often trigger disputes about whether your work caused the problem, and your insurer pays for investigation and defense. This protection is essential on any project worth more than $50,000. Mold remediation cases illustrate why this matters-initial estimates of $180,000 grew to over $400,000 on a design-build apartment project, with the insurer paying $400,000 and the policyholder absorbing a $50,000 self-insured retention plus $20,000 in legal fees. Without completed operations coverage, you would have faced that entire bill yourself months after the project ended. Your policy language determines what actually gets paid, not your assumptions about coverage. Understanding these distinctions now prevents financial devastation later, and the next section walks through real claims that expose coverage gaps and shows how proper protection would have changed the outcome.

Claims That Expose Why Coverage Gaps Cost Thousands

Real Claims Show What Happens Without Proper Coverage

A subcontractor handling mold remediation lacked pollution liability coverage, and when the claim settled, recovery capped at $120,000 despite remediation costs exceeding $700,000 plus $50,000 in legal expenses. That contractor absorbed nearly $630,000 in uninsured losses because one coverage type was missing from their policy. On a design-build apartment project, initial mold estimates started at $180,000 but ballooned to over $400,000 once remediation began. The insurer paid $400,000, but the policyholder still paid a $50,000 self-insured retention and $20,000 in legal fees out of pocket. These aren’t hypothetical scenarios-they’re what happens when contractors assume their general liability policy covers specialized risks like environmental discharge or mold remediation.

Property Damage Claims Escalate Faster Than Most Contractors Expect

A hotel roof leak case that settled for approximately $610,000 illustrates property damage exposure; the policyholder paid roughly $340,000 out of pocket plus $145,000 in legal expenses, meaning the final cost to the contractor nearly matched the settlement amount. Contractors who fail to properly secure structures during severe weather face massive repair bills when water intrusion causes secondary damage like mold. On a value engineering HVAC project, initial repair estimates reached $1,000,000, but the claim settled for $450,000. The general contractor still paid $150,000 and faced a $50,000 deductible, plus the reputational damage of a major defect claim. These outcomes occur because contractors operate without professional liability insurance, pollution coverage, or properly structured additional insured endorsements on client projects.

Your Policy Language Determines What Gets Paid

Your policy language determines what gets paid, not your assumptions about coverage. A chlorine discharge incident settled for more than $50,000 in environmental fines alone, underscoring how quickly environmental compliance failures compound into liability exposure. The protection you need extends far beyond standard contractor liability into specialized areas like professional liability for design decisions, pollution liability for environmental risks, and inland marine coverage for tools and equipment in transit. The common thread across all these real claims is that contractors believed they were protected until the bill arrived and their insurer denied the claim because the specific risk fell outside their policy language.

Deductible Choices Create Hidden Financial Exposure

Your deductible choice also matters significantly-choosing a $2,500 deductible instead of $1,000 reduces your annual premium 20-30%, but you must maintain cash reserves to actually pay that deductible when a claim happens. Many contractors face a second crisis when they cannot cover their own deductible after a major claim occurs. The gap between what you think your policy covers and what it actually covers often appears only when you need it most. Contractors who operate without professional liability insurance, pollution coverage, or properly structured additional insured endorsements leave themselves exposed to six-figure losses that a standard general liability policy won’t cover.

Final Thoughts

Contractor liability coverage separates contractors who survive claims from those who face financial ruin. A single incident can cost tens of thousands or hundreds of thousands of dollars, and your standard business insurance won’t cover it. Your policy language determines what actually gets paid, your deductible choice affects both your premium and your cash flow, and coverage gaps in areas like pollution liability or professional liability can expose you to losses your general liability policy explicitly excludes.

Read your policy exclusions carefully and verify that your coverage limits match the projects you bid on-a $1,000,000 limit works for most residential and light commercial work, but larger commercial projects often require $2,000,000 or higher. Confirm that your policy includes completed operations coverage (which protects you when defects surface months after a project finishes) and check whether you need additional insured endorsements for your clients. Verify that your subcontractors carry their own coverage or understand whether they need to be added to your policy.

Checklist of actions for contractors: review exclusions, match limits, ensure completed operations, add additional insured endorsements, and verify subcontractor coverage.

At Direct Insurance Services, we help contractors navigate these complexities by working with top-rated carriers to find contractor liability coverage that actually fits your business and budget. Our team reviews your current policies, identifies gaps, and explains what your coverage pays for-not what you assume it pays for. Contact Direct Insurance Services today to evaluate your coverage needs and get a quote that protects both your projects and your clients.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
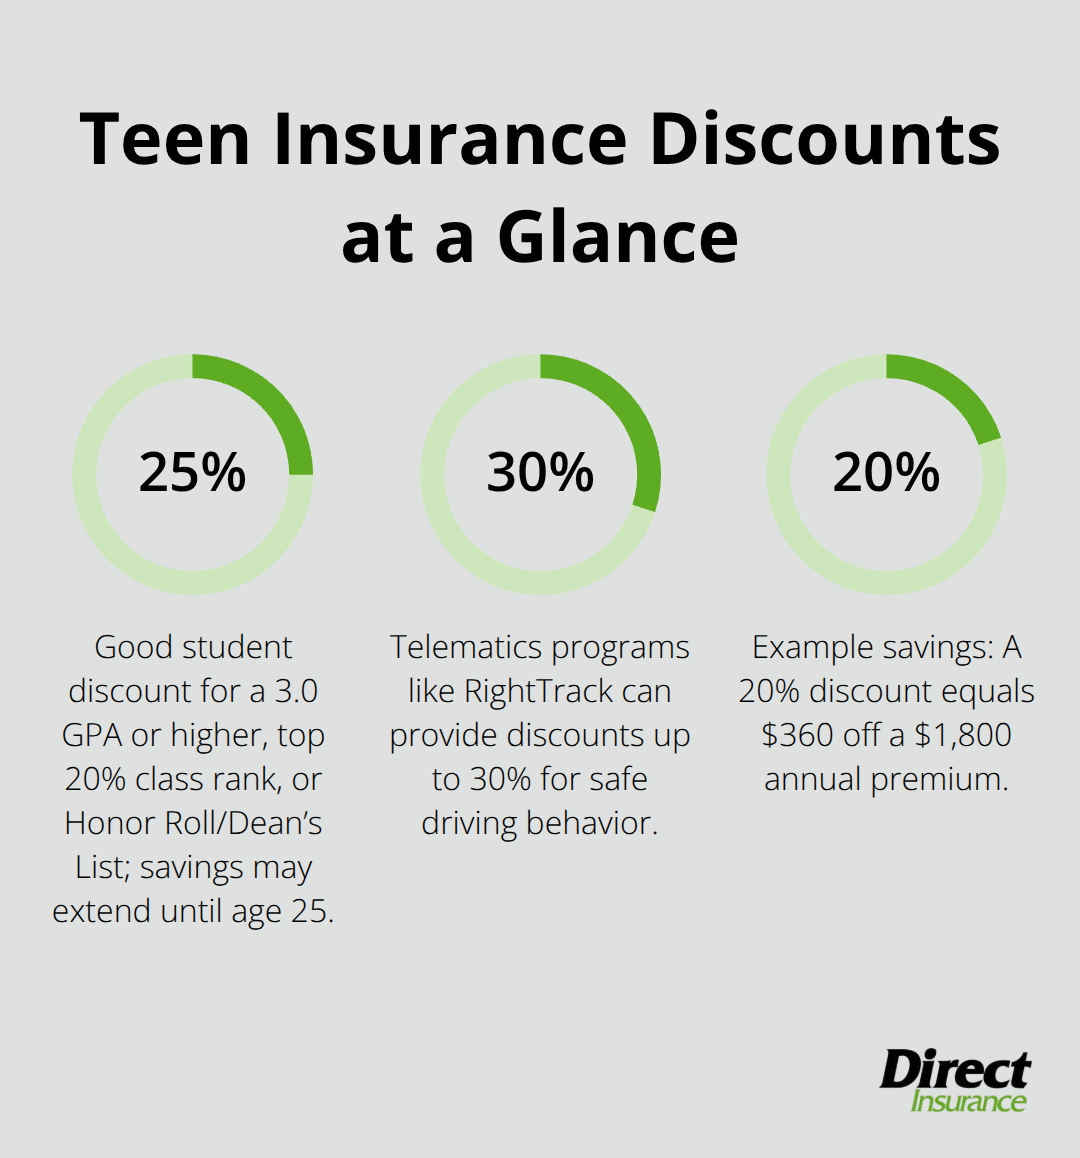
Your home contains thousands of dollars worth of belongings-furniture, electronics, clothing, and personal items that would be expensive to replace if damaged or stolen. Most homeowners assume their standard homeowners insurance covers everything, but the reality is far different.

At Direct Insurance Services, we’ve seen countless claims denied because household contents coverage had gaps or limits that didn’t match what people actually owned. This guide shows you exactly what’s covered, where the vulnerabilities are, and how to protect your belongings properly.

What Household Contents Coverage Actually Protects

Household contents coverage pays to replace or repair your belongings if fire, theft, smoke, vandalism, wind, or certain water damage affects them. According to the Insurance Information Institute, this protection applies to items inside your home and often extends to belongings you take with you for short periods, like clothes on a trip or equipment at a temporary location. The catch is that most homeowners drastically underestimate what their contents coverage includes and excludes.

Standard Coverage and Hidden Sublimits

Standard policies impose sublimits on high-value items like jewelry and electronics, meaning you won’t receive full replacement cost for these belongings even if they’re damaged. Furniture, appliances, clothing, kitchen items, and general household goods typically fall under standard coverage, but the details matter significantly. A typical home contains $50,000 to $100,000 worth of belongings, yet many people carry contents limits of just $30,000 or $40,000 without realizing the shortfall until a loss occurs.

Actual Cash Value Versus Replacement Cost Changes Everything

This is where most homeowners get blindsided. Actual Cash Value (ACV) pays you the depreciated value of an item at the time of loss, meaning a five-year-old television worth $1,500 new might be valued at $600 after depreciation. Replacement Cost Coverage reimburses you at today’s prices for a new item of similar kind and quality, so you’d receive what it actually costs to replace that television now.

If your policy includes Replacement Cost Coverage, you receive the ACV amount initially, then after you replace the item and provide receipts, the insurer covers the difference up to full replacement cost. This distinction matters enormously-a homeowner with ACV coverage on a fire loss might receive $15,000 for damaged belongings, while the same loss under Replacement Cost Coverage could pay $22,000 or more.

Comparison of Actual Cash Value and Replacement Cost coverage with payout steps. - household contents coverage

Why Replacement Cost Coverage Matters Most

Depreciation gaps leave you absorbing the real cost of rebuilding your life after a loss. Replacement Cost Coverage protects you from this financial burden by ensuring you can actually replace what you lost, not just receive a fraction of its value. Most homeowners who experience a significant loss wish they had chosen this option before disaster struck.

Understanding what your current policy covers sets the foundation for identifying gaps. The real vulnerability emerges when you compare your coverage limits to what you actually own-which is where most households discover they’re significantly underprotected.

Where Your Coverage Actually Falls Short

The gap between what homeowners think they’re covered for and what their policy actually pays is where financial disaster happens. Standard homeowners policies impose sublimits on high-value items, meaning jewelry might be capped at $1,500 total coverage regardless of actual value, and electronics often face similar restrictions. A homeowner with a $3,000 diamond ring and $2,000 in watches discovers during a burglary claim that their policy pays only $1,500 for all jewelry combined, leaving them absorbing $3,500 in losses. Electronics face the same problem-a home theater system worth $4,000 might have a $2,500 sublimit, forcing you to cover the difference yourself.

Common homeowners policy sublimits and example shortfalls. - household contents coverage

These aren’t rare edge cases; they’re standard policy structures that catch most homeowners unprepared.

High-Value Items Hit Hard

Sublimits devastate owners of valuable possessions. High-value items like jewelry, watches, and art face per-item or category sublimits on standard homeowners policies. A single piece of jewelry worth $5,000 might trigger a $1,500 sublimit, leaving you responsible for $3,500. Electronics suffer equally-your home theater system, computers, and cameras all face restricted coverage amounts. Standard policies impose these sublimits specifically on high-value items, which means your most expensive belongings receive the least protection. Without scheduled endorsements that list individual items with appraised values, you absorb the gap between what your policy pays and what replacement actually costs.

The Replacement Cost Reality Check

Many people believe their $50,000 contents limit covers everything they own until they actually price replacement. A modest home inventory includes a $3,000 sofa, $2,500 dining table, $2,000 bedroom set, $1,500 kitchen appliances, $1,200 washer and dryer, $800 in clothing per bedroom, $1,500 in linens and curtains, and $2,000 in electronics-you’ve already hit $15,000 before accounting for tools, outdoor equipment, or decorative items. Typical homes contain $50,000 to $100,000 in belongings, yet most people carry limits 30 to 50 percent below actual replacement value. When loss occurs, the gap between your limit and actual replacement cost becomes your personal financial responsibility. Inflation only worsens this problem-replacement costs for furniture and appliances have risen significantly, meaning a $50,000 limit from five years ago covers substantially less today.

Common Exclusions That Leave You Exposed

Specific categories face exclusions that devastate unprepared homeowners. Flood damage isn’t covered by standard homeowners policies, requiring a separate flood insurance policy through the National Flood Insurance Program if you live in a flood-prone area. Sewer backup and sump pump overflow are commonly excluded as well, yet these water-related losses happen frequently in basements. High-value art, collectibles, and antiques often exceed standard sublimits and require separate scheduling through an appraisal process. Business equipment and home office property may need endorsements if you work from home, and standard policies typically don’t cover business liability from home-based work.

How Scheduled Personal Property Fixes the Problem

Scheduled Personal Property endorsements exist specifically to address these gaps. You list individual high-value items with their appraised values and receive full replacement cost protection for each one. This approach eliminates sublimits for the items you schedule, meaning your $5,000 jewelry collection receives $5,000 in coverage, not $1,500. The appraisal process requires documentation, but it protects what matters most. Without these endorsements, you’re gambling that nothing valuable gets damaged or stolen-and that’s a bet most homeowners lose eventually. The real question isn’t whether you need these protections, but rather which items in your home demand them most urgently.

Sizing Your Coverage to Match What You Actually Own

The disconnect between coverage limits and actual belongings destroys most homeowners during claims. We regularly see policies with $40,000 limits protecting homes containing $80,000 or more in furniture, electronics, and personal items. The only way to avoid this trap is conducting a thorough home inventory, calculating your true replacement value, and matching your coverage accordingly.

Walk Through Each Room and Document Everything

Start by moving through each room with your phone or camera and documenting everything systematically. Your lounge likely contains a television worth $1,500 to $2,500, a sofa at $2,500 to $4,000, and additional furniture totaling another $2,000 to $3,000. Kitchen appliances including a dishwasher at $1,200, refrigerator, and small appliances easily reach $3,500 to $4,000. Bedrooms multiply these costs-each bedroom needs a bed frame, mattress, dresser, and nightstands running $2,000 to $3,500 per room.

Most homeowners complete this exercise and discover their actual belongings total $60,000 to $100,000, yet their policy covers only $35,000 to $50,000. For a quick estimate of the amount of insurance you need, multiply the total square footage of your home by local, per-square-foot building costs. Instead, calculate your actual replacement value and set your limit at least 10 to 15 percent higher to account for inflation and items you’ll inevitably forget during inventory.

Store Your Inventory Where Fire Can’t Reach It

Photographs and receipts become worthless if they burn in the same fire that destroys your belongings. Store your inventory digitally in cloud storage like Google Drive or Dropbox, separate from your home entirely. Document each item’s description, purchase date, purchase price, and current replacement value-not depreciated value.

A five-year-old sofa originally purchased for $2,500 may be worth $600 in actual cash value, but it costs $2,800 to replace with a similar sofa today, and replacement cost is what matters for coverage decisions. Include serial numbers and model numbers for electronics, appliances, and high-value items, as insurers request these during claims. For jewelry, watches, art, and collectibles exceeding $1,500 individually, obtain professional appraisals from certified appraisers and attach them to your policy records (these appraisals cost $100 to $300 per item but eliminate disputes during claims and justify scheduled endorsements that provide full replacement cost protection).

Update Your Inventory After Major Purchases

Update your inventory annually or within 30 days of major purchases-a new television, furniture replacement, or jewelry acquisition changes your coverage needs immediately. Most homeowners skip this step and discover gaps only when filing claims, at which point adjustments won’t help.

Compare Your Limit Against Your Documented Inventory

Set a calendar reminder each January to compare your current limit against your documented inventory value. If your inventory totals $75,000 and your coverage limit is $50,000, you’re underinsured by 33 percent-a gap that becomes your personal loss during a claim. Inflation typically increases replacement costs 3 to 5 percent annually, so a $50,000 limit from 2021 covers roughly 20 percent less today (add new furniture, electronics, or collectibles, and the gap widens further).

Example showing a 33% underinsured gap between inventory and coverage limit.

Request a coverage review from your agent whenever you make significant purchases, refinance your home, or suspect your limit may be insufficient. Don’t wait for renewal-changes during the policy year ensure immediate protection. High-value items acquired after your last appraisal should receive updated professional valuations before adding scheduled endorsements, as appraisals from years past don’t reflect current market prices.

Final Thoughts

The gap between what homeowners think they’re covered for and what their policies actually pay creates financial disaster when loss strikes. Household contents coverage protects your belongings, but only if your limits match what you actually own and your policy addresses high-value items through scheduled endorsements. Most homeowners discover this mismatch too late, during claims when adjustments can’t help.

Complete a thorough home inventory by walking through each room and documenting everything with descriptions, purchase dates, and current replacement values, then store this inventory digitally in cloud storage separate from your home so fire or theft won’t destroy your documentation. Calculate your total replacement value honestly-most homes contain $60,000 to $100,000 in belongings, yet many policies cover only $35,000 to $50,000-and identify high-value items like jewelry, watches, or art that exceed $1,500 individually so you can obtain professional appraisals for scheduled endorsements that eliminate sublimits. Set a calendar reminder each January to compare your documented inventory against your current coverage limit and adjust for inflation and new purchases, then request a coverage review from your agent whenever you acquire significant items or suspect your limit is insufficient.

Contact our team for a policy review and let us help you ensure your household contents coverage protects what matters most to your family.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation
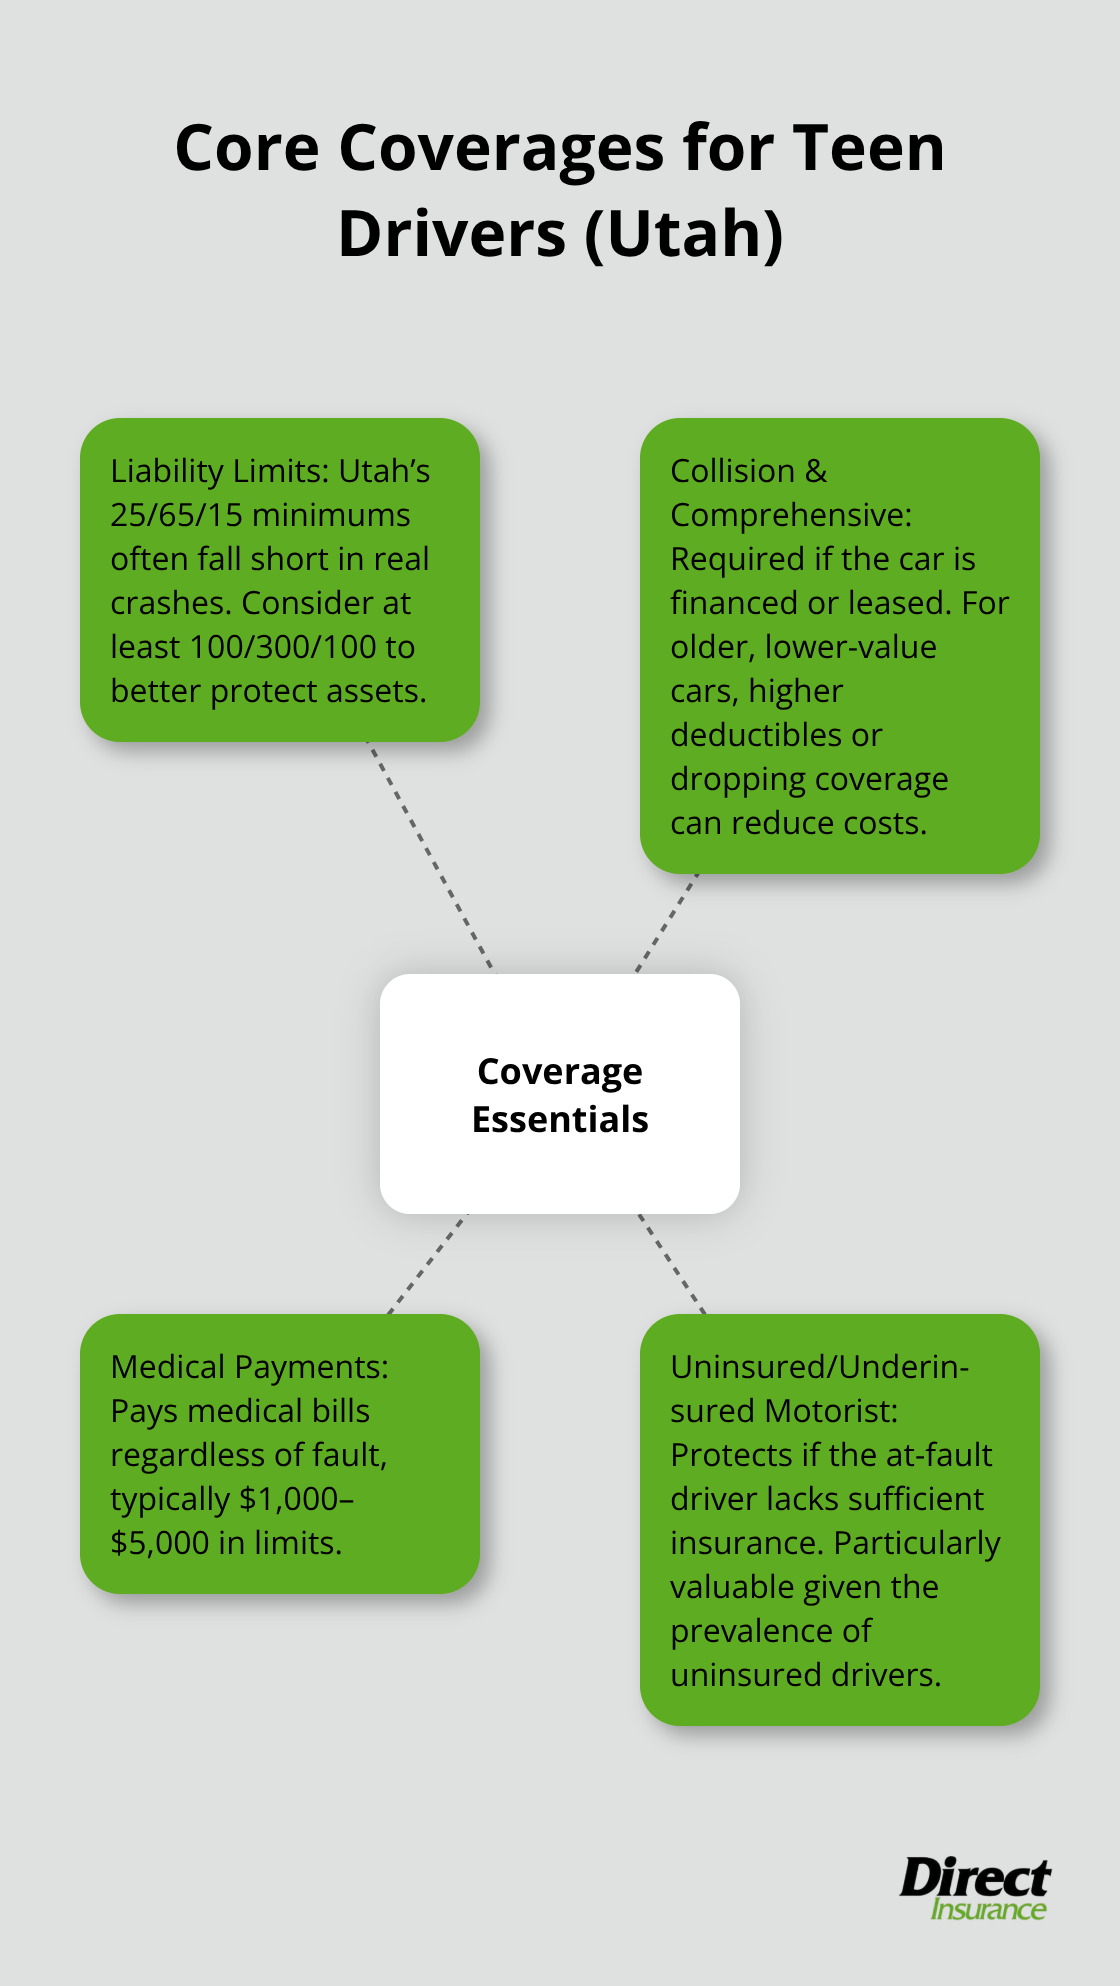
Most people pay more for insurance than they need to. Bundling your home and auto insurance is one of the fastest ways to cut costs without sacrificing coverage.

At Direct Insurance Services, we’ve helped thousands of customers save money by combining their policies. This guide shows you exactly how bundling works and what savings you can realistically expect.

What Bundling Actually Means for Your Wallet

Bundling is straightforward: you combine your home and auto insurance with the same company and receive a discount on your total premium. That’s it. No complicated formulas or hidden conditions. When you bundle, insurers reduce your rates because you give them more of your business and they spend less time managing your accounts. Bundling stands as one of the most direct ways to lower your insurance costs without cutting coverage.

The discount you receive depends entirely on your insurer and your state, but the range is real. Multi-policy discounts average 18%. State Farm customers report savings around 17%, while Progressive advertises discounts up to 25% for new customers. Liberty Mutual reports that new customers who switch and bundle auto and home save approximately $950 per year on average. These aren’t theoretical numbers-they’re what actual customers are seeing. The variation matters because your home’s age, location, vehicle type, driving history, and claims record all affect the final discount. A newer home in a low-crime area with a clean driving record will likely qualify for a larger discount than an older property in a different zip code. The best approach is to get quotes from at least three carriers and compare the bundled total against what you’d pay for separate policies. Sometimes bundling wins. Sometimes you’ll pay less when you buy auto from one company and home from another. You won’t know without running the numbers yourself.

How Discounts Stack on Top of Bundling

The multi-policy discount is just the foundation. Once you bundle, you can layer additional savings on top. Autopay discounts (typically 1–3% off), paperless billing discounts, safety device discounts for your home, and safe-driver programs for your vehicle all combine with your bundle savings. If you install a security system, smoke detectors, or deadbolts, your homeowners premium drops further. If you maintain a clean driving record or use a telematics app that tracks safe driving habits, your auto premium falls too.

Hub-and-spoke diagram showing stackable discounts that combine with a home and auto bundle.

These secondary discounts are where bundling becomes even more valuable because they apply across both policies simultaneously. Ask your agent explicitly which discounts stack and which ones don’t-some carriers limit how many discounts you can claim in a single category.

Why Bundle Savings Vary So Much

Your actual savings depend on how the insurer calculates the discount. Some carriers apply a fixed percentage to both policies equally. Others tier their discounts based on risk level and property value. High-value homes or vehicles sometimes trigger different discount structures than standard properties. Deductible choices matter too. If you select a $1,000 deductible instead of $500, your premium falls, which means your bundle discount is calculated on a lower base number. Coordinating your renewal dates across both policies ensures the bundle discount applies to both at the same time. If your auto policy renews in March and your home policy renews in September, you might miss out on combined savings during the gap. Align renewal dates so discounts work together and you avoid gaps in coverage.

What Happens When You Actually Compare Quotes

Getting quotes from multiple carriers reveals which bundle truly saves you the most money. One insurer might offer a 20% discount on a $1,200 annual home premium and a $900 annual auto premium, totaling $1,980 after the discount. Another carrier might offer 15% off the same combined premium of $2,100, totaling $1,785. The second option wins, even though the discount percentage is lower. This is why comparing total costs matters far more than comparing discount percentages. Online quote tools let you enter your information once and receive bundled quotes from several carriers within minutes. You’ll see the exact dollar amount you’d pay, not just a percentage. Some carriers require agent-assisted quotes, which takes longer but often provides more detailed customization options for your specific situation.

What Real Savings Look Like When You Bundle

The numbers tell a clear story. Liberty Mutual reports that new customers switching and bundling auto and home save approximately $950 per year on average, based on a nationwide survey. State Farm customers see bundled discounts around 17%, which translates to roughly $1,429 in annual savings for some policyholders. Progressive advertises discounts up to 25% for new customers who bundle, while Travelers offers up to 15% in bundle savings.

Chart showing common bundle discount percentages from major U.S. insurers. - home and auto bundle

These aren’t hypothetical percentages-they’re actual dollars that real people keep in their pockets every year.

Your Situation Determines Your Actual Savings

The variation exists because your specific circumstances drive the final number. A 25-year-old driver with a clean record living in a low-crime suburb will save more than a 35-year-old with one accident living in an urban area. An older home in need of updates qualifies for smaller discounts than a newly built property with modern safety features. The only way to know your exact savings is to request quotes from at least three carriers and calculate the total cost of bundling versus buying policies separately. One carrier might beat another by $200 or $300 annually, which compounds to thousands of dollars over five years.

Bundling Often Beats Individual Policies, But Not Always

This matters: bundling doesn’t automatically guarantee the cheapest total price. Sometimes your auto rate is significantly cheaper with one company while another carrier offers a better home rate. If Carrier A quotes $1,100 for auto and $1,800 for home with a 20% bundle discount totaling $2,320, but Carrier B quotes $950 for auto alone and $1,600 for home alone totaling $2,550 unbundled, Carrier A wins even though Carrier B has cheaper individual rates. However, if Carrier C quotes $900 for auto and $1,400 for home unbundled totaling $2,300, you save $20 compared to bundling. The math requires actual numbers from your quotes, not assumptions.

Secondary Discounts Stack With Your Bundle

The secondary discounts layer on top and shift the equation further. If you qualify for autopay discounts (1–3% off), safety device discounts for your home, and a safe-driver program for your vehicle, these stack with your bundle discount. A customer with a bundled policy receiving a 20% multi-policy discount plus a 2% autopay discount plus a 5% safety device discount ends up saving far more than the base 20% suggests. These additional discounts apply across both policies simultaneously, making bundling increasingly valuable the more discounts you qualify for.

Where Additional Savings Hide

Security systems, smoke detectors, and deadbolts reduce your homeowners premium. If you install these devices before requesting quotes, your base home premium drops, which means your bundle discount is calculated on a lower foundation. A telematics app that monitors safe driving habits can reduce your auto premium by up to 30% with some carriers, though eligibility varies. Combining a telematics discount with your bundle discount produces substantial savings that most customers overlook.

Paying your premium annually instead of monthly saves money with most carriers. Maintaining continuous coverage without gaps qualifies you for loyalty discounts that increase over time. Some insurers reward customers who maintain both policies for multiple years with rate reductions or additional perks. The key is asking your agent which specific discounts apply to your situation and how they combine (some carriers restrict how many discounts you can stack in a single category, so clarification prevents surprises at renewal).

Now that you understand what real savings look like, the next step is learning how to actually compare quotes and identify which bundle works best for your home and vehicle.

Practical Steps to Bundle Your Home and Auto Insurance

Know Your Current Coverage Before You Compare

Start with what you actually have, not what you think you have. Pull out your current home and auto policies and write down three specific numbers: your annual premium for each policy and your deductible for each. Most people skip this step and waste time comparing quotes without a baseline. You need to know exactly what you’re paying now so you can measure whether a bundled quote actually saves money.

Check your policy documents for coverage limits too. Your homeowners policy should state your dwelling coverage amount, personal property limit, and liability limit. Your auto policy should show your liability limits, collision coverage, and comprehensive coverage. Write these down. When you request bundled quotes, you’ll want to match these same coverage levels across carriers so you’re comparing apples to apples, not a $300,000 dwelling limit from one insurer against a $250,000 limit from another.

If your home was built before 1980 or your vehicle is over ten years old, mention this upfront when requesting quotes because some carriers price older properties and vehicles differently, and this affects your bundle discount calculation. If you have any claims in the past three to five years, disclose them immediately. Bundled quotes change dramatically when you add a home claim or an at-fault accident, so carriers need this information to provide accurate numbers.

Request Quotes from Multiple Carriers

Requesting quotes from at least three different carriers takes roughly 30 minutes online but saves hundreds of dollars annually. Start with carriers that operate in your state and accept online quotes. Progressive, State Farm, Travelers, and Liberty Mutual all allow you to enter your information once and receive bundled quotes within minutes.

Compact checklist of quick steps to get and compare bundled insurance quotes.

Enter your current coverage levels exactly as they appear on your existing policies so the quotes reflect your actual protection. When the quotes appear, don’t just look at the bundled discount percentage. Look at the total annual cost for both policies combined. One carrier might offer a 20% bundle discount while another offers 15%, but the carrier with the lower percentage could have a lower total cost because their base rates are cheaper.

Calculate the total premium you’d pay annually with each carrier, then subtract that from your current total premium. That number is your actual savings. If one carrier quotes $2,100 bundled and you currently pay $2,400 total, you save $300 annually. That’s $1,500 over five years.

Work with an Independent Agent for Deeper Analysis

After you’ve collected quotes from three carriers, contact a local independent agent. Independent agents have access to multiple carriers and can often find bundle options that online quote tools don’t show. An agent can also explain which secondary discounts apply to your specific situation and how they stack with your multi-policy discount.

If you qualify for a safety device discount, autopay discount, and a safe-driver program, an agent can calculate the combined impact before you commit to a policy. This matters because some carriers restrict how many discounts you can claim simultaneously, and an agent knows these limitations for each company they represent. An independent agency like Direct Insurance Services can provide this level of personalized analysis without locking you into a single carrier’s offerings.

Final Thoughts

Bundling your home and auto insurance delivers three concrete benefits: lower premiums, simplified management, and access to additional discounts that stack on top of your base savings. New customers who bundle save approximately $950 per year on average, with some seeing discounts up to 25%, and over five years that compounds to thousands of dollars you keep instead of sending to an insurance company. Beyond the money, a home and auto bundle means one renewal date, one bill, one agent to contact, and one online portal to manage both policies.

The bundle only works when you compare quotes from multiple carriers and calculate your actual total cost. Request quotes from at least three insurers, match your current coverage levels across all quotes, and compare the final annual premium, then layer in secondary discounts like autopay, safety devices, and safe-driver programs to see your true savings potential. Don’t assume the highest discount percentage wins-the lowest total annual cost is what matters.

We at Direct Insurance Services help Utah families and individuals navigate bundling without pressure or one-size-fits-all solutions. Contact Direct Insurance Services today for a personalized quote and let our experienced team show you exactly how much your home and auto bundle could save.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation

Condo association insurance protects both your property and your finances, but most owners don’t fully understand what their coverage actually includes. The gap between what your HOA’s master policy covers and what you need to protect personally creates real financial risk.

At Direct Insurance Services, we’ve seen too many condo owners face unexpected costs because they didn’t know the difference. This guide breaks down exactly what you need to know about condo insurance so you can avoid costly mistakes.

What Your HOA Master Policy Actually Covers

The Building Structure and Common Areas

Your HOA’s master policy protects the building structure and common areas that benefit all residents, but coverage limits and what qualifies as part of the building varies significantly depending on how your association structured the policy. Most master policies cover the roof, exterior walls, foundation, and shared spaces like hallways, lobbies, pools, and parking areas. The policy also includes liability coverage for injuries that occur in these common areas, protecting the association and its board members from lawsuits.

Minimum Coverage Requirements

Minnesota’s condo insurance requirements under MCIOA mandate that associations carry property insurance with full replacement cost and commercial general liability at minimum. Many lenders also require Employee Dishonesty coverage. This baseline protection forms the foundation of what your HOA provides, but it doesn’t tell the full story about what you personally need to protect.

Bare Walls Versus All-In Coverage

The confusion starts here: some master policies are written as bare walls coverage, meaning they only protect the structural frame and shared spaces while leaving unit interiors entirely to owners. Other policies use all-in coverage, extending protection to built-in fixtures, flooring, and even some upgraded finishes inside individual units. The difference matters enormously because it determines what gaps you personally must fill with your own HO-6 policy.

Loss Assessment Protection

Loss assessment coverage protects you from special assessments when a major loss exceeds the master policy’s limits. If a building-wide disaster like a roof collapse or significant fire damage occurs and the association’s insurance doesn’t fully cover the repair costs, the board can impose a special assessment on all owners to cover the shortfall. Without loss assessment coverage on your individual HO-6 policy, you could face thousands in unexpected bills. Fannie Mae and the FHA recognize this risk, which is why loss assessment endorsements are increasingly standard on HO-6 policies in communities with shared liability exposure.

Understanding Coverage Limits and Valuation Methods

The actual coverage limits in your master policy matter more than most owners realize. A roof replacement that costs $500,000 but only has $300,000 in coverage leaves a $200,000 gap that could trigger an assessment. Additionally, the difference between Actual Cash Value and Replacement Cost coverage affects what gets paid out. A hail-damaged roof with a $1,000,000 replacement cost but 15 years of age might only pay $600,000 under ACV versus $900,000 under replacement cost.

Three key takeaways explaining coverage shortfalls and ACV vs. Replacement Cost for condo owners in the U.S. - condo association insurance

Your HOA should provide you with a certificate of insurance and the Master Hazard Declaration so you know exactly what’s covered, what limits apply, and where your personal coverage needs to begin. Understanding these details now prevents surprises later when you need to file a claim or face an unexpected assessment.

Where Your HOA Coverage Ends and Yours Begins

Understanding the Two-Layer Protection System

Your HOA’s master policy and your individual HO-6 policy operate in two separate layers, and understanding exactly where one stops and the other starts determines whether you stay protected or face exposure. The master policy covers the building’s structural elements and common areas that serve all residents, while your HO-6 protects everything inside your unit that the master policy doesn’t touch. In Minnesota, MCIOA requires associations to carry property insurance with full replacement cost, but that requirement alone doesn’t tell you what happens to your personal interior finishes, upgraded fixtures, or belongings if disaster strikes. Most condo owners assume their HOA has them covered completely, then face a rude awakening when they file a claim and discover their kitchen cabinets, flooring, or custom lighting weren’t included in the master policy’s scope.

Hub-and-spoke diagram showing the two-layer condo insurance system for U.S. owners.

What the Master Policy Actually Protects

The master policy typically covers the roof, exterior walls, foundation, structural framing, and common areas like hallways and lobbies. Anything beyond that-your drywall, paint, flooring, built-in appliances, countertops, and personal property-falls to you. If your HOA uses bare walls coverage, which many do, the association covers only the structural frame and shared spaces, leaving nearly everything inside your unit your responsibility. Even with all-in coverage, which extends to some built-in fixtures, gaps still exist around upgraded finishes or improvements you’ve made since purchase.

The Financial Risk of Misaligned Coverage

The real financial risk emerges when you don’t align your HO-6 limits with what the master policy actually excludes. A $300,000 master policy with a $500,000 roof replacement cost creates a $200,000 shortfall that can trigger a special assessment on all owners. Your loss assessment coverage protects against these surprise bills, but only if you purchased the endorsement on your HO-6. Without it, you could face thousands in unexpected costs when the association’s insurance falls short. Fannie Mae and the FHA increasingly recognize this exposure, which is why loss assessment endorsements are becoming standard on most HO-6 policies in communities with shared liability.

Getting the Documents You Need

Request your HOA’s certificate of insurance and Master Hazard Declaration immediately-these documents spell out exactly what’s covered and at what limits. Have your insurance agent review both documents side by side with your current HO-6 policy to identify gaps. Many owners discover they’re either duplicating coverage they don’t need or leaving themselves dangerously underinsured. If your current policy is an HO3 designed for single-family homes, you’re likely paying for coverage you don’t own, like the building structure. Switching to an HO-6 policy tailored to condo ownership reduces unnecessary costs while ensuring your interior and personal property receive proper protection.

Moving Forward with Confidence

The coordination between these two policies is not optional-it’s the difference between manageable risk and financial crisis. Once you understand what your master policy covers and what gaps exist in your personal protection, you can address the specific mistakes that leave most condo owners exposed. The next section reveals the most common errors owners make when setting up their coverage.

Common Insurance Mistakes Condo Owners Make

Underestimating Your Interior Replacement Costs

Most condo owners drastically underestimate what their interior actually costs to replace, and this mistake creates massive financial exposure. A kitchen renovation with custom cabinetry, granite countertops, and upgraded appliances easily runs $40,000 to $60,000, yet many owners carry HO-6 limits of only $15,000 to $20,000. When a fire or water damage destroys your unit, that gap between your coverage limit and your actual replacement cost becomes your personal financial responsibility. Request detailed replacement cost estimates from a contractor before you set your HO-6 limits, not after a loss occurs. Your insurance agent can help you calculate the true replacement cost of your flooring, fixtures, and finishes so your coverage actually matches what you own.

Misunderstanding Policy Limits and Deductibles

The second mistake involves misunderstanding your policy’s actual limits and how deductibles work across multiple coverage types. Many owners think their $300,000 dwelling limit applies to every type of damage equally, when in reality some perils carry separate limits or higher deductibles. Water damage from a burst pipe might have a $5,000 limit or a $2,500 deductible, while fire carries a different threshold entirely. Read your HO-6 declarations page carefully-the actual coverage summary shows exactly what limit applies to each peril and what you’ll pay out of pocket.

Checkmark list of the most common condo insurance mistakes for U.S. owners. - condo association insurance

Different perils (fire, theft, water damage, wind) often have different deductible amounts, and understanding these distinctions prevents shock when you file a claim.

Ignoring Policy Changes After HOA Modifications

The third and most dangerous error involves ignoring your policy after your HOA makes changes. If your association converts from bare walls coverage to all-in coverage, your old HO-6 might now duplicate coverage you no longer need, or if they reduce their limits, you suddenly face new exposure. When your HOA purchases a new master policy, renovates common areas, or hires a new property management company, request an updated certificate of insurance immediately and have your agent review it against your current HO-6. That annual review takes 30 minutes and prevents thousands in wasted premiums or dangerous coverage gaps. Your master policy can shift significantly from year to year, and your individual coverage must shift with it to stay aligned.

Final Thoughts

Your condo association insurance strategy requires action, not assumptions. Obtain your HOA’s certificate of insurance and Master Hazard Declaration, then compare what the master policy covers against what you own personally. This comparison reveals your actual gaps and prevents both overpaying for duplicate coverage and underinsuring critical assets. An HO-6 policy with limits that match your actual interior replacement costs, loss assessment protection, and liability coverage for injuries inside your unit form the essential foundation of your protection.

Review your condo association insurance annually and request an updated certificate whenever your HOA makes changes to their master policy, renovates common areas, or hires new management. Life changes matter too-if you upgrade your kitchen, add flooring, or install custom fixtures, your HO-6 limits need adjustment to reflect those improvements. Document your interior finishes with photos and keep receipts for upgrades so you have proof of value if you file a claim.

We at Direct Insurance Services help condo owners navigate these conversations and align their individual policies with their association’s master coverage. The coordination between these two layers of protection determines whether you face financial security or unexpected crisis when damage occurs. Take control of your coverage today.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation