
Boat Insurance Utah Essentials For Boat Owners
Utah’s lakes and rivers attract thousands of boat owners each year. Whether you’re navigating the Great Salt Lake or exploring smaller reservoirs, boat insurance in Utah isn’t optional-it’s a legal requirement and financial necessity.
At Direct Insurance Services, we help boat owners understand what coverage they actually need. This guide walks you through liability requirements, protection options, and how to find rates that fit your budget.
Why Boat Insurance Matters in Utah
Legal Requirements You Can’t Ignore
Utah’s boating regulations require liability insurance before you register any vessel with the state. The Utah Division of Wildlife Resources mandates that all motorized boats carry minimum liability coverage of $25,000/$50,000 bodily injury/death – $15,000 property damage or $65,000 combined minimum per accident. This isn’t bureaucratic red tape-it’s your legal shield. Without proof of insurance during registration, you won’t receive your title or registration papers. If you operate an uninsured boat, Utah law allows fines up to $1,000 and potential criminal charges.
The Real Cost of Boating Accidents
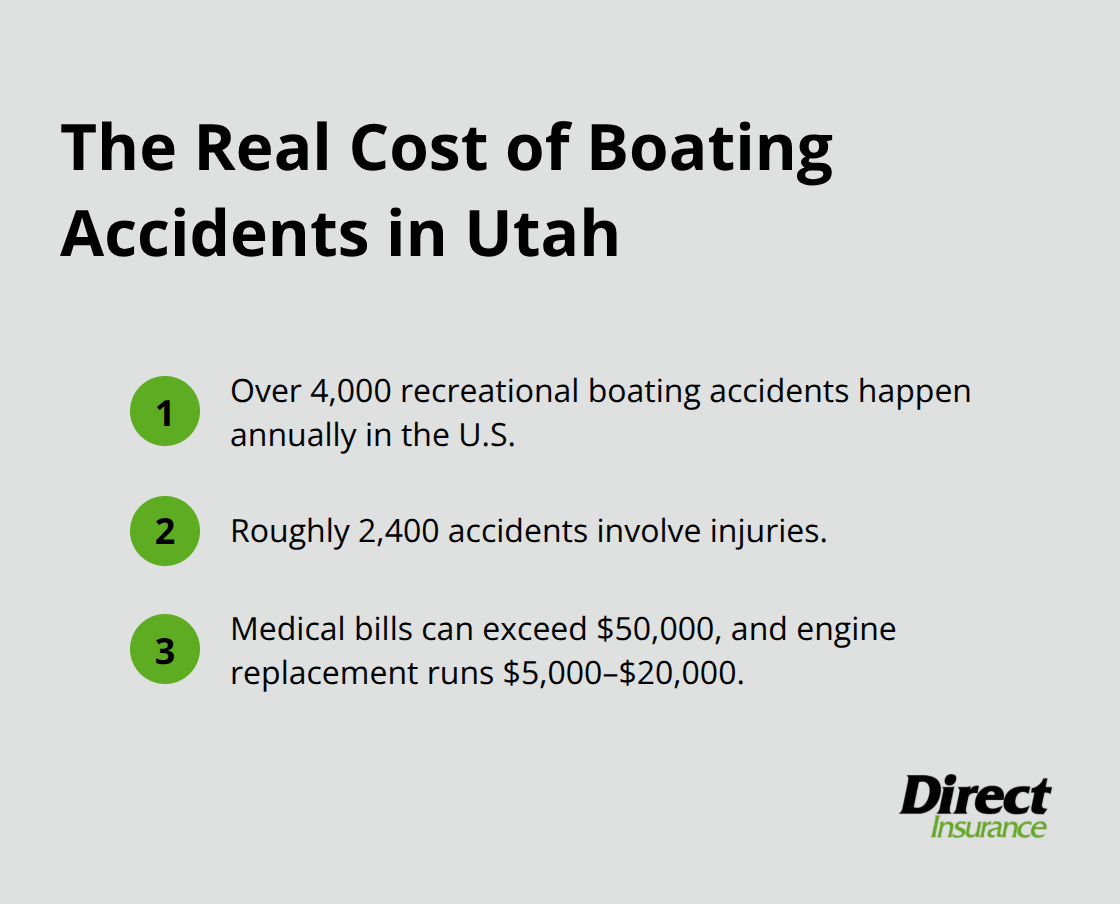
Boat accidents occur far more frequently than most owners realize. The U.S. Coast Guard reported over 4,000 recreational boating accidents annually in recent years, with roughly 2,400 involving injuries. Medical costs from a single boating accident can reach $50,000 or more if someone needs emergency treatment or hospitalization. Property damage claims are equally serious-replacing an engine costs between $5,000 and $20,000 depending on your boat type.
Protecting Your Assets and Your Boat
Liability coverage protects your personal assets if you’re found responsible for injuring someone or damaging their property. Collision and comprehensive coverage tackle your own boat’s damage from weather, theft, or accidents with other vessels. Utah’s unpredictable weather patterns (including sudden storms across the Great Salt Lake and flash flooding in reservoir areas) make comprehensive coverage practical rather than optional. Theft remains a real concern too-boat parts like outboard motors and electronics are frequently stolen, with replacement costs running into thousands of dollars.
Why Adequate Coverage Matters
Boat owners who faced devastating financial situations after accidents often skipped adequate coverage. A single liability claim without proper limits can wipe out savings or trigger wage garnishment for years. The financial protection that insurance provides isn’t just about meeting legal requirements-it’s about safeguarding everything you’ve worked to build.
Understanding these risks sets the stage for selecting the right coverage options for your specific situation.
Coverage Options That Actually Protect Your Boat
Liability Coverage Protects Your Assets
Liability coverage is non-negotiable in Utah, but the standard $25,000/$50,000/$15,000 minimums often fall short of real-world needs. If your boat injures someone seriously, medical bills can exceed $100,000 within days. Courts have awarded settlements well above these minimums in cases involving permanent disability or multiple injured parties.
We recommend liability limits of at least $25,000 bodily injury per person and $50,000 property damage for most boat owners. This coverage shields your actual assets from catastrophic claims.
Collision and Comprehensive Coverage for Your Boat
Collision coverage pays for damage to your own boat from accidents with other vessels or objects. Comprehensive coverage handles weather damage, theft, vandalism, and sinking-the threats that matter most in Utah waters.
The Great Salt Lake experiences sudden storms that capsize boats or cause engine damage costing thousands of dollars. Comprehensive coverage typically costs $300 to $800 annually depending on your boat’s value and age, making it practical protection rather than luxury spending.
Uninsured Boater Protection Fills a Critical Gap
Uninsured boater coverage protects you when another boat hits you and the operator carries no insurance. Your uninsured boater protection covers your medical bills and boat repairs without waiting for the other party’s claim to settle.
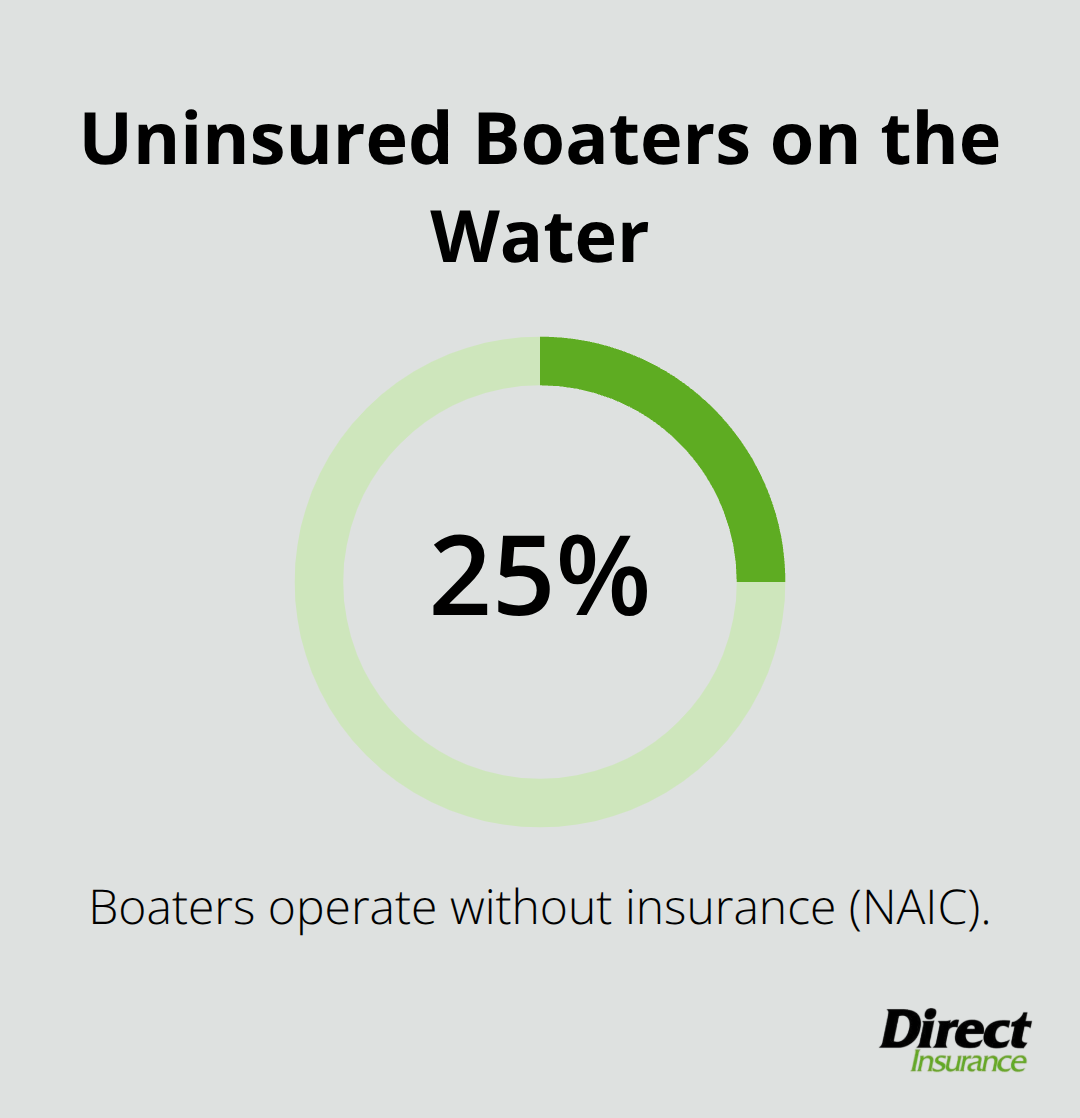
The National Association of Insurance Commissioners reports that roughly 25 percent of boaters operate without insurance, making this coverage statistically valuable for Utah waters. This protection addresses a real problem that affects many boat owners on Utah’s lakes and reservoirs.
Medical Payments Coverage for Emergencies
Medical payments coverage handles hospital visits and emergency treatment for you and your passengers without requiring proof of who caused the accident. A single water-skiing accident requiring helicopter evacuation and hospitalization can cost $50,000 to $150,000, and medical payments coverage covers these expenses directly.
Most policies include $1,000 to $5,000 in medical payments coverage as standard, though you can increase limits for higher-risk activities like towing or racing. These higher limits provide real protection when accidents happen on the water.
Selecting Coverage That Matches Your Boating Style
Your specific coverage needs depend on how you use your boat, where you boat, and what activities you pursue. A boat owner who tows skiers faces different risks than someone who fishes alone on a reservoir. The next step involves assessing your boat’s actual value and your typical usage patterns to determine which coverage options make financial sense for your situation.
Picking the Right Policy for Your Boat
Assess Your Boat’s Actual Value
Selecting boat insurance in Utah requires honest assessment of what your boat actually costs and how you use it. Many owners either underinsure their vessels to save money or overpay for coverage they don’t need. Start with your boat’s current market value, not what you paid for it years ago. Boats experience a significant 10% to 15% decline in value within their first year, so a boat purchased for $40,000 might be worth significantly less today.
Check recent sales of comparable vessels in Utah’s market on sites like MarineMax or local dealer inventories to establish realistic replacement costs. Your insurance limits should reflect this actual value, not inflated expectations. This step prevents you from paying premiums on coverage that exceeds your boat’s worth.
Match Coverage to Your Boating Activities
Document how you use your boat throughout the year. Do you tow skiers regularly, fish alone in remote reservoirs, or cruise with family on weekends? High-risk activities like towing require higher medical payments coverage and liability limits because injuries happen more frequently. Someone who boats 50 days annually on the Great Salt Lake faces different exposure than someone who launches twice yearly on a small reservoir.
This usage pattern directly affects which deductible levels make sense for your situation. Higher deductibles of $1,000 or $2,500 reduce your annual premium significantly but require you to absorb smaller damage claims yourself. If your boat sits idle most months, a $1,000 deductible might save you $200 to $400 annually while protecting against catastrophic losses.
Compare Quotes Across Multiple Carriers
Compare actual quotes from multiple carriers rather than relying on online estimates. Request quotes that include the same liability limits, deductibles, and coverage options across different insurers so you’re comparing identical protection, not just price tags. A $300 annual savings means nothing if you’re dropping from $100,000 to $50,000 in liability coverage.
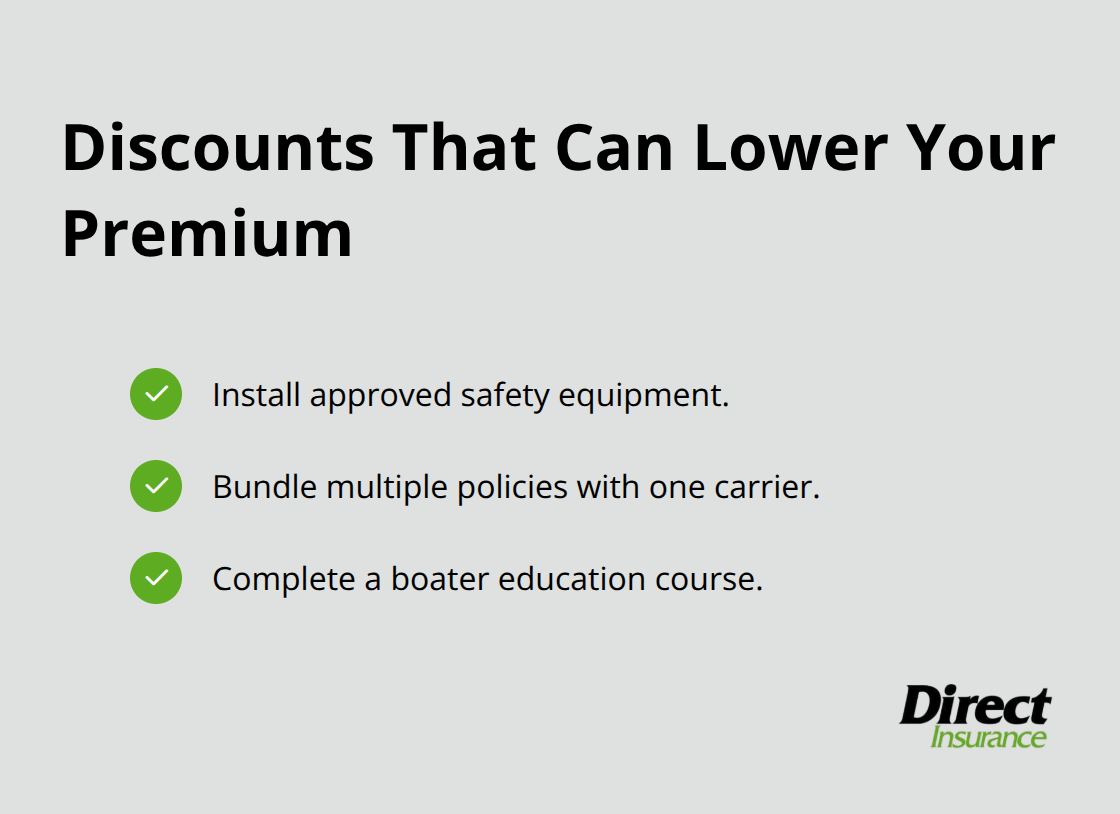
Utah’s independent agents can access carrier discounts for safety equipment, multi-policy bundling, and boater education courses that online quotes often miss entirely. These discounts reduce premiums by 10 to 25 percent depending on what you qualify for. Direct Insurance Services works with top-rated carriers to help boat owners find policies that match their specific needs and budgets.
Final Thoughts
Boat insurance in Utah protects both your legal standing and your financial future. The state’s mandatory liability requirements exist because boating accidents happen regularly, and the costs of medical treatment, property damage, and legal settlements can devastate uninsured owners. Your coverage decisions should reflect your boat’s actual value, how frequently you boat, and which activities you pursue on the water.
Liability shields your personal assets from catastrophic claims, while collision and comprehensive coverage protects your boat from weather, theft, and accidents. Medical payments coverage handles emergency treatment without requiring fault determination, and safety equipment discounts, multi-policy bundling, and boater education course credits reduce premiums by meaningful amounts. Utah’s independent agents understand local boating conditions and can identify discounts that online quotes miss entirely.
Contact Direct Insurance Services with details about your boat’s value, how you use it, and what coverage limits you’re considering. An agent will provide quotes that compare identical protection across different carriers so you can make informed decisions based on actual costs and coverage differences. Your boat represents an investment in recreation and family time, and appropriate boat insurance Utah coverage means boating with confidence rather than worrying about financial exposure.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


