
Landlord Liability Insurance Utah: Limits, Costs, and Protections
Owning rental property in Utah comes with real financial exposure. A single tenant injury or property damage claim can cost you tens of thousands of dollars-or more.
Landlord liability insurance in Utah protects you from these risks. At Direct Insurance Services, we help property owners understand their coverage options so they can make informed decisions about their protection.
What Landlord Liability Insurance Actually Covers
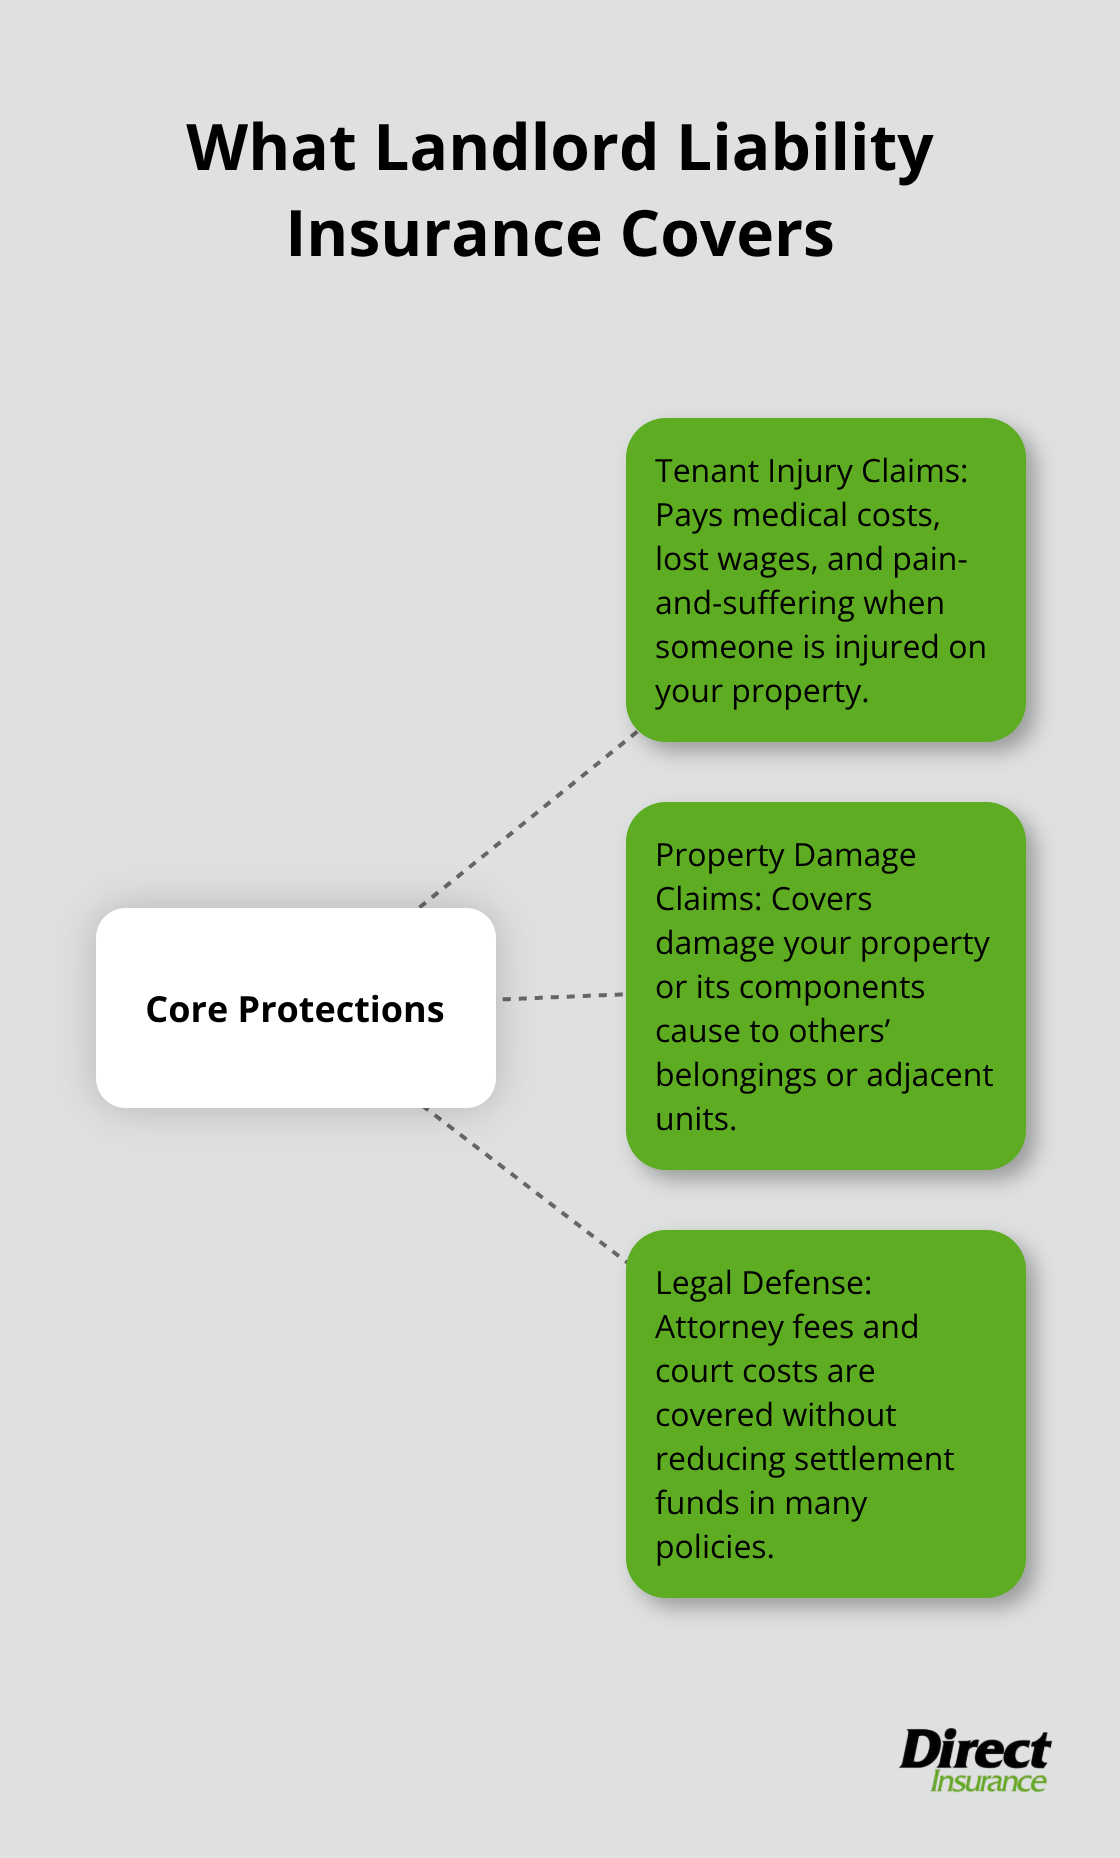
Landlord liability insurance protects you against claims when someone is injured on your rental property or when your property damages someone else’s belongings. The policy covers medical expenses, lost wages, and pain-and-suffering awards that a tenant or visitor might claim. It also pays for your legal defense if you end up in court, which matters because Utah courts have awarded significant damages in premises liability cases. The National Association of Insurance Commissioners reports that liability claims average between $15,000 and $300,000 depending on injury severity, though catastrophic cases exceed $1 million.
Core Coverage Types
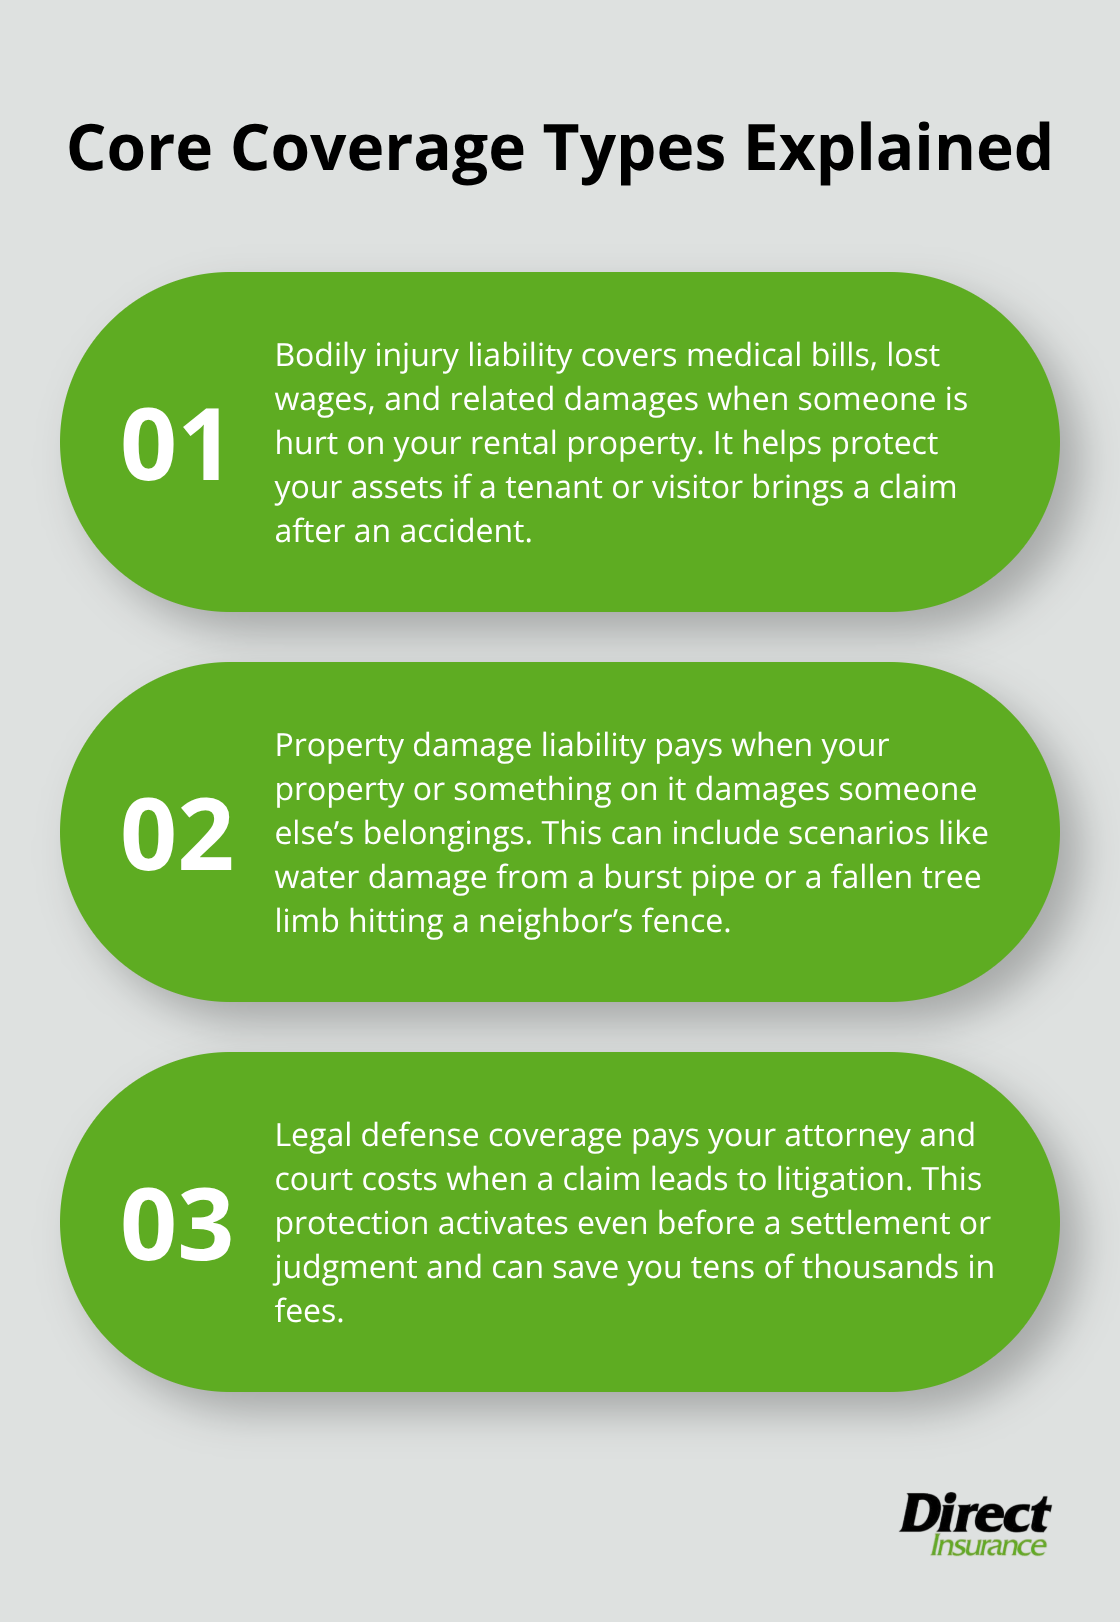
Bodily injury liability covers injuries sustained on your property. Property damage liability handles accidental damage your property causes to others’ belongings. Most policies also include legal defense costs, meaning the insurance company pays your attorney even before a settlement or judgment occurs. This protection matters significantly because legal fees alone can reach $10,000 to $50,000 in contested cases.
Why Utah Landlords Face Unique Exposure
Utah’s rental market has grown significantly over the past decade, with median rent increasing from around $900 in 2015 to approximately $1,400 today according to Zillow data. This growth means more properties, more tenants, and more opportunities for accidents. Winter weather creates specific hazards in Utah-ice on walkways, roof collapses from heavy snow, and frozen pipe damage all trigger liability claims regularly. The state’s active outdoor culture also means your property might host more visitors and activities than typical rentals elsewhere.
A tenant slips on an icy staircase, a guest sustains injury from an unmaintained handrail, or a burst pipe damages a neighbor’s property-these concrete scenarios Utah landlords handle frequently. Utah has no cap on pain-and-suffering damages in personal injury cases, which means a jury can award whatever amount they deem appropriate. This creates unpredictable financial exposure that standard homeowners insurance simply won’t cover for rental properties.
Legal Requirements and Your Actual Obligations
Utah law doesn’t mandate landlord liability insurance, but most mortgage lenders require it if you financed your rental property. More importantly, Utah Code Section 34-42-2 holds landlords responsible for maintaining premises in habitable condition and making repairs promptly. This legal duty means you face financial liability when someone is injured because you failed to maintain your property properly. If a tenant trips on a broken stair you knew about but never fixed, that constitutes negligence on your part, and your homeowners insurance won’t cover it because it excludes rental properties.
Many landlords mistakenly think their personal homeowners policy extends to rental units-it doesn’t. You need a separate landlord policy to have any protection at all. Without it, you personally pay every penny of a claim, which can include your own legal fees even before the case settles. Understanding these coverage gaps becomes critical when you start comparing quotes and evaluating which limits protect your assets.
Coverage Limits and Costs for Landlord Liability Insurance in Utah
Standard Coverage Limits and What They Cost
Utah landlords typically pay annual premiums between $300 and $800 for standard landlord liability insurance, though this varies considerably based on property specifics and coverage limits you select. Most carriers in Utah offer bodily injury liability limits starting at $100,000 per occurrence and $300,000 aggregate, with property damage limits around $50,000 per occurrence. These baseline limits prove insufficient for serious claims-a single catastrophic injury claim can easily exceed $500,000 when medical costs, lost wages, and pain-and-suffering damages combine.
We recommend Utah landlords carry at least $300,000 bodily injury coverage and $100,000 property damage coverage as a practical minimum, which typically costs between $450 and $650 annually depending on your property characteristics. Higher limits like $1 million bodily injury coverage add roughly $150 to $300 annually but provide substantially better protection against Utah’s uncapped pain-and-suffering awards.
Property Characteristics That Drive Your Premium
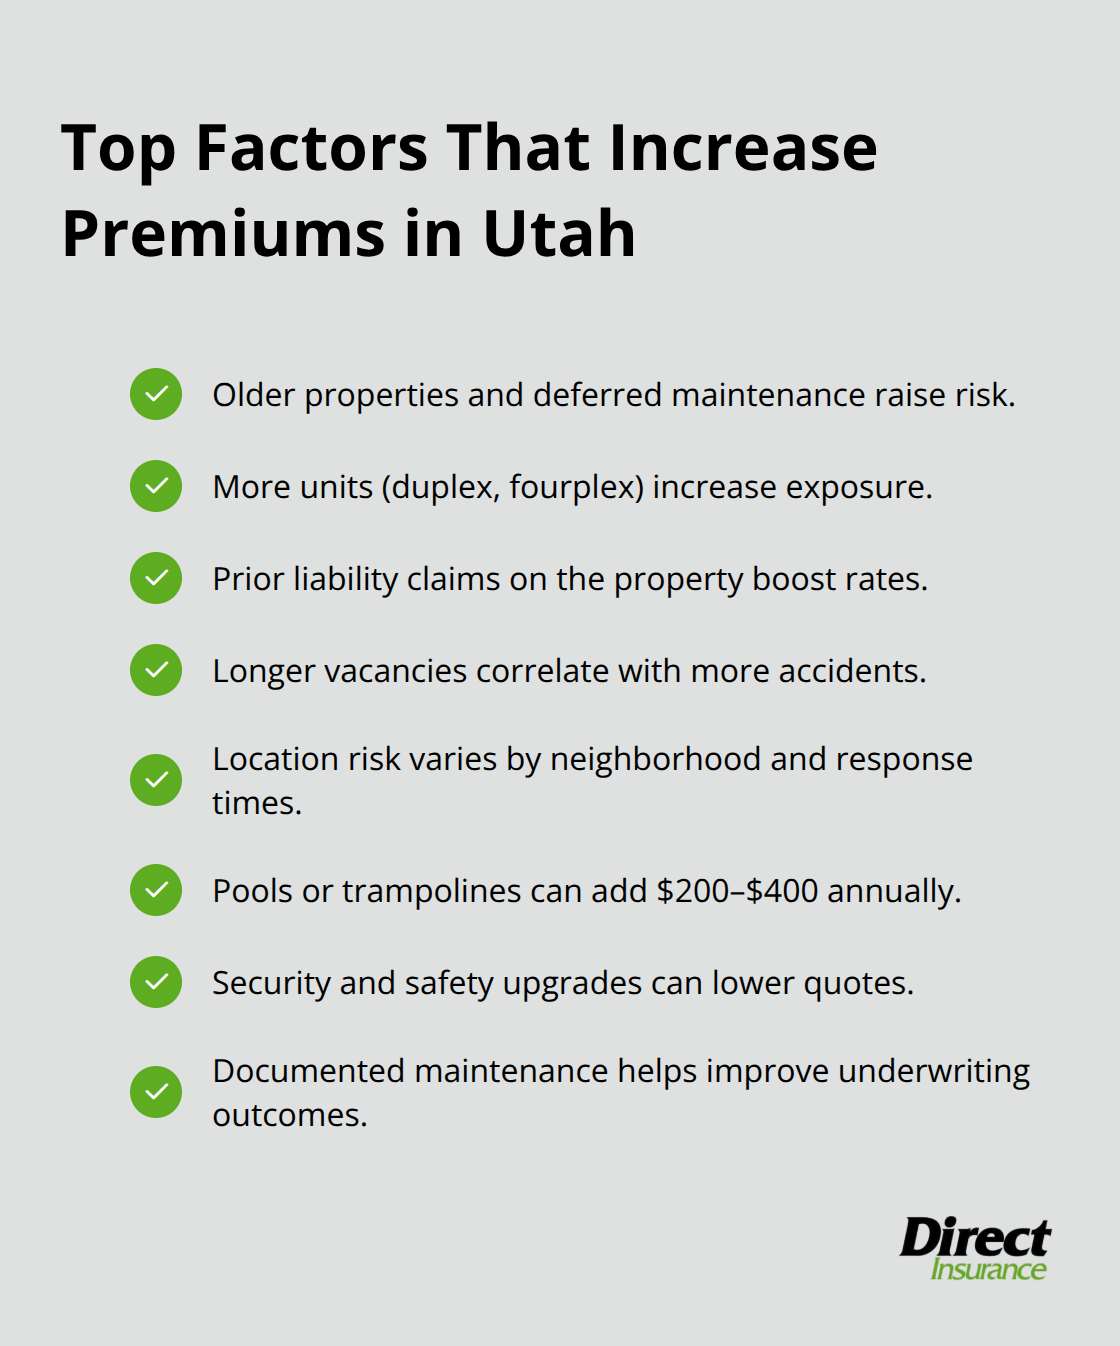
Your property’s age, condition, and maintenance history heavily influence what you’ll pay-a well-maintained single-family home in Salt Lake City costs less to insure than an older multi-unit building in a high-crime area. The number of units matters significantly; carriers charge more for fourplexes than duplexes, and multi-unit properties require higher premiums across the board. Claims history on the property itself drives costs up substantially; if the previous owner filed liability claims, expect higher quotes from most carriers.
Vacancy rates affect pricing too; properties sitting empty longer attract higher premiums because unmaintained properties generate more accidents. Location within Utah creates pricing differences; rural properties sometimes cost more due to longer emergency response times, while urban properties in certain neighborhoods may carry higher rates. Swimming pools, trampolines, or other attractive nuisances on your property increase premiums significantly-some carriers add $200 to $400 annually for pool coverage alone.
How to Compare Quotes Effectively
When comparing quotes from different carriers, request identical coverage limits and deductibles across all quotes to make apples-to-apples comparisons. Ask each carrier specifically what factors they weighted most heavily in their quote, because this reveals which improvements could lower your costs. A carrier pricing you high might heavily penalize older properties while another focuses primarily on claims history, meaning switching carriers could save $150 to $300 annually for the exact same coverage.
Request quotes from at least three carriers before deciding, and don’t assume the lowest quote provides adequate service-check complaint ratios through the Utah Department of Insurance before committing. Understanding these cost factors positions you to evaluate which coverage limits actually protect your assets against the specific risks your property faces.
Key Protections Landlord Liability Insurance Provides
Protection Against Tenant Injury Claims
Tenant injuries represent the most expensive liability exposure Utah landlords face, and your policy must cover the full range of costs that emerge after an accident occurs. When a tenant sustains an injury on your property-whether from a fall, electrical hazard, or maintenance failure-your landlord liability coverage pays their medical treatment, rehabilitation costs, lost wages during recovery, and pain-and-suffering damages awarded by a court or settlement.
Utah courts take these awards seriously. Premises liability cases have resulted in significant verdicts for tenant injuries. Your coverage limits directly determine whether you absorb these costs yourself or whether insurance protects your assets.
A $300,000 bodily injury limit sounds substantial until you face a catastrophic case. A tenant paralyzed by a fall or suffering severe burns from a maintenance failure can easily generate claims exceeding $1 million when medical expenses, lifetime care costs, and pain-and-suffering damages combine.
Coverage for Property Damage Claims
Property damage liability covers the other major exposure: when your property or something your property contains damages someone else’s belongings. A burst pipe floods a tenant’s electronics and furniture, a falling tree limb damages a neighbor’s fence, or faulty wiring causes fire damage to adjacent units-these scenarios trigger property damage claims that your policy handles.
Ask carriers specifically whether their property damage limits cover water damage and fire-related losses, because some policies restrict these coverages or apply separate sublimits. This distinction matters significantly when you evaluate which carrier offers the protection your property actually needs.
Legal Defense and Court Costs
Legal defense costs represent an underestimated protection that separates adequate policies from inadequate ones. Utah defense attorneys charge $250 to $400 hourly for premises liability cases, meaning even a straightforward case that settles quickly costs $10,000 to $25,000 in legal fees.
Your landlord liability insurance pays these defense costs separately from your coverage limits. The insurance company covers your attorney without reducing the money available for the actual claim settlement. This matters tremendously because some landlords face the impossible choice between hiring adequate legal representation or preserving funds for settlement without this protection.
Final Thoughts
Landlord liability insurance in Utah protects your assets from the financial devastation a single claim can cause. The risks are real, the costs are substantial, and Utah’s uncapped pain-and-suffering damages mean your exposure extends far beyond what most landlords anticipate. Standard homeowners insurance won’t cover your rental property, leaving you personally responsible for every penny of a claim without the right policy in place.
Securing adequate coverage requires you to determine your minimum acceptable limits based on your property’s characteristics and location within Utah. Request quotes from multiple carriers using identical coverage specifications so you can compare actual costs rather than making assumptions. Evaluate each carrier’s complaint history and claims handling reputation through the Utah Department of Insurance before committing to a policy.
An independent agent transforms this process from overwhelming to manageable by understanding Utah’s specific rental market conditions and identifying coverage gaps you might otherwise miss. The right landlord liability insurance Utah policy costs between $300 and $800 annually for most properties, a modest investment compared to the financial catastrophe an uninsured claim creates. Contact Direct Insurance Services today to discuss your specific property and get quotes that actually reflect your protection needs.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


