
St George snowmobile insurance: Local Protection for Your Ride
Snowmobiling in St George means navigating unique terrain and weather patterns that most insurance companies don’t fully understand. At Direct Insurance Services, we know the specific risks riders face in southern Utah-from sudden weather changes to challenging mountain conditions.
Getting the right St George snowmobile insurance isn’t just about meeting legal requirements. It’s about having protection that actually matches where and how you ride.
What Utah Snowmobilers Actually Need to Know About Coverage
Utah’s liability insurance requirements
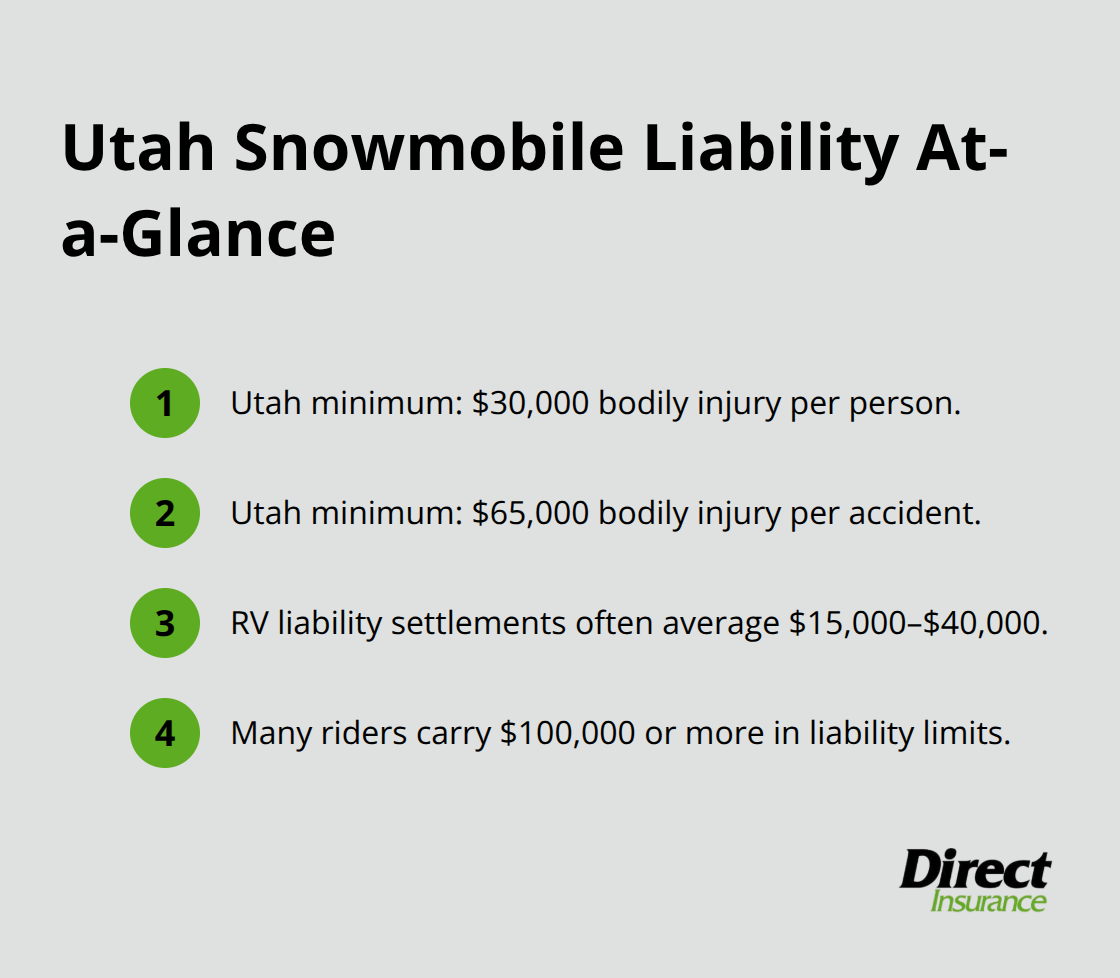
Utah requires snowmobile owners to carry liability insurance, with minimum limits of $30,000 for bodily injury per person and $65,000 for bodily injury per accident. These aren’t just bureaucratic numbers-they’re your financial protection if you injure someone while riding. A serious accident on southern Utah trails can result in medical bills exceeding $100,000 within hours. Without adequate liability coverage, you’re personally responsible for those costs.
Many riders assume their homeowners or auto policies cover snowmobile accidents, but they don’t. Utah law specifically requires a separate snowmobile policy, and getting one isn’t optional if you want to ride legally. This gap in coverage catches riders off guard every season.
Why liability protection matters beyond the law
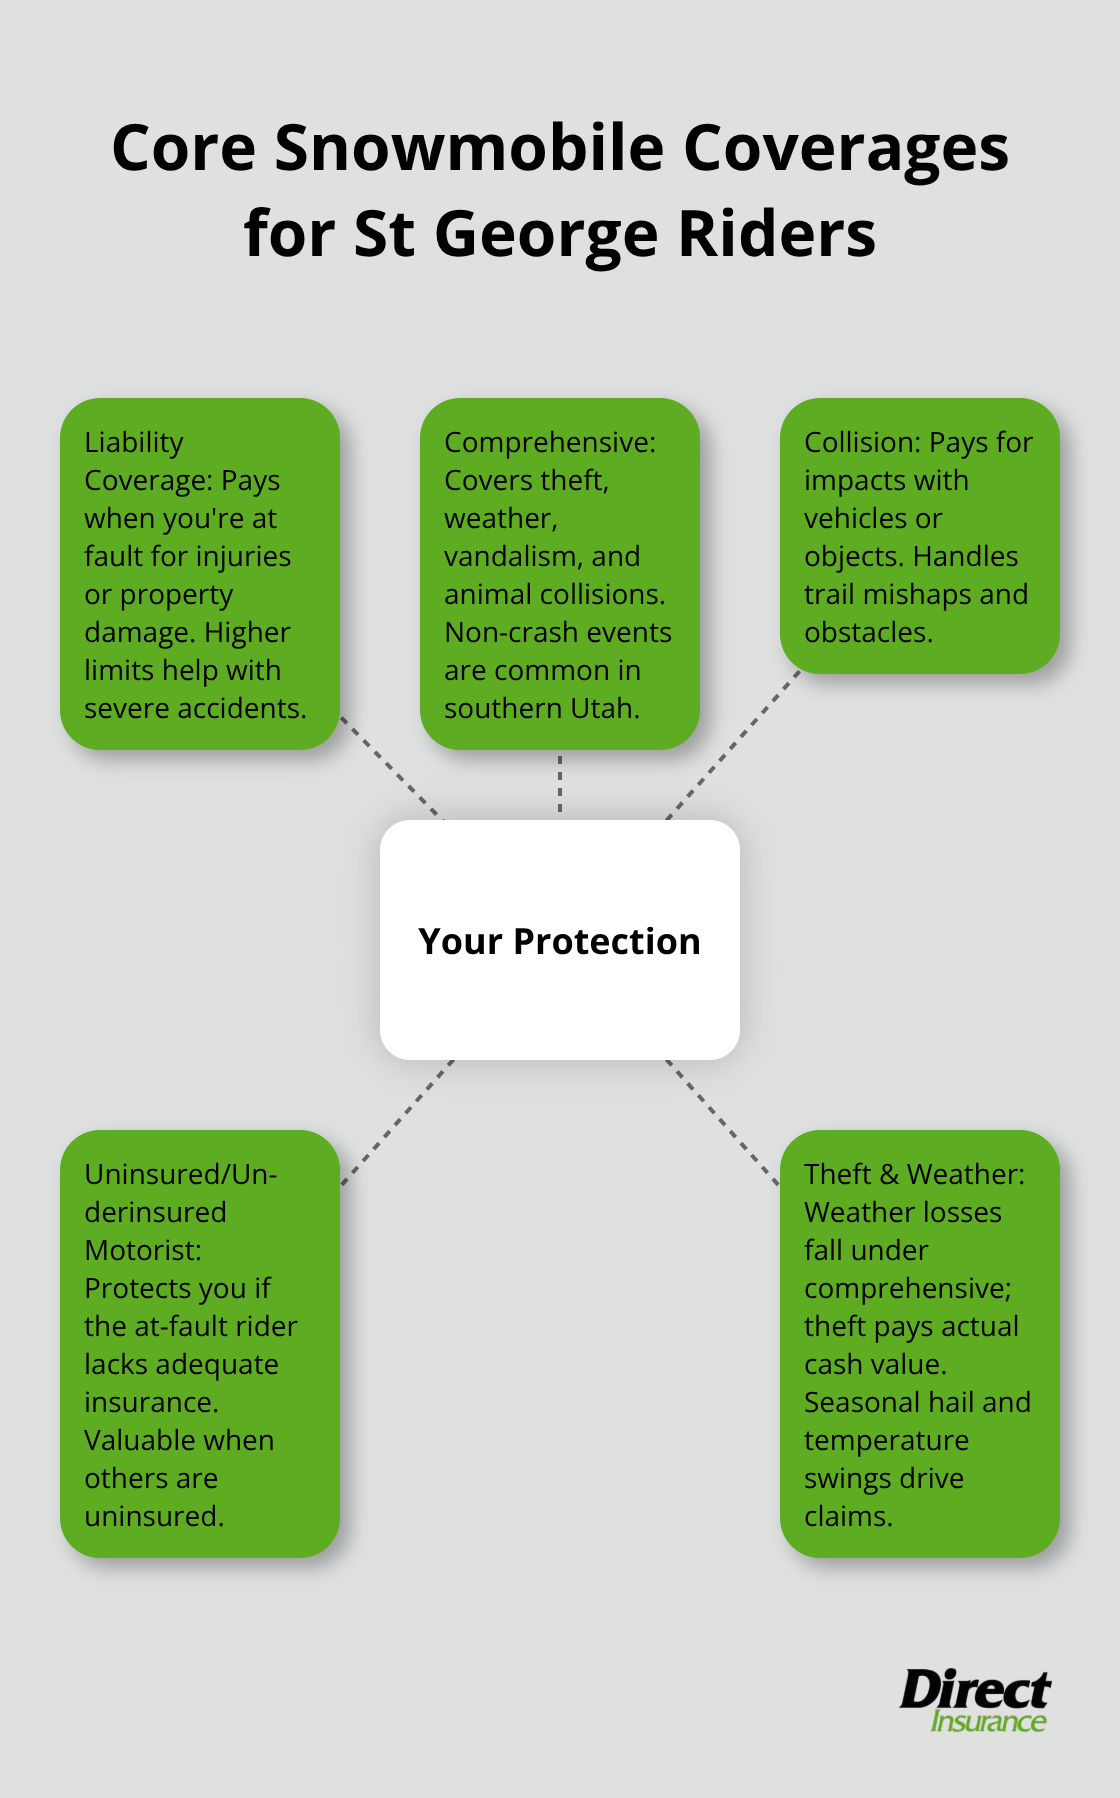
Liability coverage protects you when you’re at fault for someone else’s injuries or property damage. In St George terrain, where trails wind through challenging mountainous areas and weather shifts rapidly, accidents happen. A rider injured on a trail you were using, a bystander hit near a popular riding area, or property damage to someone’s home-these scenarios occur regularly.
The Insurance Information Institute reports that recreational vehicle liability claims average $15,000 to $40,000 in settlements. Utah’s minimum coverage of $65,000 for multiple injuries sounds adequate until you face a serious crash. Many experienced riders carry $100,000 or more in liability limits because they understand the real cost of accidents. Consider limits higher than the state minimum, especially if you ride frequently or have significant personal assets to protect.
Common misconceptions about snowmobile coverage
The most common misconception we encounter is that snowmobile insurance only covers theft. In reality, comprehensive coverage protects against theft, weather damage, vandalism, and animal collisions. Collision coverage handles accidents with other vehicles or objects. Many riders also believe their vehicle insurance extends to recreational equipment, which it doesn’t.
Another persistent myth is that casual, occasional riders don’t need coverage. Utah law applies regardless of how often you ride. Some riders think liability coverage is unnecessary if they only ride on private property, but accidents can happen anywhere, and liability still applies. Riders also underestimate the cost of snowmobile damage in southern Utah’s weather conditions. Heavy snow, hail, and temperature fluctuations cause significant damage annually.
Getting honest answers about what your policy actually covers prevents costly surprises when you need your insurance most. Understanding these misconceptions puts you ahead of most riders-and that knowledge becomes even more valuable when you explore the specific coverage options available to protect your snowmobile.
Coverage Options That Protect Your Snowmobile
Comprehensive and collision coverage explained
Comprehensive and collision coverage represent the two most misunderstood protections riders purchase. Comprehensive coverage handles damage from theft, weather, vandalism, and animal collisions-basically anything that isn’t a crash. Collision coverage pays for damage when your snowmobile hits another vehicle or object. Southern Utah’s weather causes significant damage claims annually.
Heavy snow loads crack windshields and damage frames. Hail dents hoods and seats. Temperature swings between 60-degree days and 20-degree nights crack plastic components and weaken seals.
If you ride in St George terrain regularly, comprehensive coverage isn’t optional-it’s financially necessary. Most riders choose $500 or $1,000 deductibles on comprehensive, which balances lower premiums against manageable out-of-pocket costs when weather strikes.
Uninsured and underinsured motorist protection
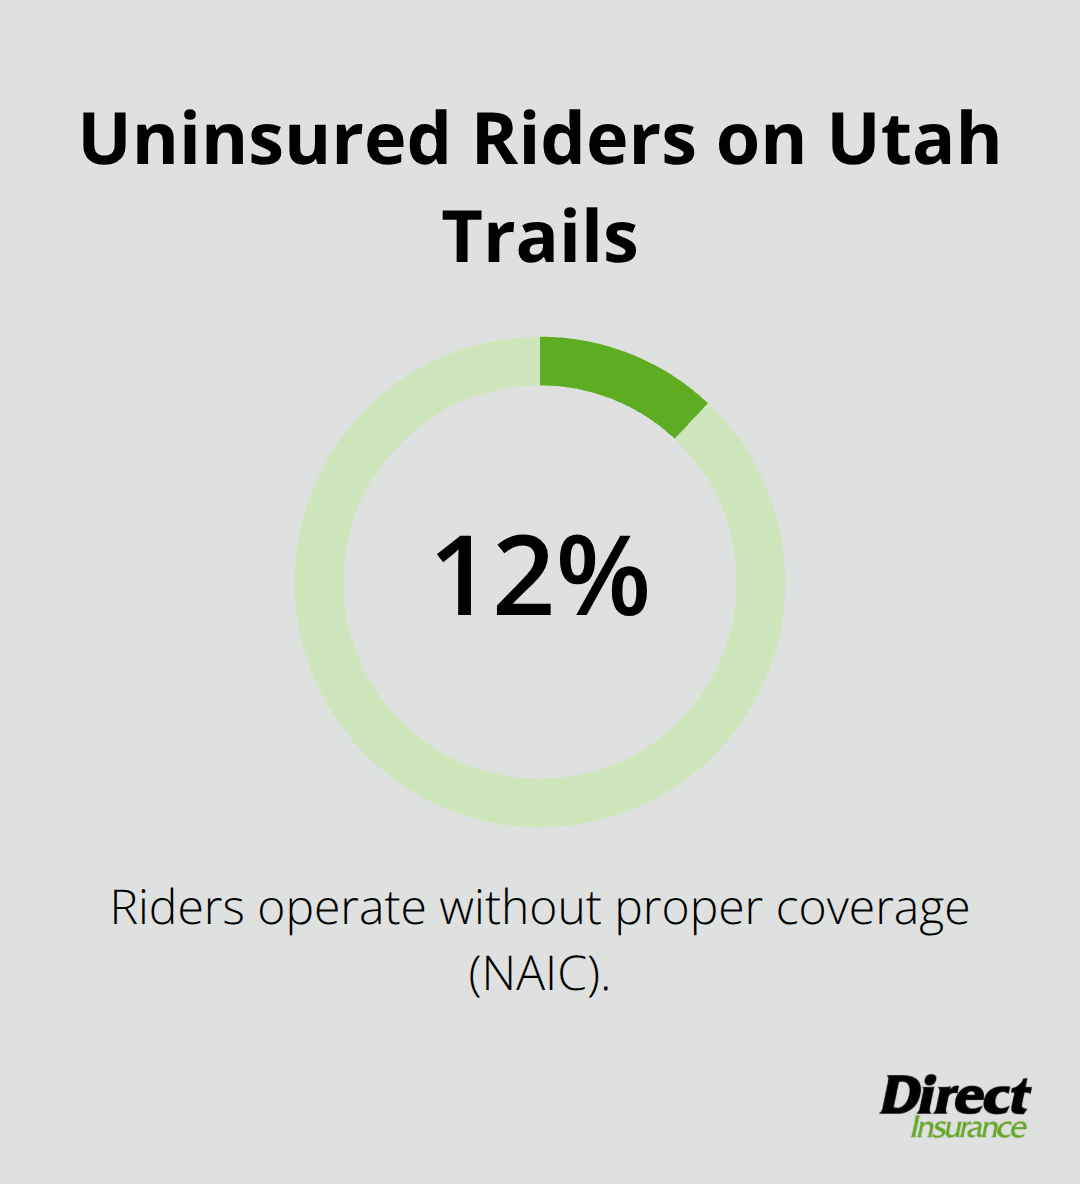
Uninsured and underinsured motorist protection addresses a specific St George problem: not every rider on southern Utah trails carries adequate insurance. If an uninsured rider hits you and causes injury or property damage, this coverage protects you when their policy doesn’t. The National Association of Insurance Commissioners found that roughly 12 percent of riders operate without proper coverage. Utah’s minimum liability limits often prove insufficient for serious accidents, making underinsured motorist protection valuable.
Theft and weather-related damage coverage
Theft and weather-related damage coverage work differently than most riders assume. Theft coverage reimburses you if someone steals your snowmobile, but the payout depends on your snowmobile’s actual cash value-not what you paid for it five years ago. Weather damage falls under comprehensive coverage, not a separate policy section. Hail damage claims spike during spring riding season in southern Utah when weather patterns shift unpredictably.
Selecting appropriate coverage limits requires understanding your snowmobile’s actual value and how frequently you ride. As an independent agency, we work with top-rated carriers to help you find protection that matches your specific situation, rather than pushing unnecessary add-ons that inflate premiums without meaningful protection. The coverage you choose now directly impacts what happens when St George’s challenging terrain and weather conditions test your protection.
Why Local Agents Understand St George Riding Better
Regional weather patterns create specific claim patterns
St George’s unique geography produces risks that national insurers struggle to recognize. The terrain shifts dramatically from high elevation mountains to desert valleys within short distances. Riders encounter wet spring snow that damages seals alongside sudden temperature swings that crack plastic components. Winter conditions in southern Utah don’t follow predictable patterns like they do in states with consistent cold. A 50-degree temperature difference between midday and evening is common, and that stress on equipment causes damage claims that surprise riders using policies designed for flatter, more stable climates.
Local agents see claim data that reveals these patterns firsthand. We know which months produce the most theft claims, which weather conditions trigger the most comprehensive damage, and which riding areas generate liability claims more frequently than others. This knowledge comes from handling snowmobile claims across southern Utah for years.
National carriers miss southern Utah’s unique risks
National carriers rely on broad statistical models that treat Utah snowmobiling like snowmobiling in Colorado or Wyoming, but southern Utah is fundamentally different. Spring riding season here means unpredictable weather that damages equipment in ways riders don’t anticipate. Standard insurance models don’t account for the specific risks that St George terrain creates.
Specialized carriers work differently. They have underwriting guidelines specifically for high-elevation, variable-climate regions. These carriers recognize that a St George rider faces different risks than someone in a consistent snow belt, and they price coverage accordingly.
Access to carriers that specialize in winter sports
Independent agencies work with carriers whose expertise actually matches where you ride. That alignment between your actual risk exposure and your coverage options is what separates adequate protection from protection that actually works when St George’s terrain and weather test your policy. Specialized carriers understand snowmobile coverage details that general auto insurers overlook.
At Direct Insurance Services, we work with top-rated carriers to help you find protection that matches your specific situation. As an independent agency, we connect you with carriers whose experience in winter sports and recreational vehicles translates to better coverage for southern Utah riders.
Final Thoughts
St George snowmobile insurance protects your financial security when southern Utah’s terrain and weather create real risks. The coverage you carry determines whether an accident becomes manageable or turns into a financial crisis. Utah’s minimum liability requirements exist for a reason, but they often fall short when serious injuries occur, and comprehensive coverage handles the weather damage that happens regularly in this region.
National carriers use generic models that don’t account for southern Utah’s unique climate and terrain. Local agents know which carriers specialize in winter sports coverage and which ones price policies based on actual regional risk data (rather than broad statistical assumptions). They identify gaps in your protection and connect you with coverage that matches where and how you ride.
Contact Direct Insurance Services to discuss your St George snowmobile insurance needs with someone who understands southern Utah’s specific risks. We work with top-rated carriers to help you find protection that actually covers your situation. We’re here to provide clear guidance about what your policy covers and why those protections matter for your riding.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


