
Condo Insurance Costs Utah: What Affects Your Premiums
Condo insurance costs in Utah vary significantly based on where your property sits and how it’s built. At Direct Insurance Services, we’ve seen premiums swing by hundreds of dollars depending on a few key factors.
Understanding what drives your premium helps you make smarter decisions about coverage. This guide breaks down the real numbers and shows you concrete ways to pay less.
What Drives Your Condo Insurance Premium
Location and Building Age Shape Your Costs
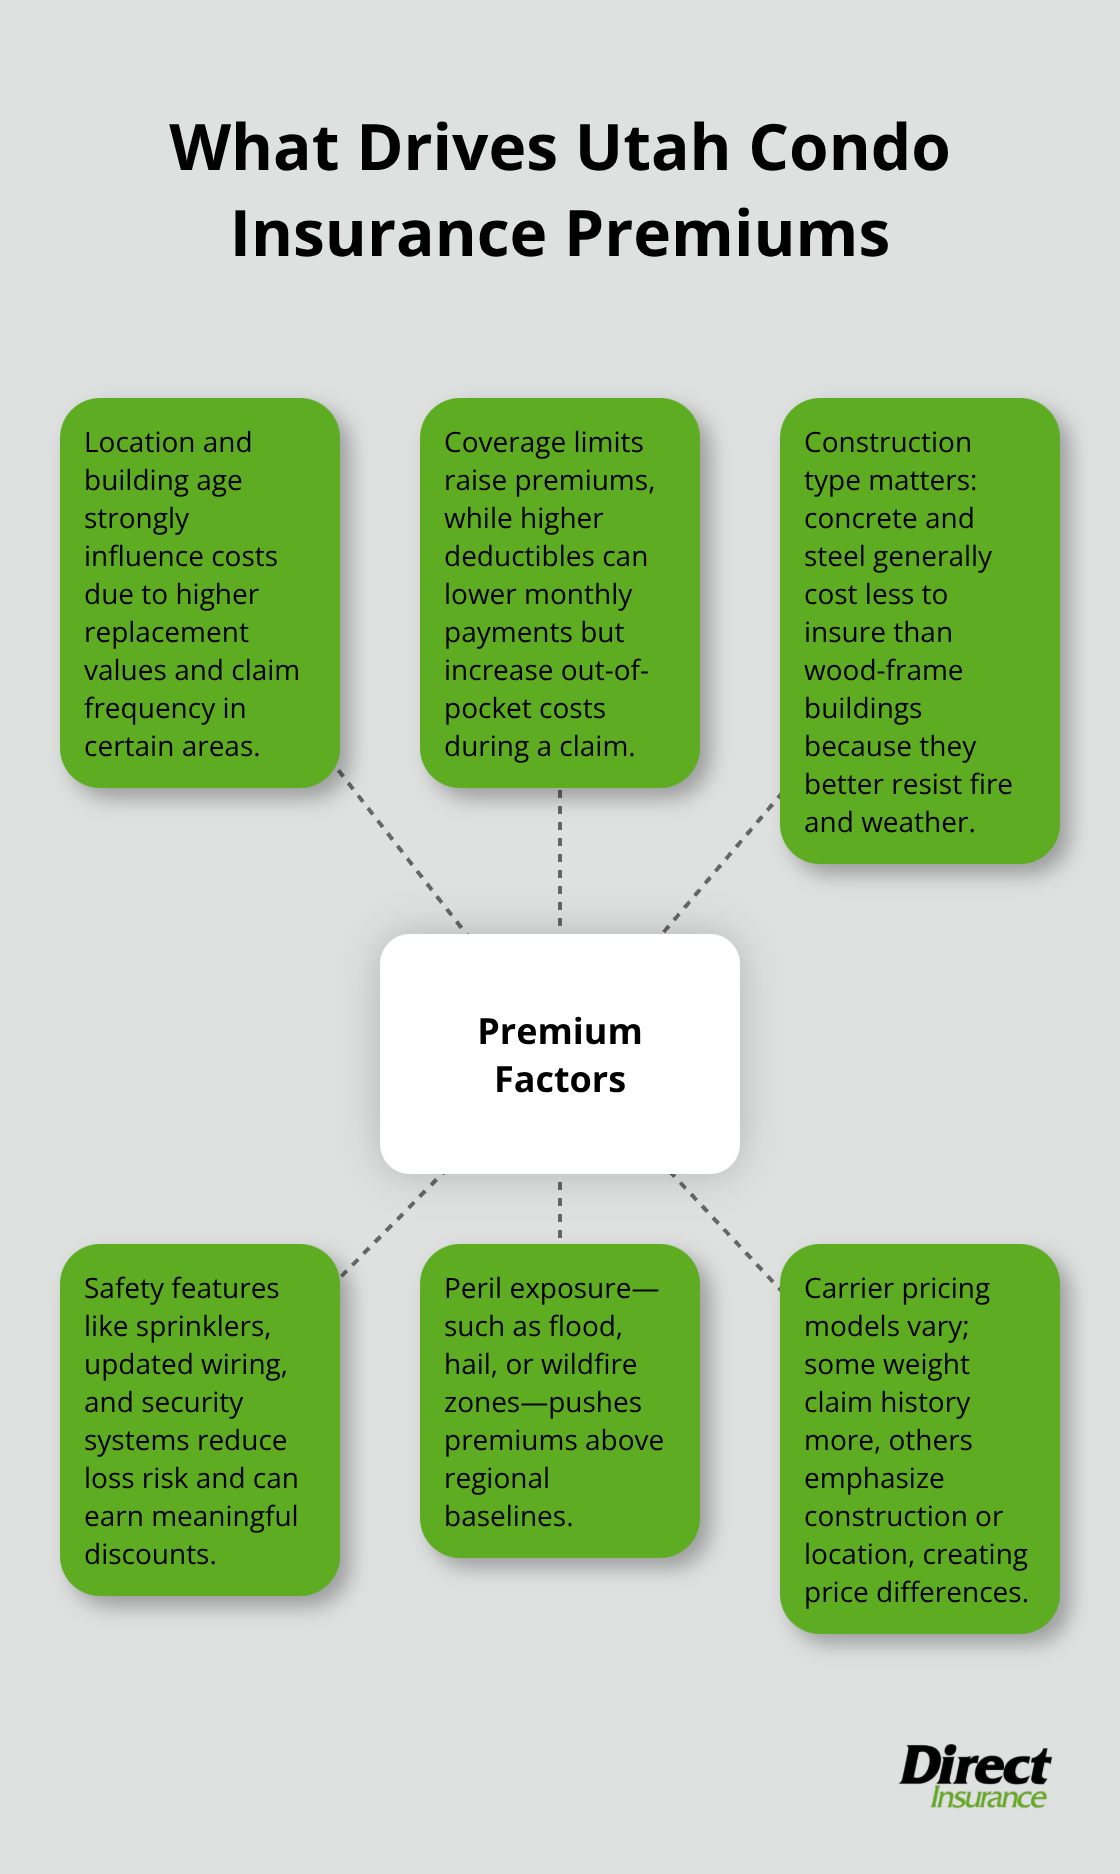
Your location within Utah matters far more than most people realize. Condos in Salt Lake City’s downtown core pay significantly higher premiums than identical units in smaller towns like Moab or Price. This difference stems from higher replacement costs in urban areas and increased frequency of claims. Building age plays an equally important role-a condo constructed in 1995 will cost more to insure than one built in 2015, simply because older electrical systems, plumbing, and roofs present greater risk.
Insurance companies use zip codes and construction dates as primary pricing factors because they directly correlate with claim history. If your building sits in a flood zone or area prone to hail damage, your premium jumps significantly above the baseline rate for your region.
Coverage Limits and Deductibles Control Your Monthly Payment
Your coverage limits and deductible choices directly control what you pay each month. Selecting a higher deductible instead of a lower one typically reduces your premium, though you’ll pay more out of pocket if you file a claim. Coverage limits for personal property, liability, and loss assessment protection vary widely-higher limits cost more but provide stronger financial protection.
Construction Type and Safety Features Lower Premiums
Building construction type significantly impacts pricing. Condos built with concrete and steel frames cost less to insure than wood-frame buildings because they withstand fire and weather damage better. Safety features like sprinkler systems, updated electrical wiring, and security cameras lower your premium substantially.
Before you request quotes, review what features your building actually has. Many owners don’t realize their building qualifies for safety discounts that could save hundreds annually. These specific building characteristics form the foundation of how insurers calculate your rate, which is why understanding them matters before you shop for coverage.
What Utah Condo Owners Actually Pay
Utah condo insurance premiums range from $400 to $1,200 annually for standard coverage, depending heavily on your specific location and building characteristics. Salt Lake City condos typically fall between $700 and $1,200 per year, while properties in smaller Utah cities like St. George or Logan average $450 to $750. The difference isn’t arbitrary-urban properties face higher replacement costs and claim frequency, which insurers price accordingly. National averages hover around $600 to $1,000 annually, meaning Utah sits slightly above the middle of the country. However, this national figure masks critical regional variations that matter far more to your actual quote.
Urban versus Rural Pricing Tells the Real Story
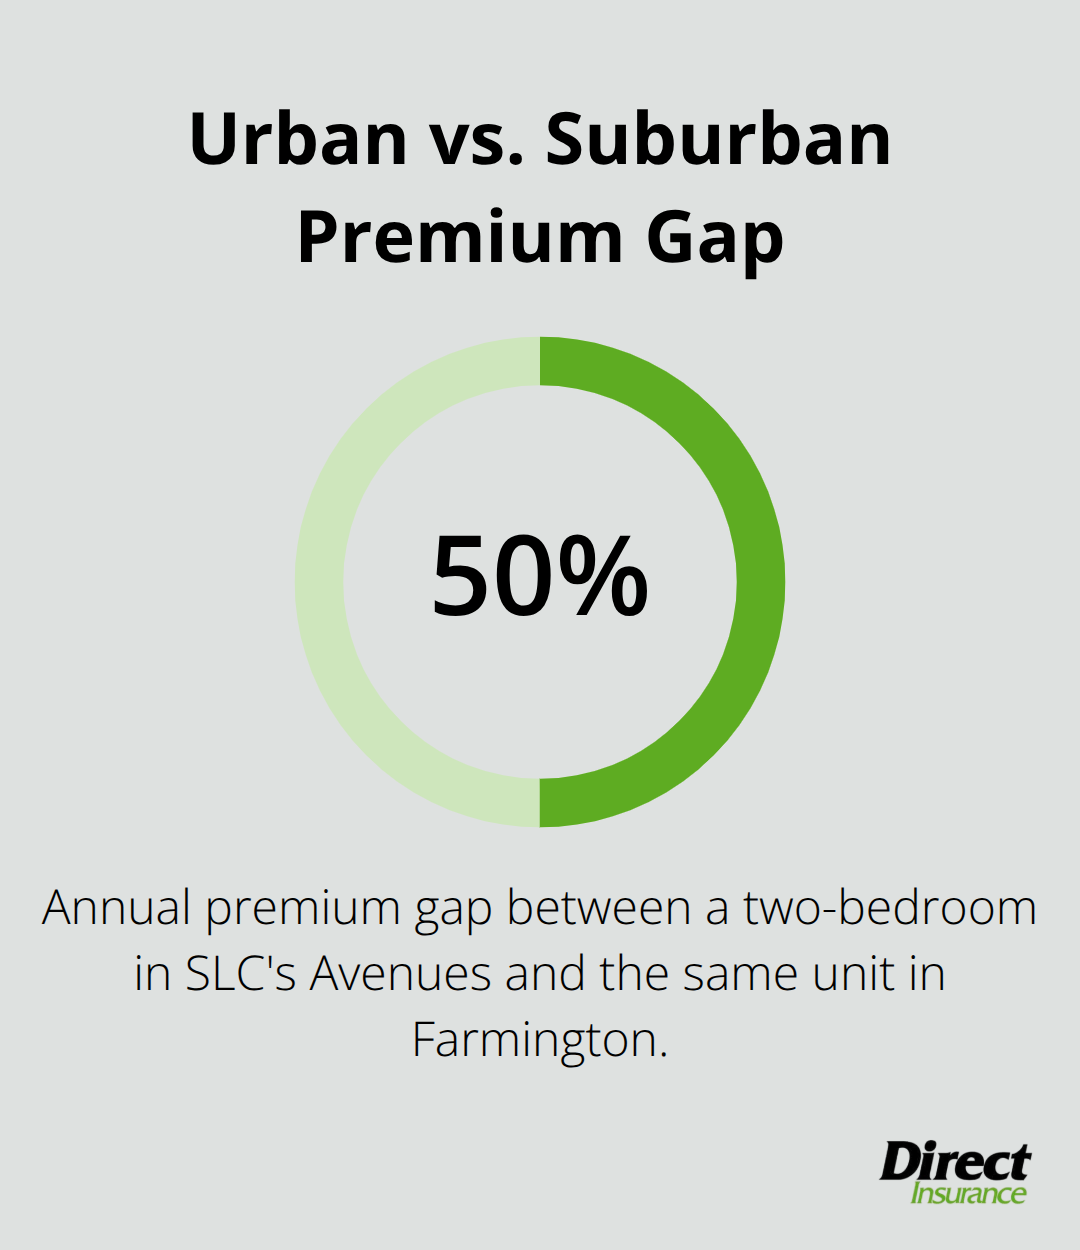
Downtown Salt Lake City condos cost substantially more than identical units fifteen miles outside the city limits. A two-bedroom condo in the avenues neighborhood might cost $950 annually while the same unit in Farmington costs $620. This 50-percent gap reflects urban claim patterns, higher property values, and increased risk from population density. Rural Utah properties benefit from lower replacement costs and fewer claims overall, which creates genuine savings.
The catch: rural areas sometimes face higher premiums for specific perils like hail or wildfire exposure, which can offset some location advantages depending on your exact zip code.
What Your Premium Covers and How Choices Affect Price
Your premium buys personal property protection, liability coverage, and loss assessment protection-but amounts vary significantly across policies. Most Utah condo owners select $30,000 to $50,000 in personal property coverage with $300,000 liability limits. Choosing a $500 deductible instead of $250 typically saves 15 to 20 percent on your annual premium. A condo owner in Provo paying $680 annually with a $250 deductible might reduce that to $550 with a $1,000 deductible. These aren’t theoretical savings-they’re concrete reductions that compound over years of ownership.
How Carriers Price Identical Coverage Differently
Shopping between carriers matters enormously because pricing for identical coverage varies by 30 to 40 percent across insurers in Utah. Two companies might offer the same $30,000 personal property limit and $300,000 liability protection at vastly different rates. Your zip code, building age, and safety features influence each carrier’s pricing model differently. Some insurers weight claim history heavily while others prioritize construction type. This variation means your best rate depends on which carrier values your specific property characteristics most favorably, which is why comparing multiple quotes reveals savings you won’t find any other way.
Reduce Your Premium Without Sacrificing Coverage
Bundle Policies for Immediate Savings
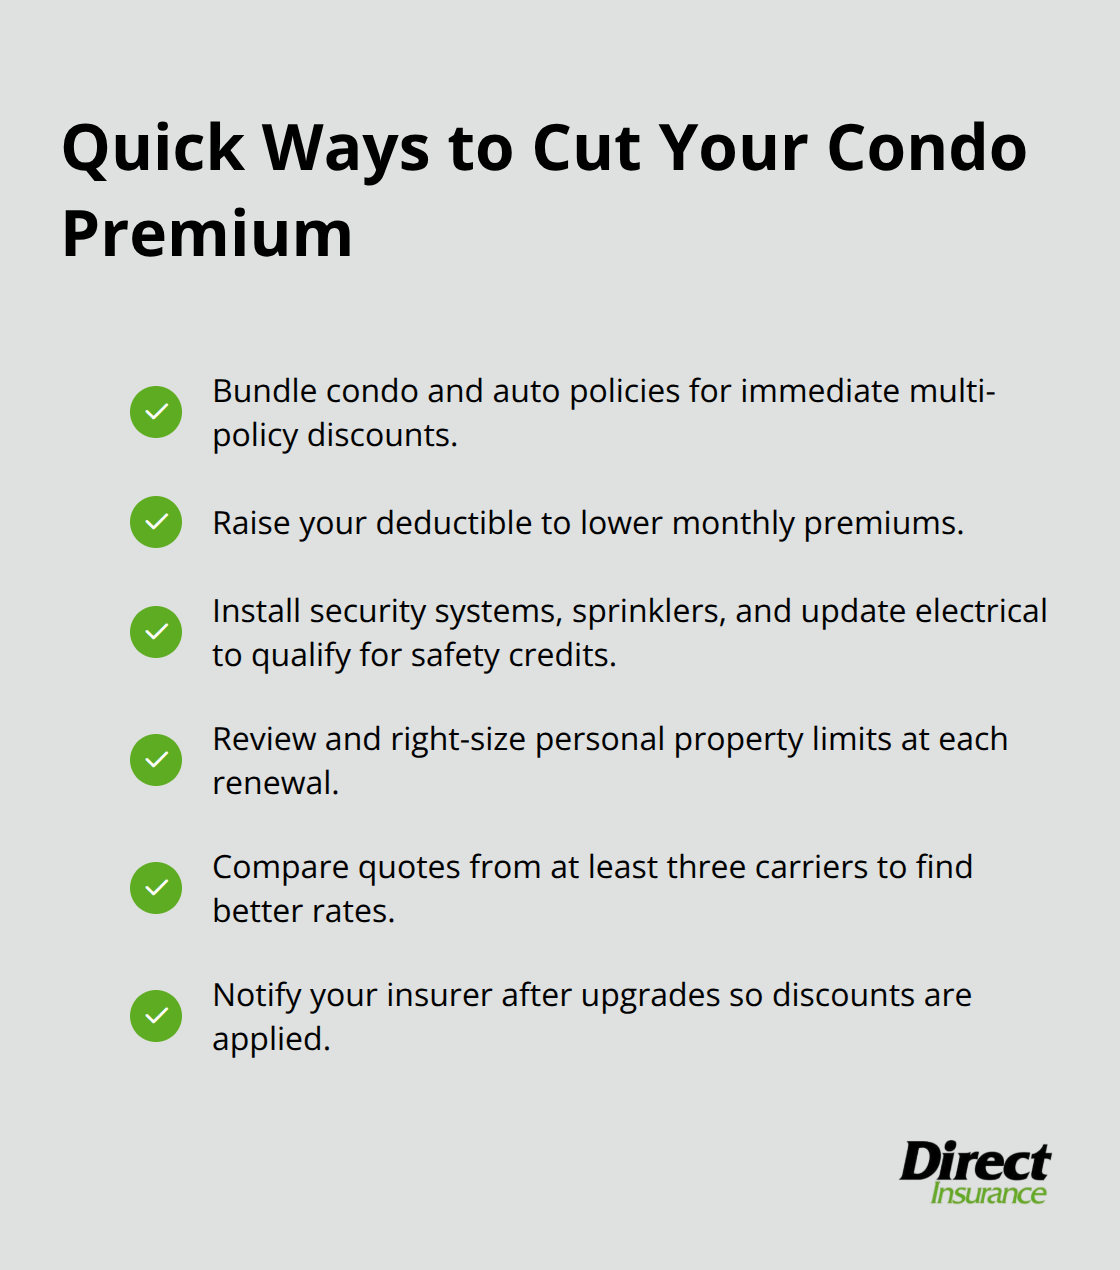
Bundling your condo insurance with auto or homeowners policies delivers the most reliable discount available to Utah property owners. Clients consistently save 15 to 25 percent when they consolidate policies with a single carrier. A condo owner paying $850 annually for condo coverage plus $1,200 for auto insurance might reduce combined costs to $1,700 through bundling, saving roughly $350 per year. This isn’t a small favor from insurers-it’s a standard business practice because bundled customers stay longer and file fewer claims overall. The discount applies immediately upon combining policies, so this change produces tangible savings starting with your next billing cycle.
Contact your current carriers and ask specifically what bundling discounts apply to your situation, then compare those figures against quotes from carriers you haven’t worked with yet. Some companies advertise bundling discounts prominently while others bury them in fine print, so direct questions yield clearer answers than reading marketing materials.
Invest in Building Safety Features
Building safety improvements create permanent premium reductions that accumulate over years of ownership. A security system, upgraded electrical wiring, or sprinkler systems typically reduce your premium by 10 to 20 percent because insurers recognize these features lower claim frequency. A Salt Lake City condo owner might invest $2,000 in security upgrades and recover that cost through insurance savings within three years while also gaining genuine protection improvements.
Notify your carrier once upgrades are complete so they adjust your rate accordingly-many owners finish improvements but fail to inform their insurer, missing savings they’ve already earned. This step takes minutes but produces measurable financial results.
Review Coverage Annually and Adjust as Needed
Annual coverage reviews matter equally because your needs change over time. If you’ve paid off debt or accumulated less personal property, reducing coverage limits lowers your premium without meaningful financial risk. Someone who initially selected $50,000 personal property coverage might need only $30,000 five years later, cutting that portion of their premium substantially.
Schedule this review each year when your renewal notice arrives so you stay current with your actual situation rather than maintaining coverage from years past. This practice (combined with the other strategies mentioned) compounds savings significantly over your years as a condo owner.
Final Thoughts
Your condo insurance costs in Utah reflect factors beyond your control-location, building age, construction type-alongside decisions you make directly. Understanding these elements gives you real leverage when shopping for coverage, and comparing quotes across multiple carriers reveals savings that can reach $300 to $500 annually. Bundling policies, investing in building safety improvements, and reviewing your coverage annually compound these savings significantly over time.
Identical coverage varies by 30 to 40 percent between insurers in Utah, which means your best rate depends entirely on which company values your specific property most favorably. Start by gathering quotes from at least three different carriers, then ask each one specifically about bundling discounts and safety feature credits. This approach takes time but produces tangible financial results that matter year after year.
Contact Direct Insurance Services to explore your options and see how much you might save on condo insurance costs in Utah.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


