
Auto insurance quotes Utah: How to Compare and Save
Utah drivers face real pressure to find affordable auto insurance without sacrificing coverage. Getting auto insurance quotes in Utah shouldn’t mean spending hours comparing policies or missing out on savings.
We at Direct Insurance Services help drivers cut through the confusion and find rates that actually fit their budget. This guide walks you through coverage types, comparison tools, and proven strategies to lower your premiums.
Understanding Auto Insurance Coverage Types in Utah
Liability Coverage Requirements in Utah
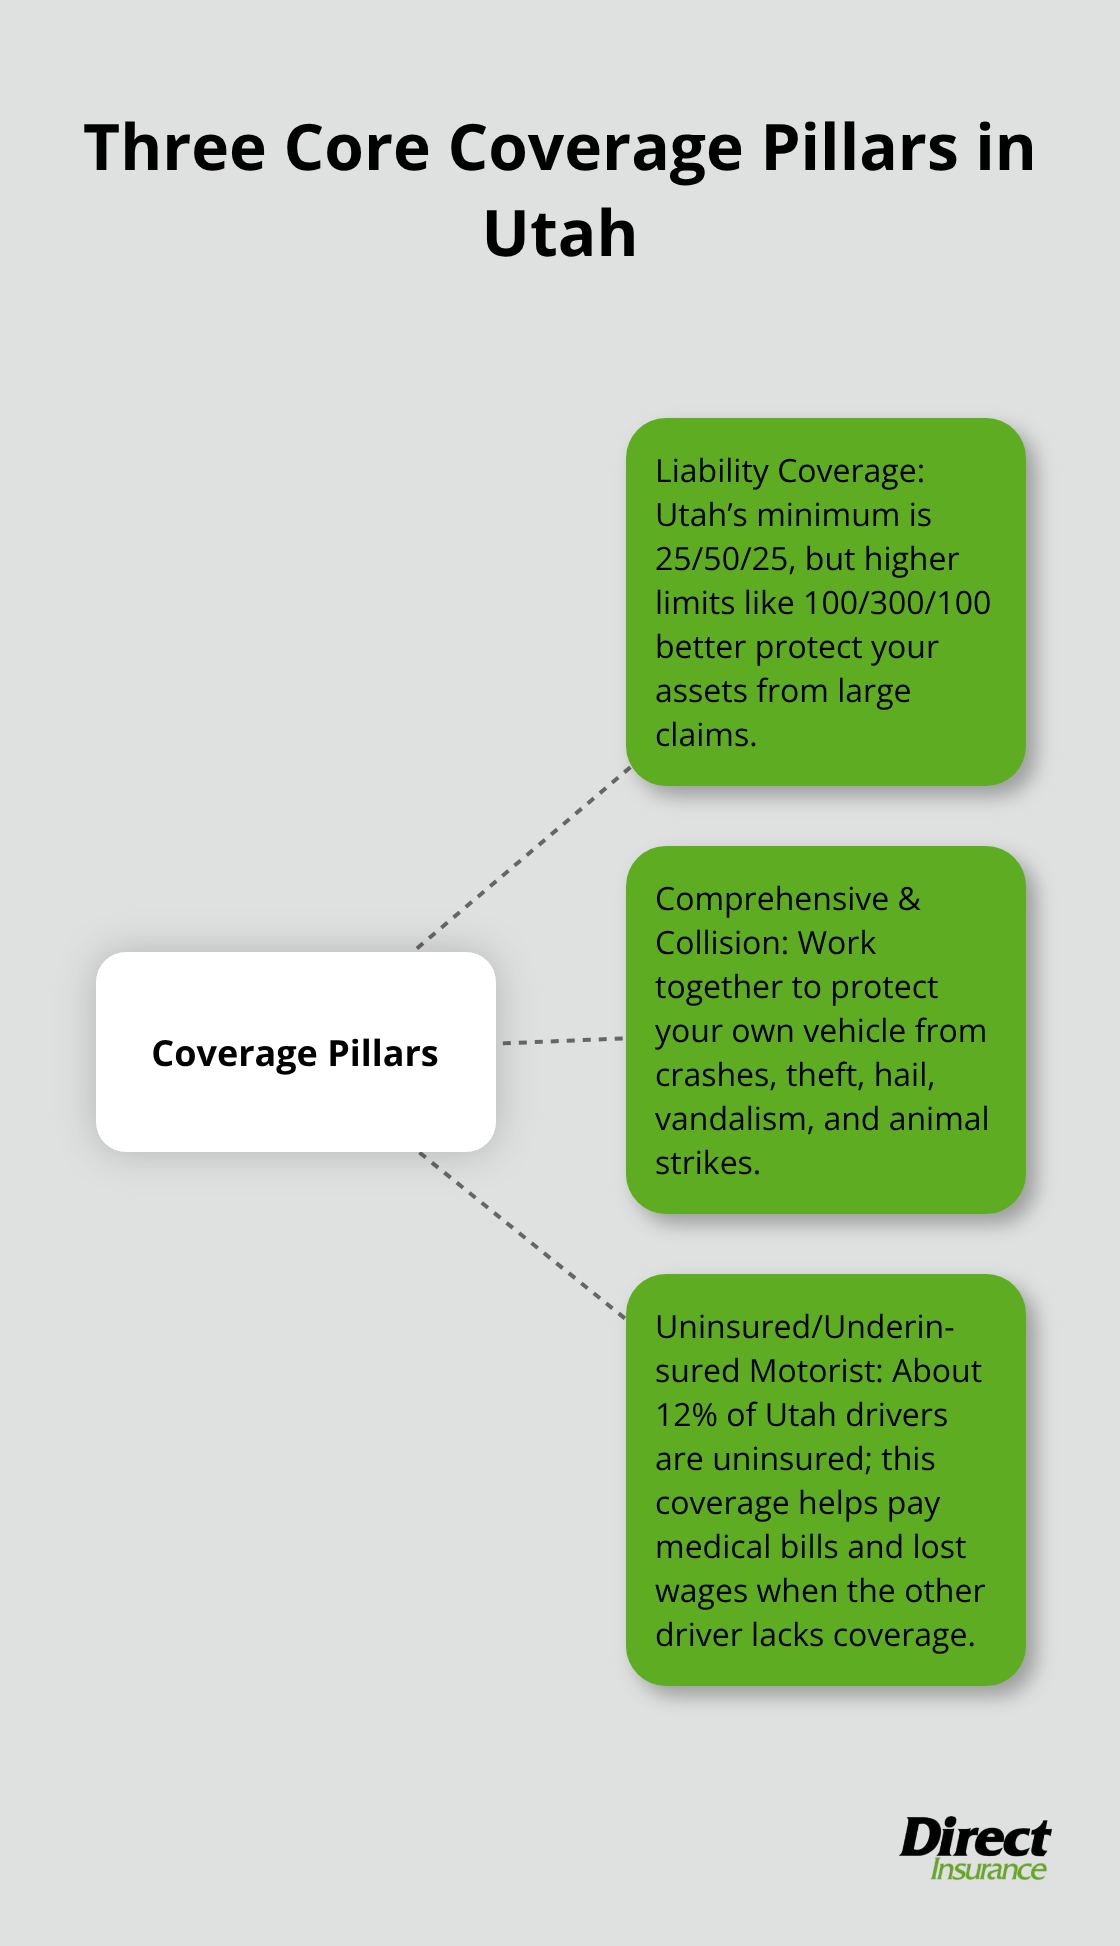
Utah requires all drivers to carry minimum liability coverage of 25/50/25, meaning $25,000 for bodily injury per person, $50,000 for total bodily injury per accident, and $25,000 for property damage. This is the legal floor, not a recommendation. If you cause an accident and your liability limits fall short, you’ll pay the difference out of pocket-a serious financial burden.
A single serious accident easily exceeds these minimums. Medical bills alone often run $100,000 or more, leaving you responsible for thousands in additional costs. Higher limits like 100/300/100 or 250/500/100 protect your assets far more effectively. The cost difference between minimum coverage and these higher limits is surprisingly small, often just $10 to $20 monthly.
Comprehensive and Collision Coverage Explained
Comprehensive and collision coverage protects your own vehicle rather than covering damage you cause to others. Collision covers accidents with other vehicles or objects, while comprehensive handles theft, weather, vandalism, and animal strikes. These two coverages work together to shield your investment from most damage scenarios.
Utah’s weather patterns create real risks for vehicle owners. Hail storms in spring and summer months cause significant vehicle damage across the state, making comprehensive coverage particularly valuable. If you financed or leased your vehicle, your lender requires both coverages as a condition of the loan or lease agreement.
The deductible you choose directly affects your premium. Jumping from a $500 deductible to $1,000 typically saves 15 to 30 percent annually, giving you meaningful control over your costs.
Uninsured and Underinsured Motorist Protection
Uninsured and underinsured motorist coverage protects you when the at-fault driver lacks adequate insurance or flees the scene. Utah has around 12 percent uninsured drivers on the road, making this coverage practical rather than theoretical. This protection covers medical expenses and lost wages for you and your passengers, and it applies regardless of who causes the accident.
This coverage fills a critical gap in your protection. Without it, you absorb the financial impact of someone else’s lack of insurance-a risk that affects thousands of Utah drivers annually. Understanding these three coverage pillars positions you to make informed decisions about which policies actually fit your situation and budget.
How to Get and Compare Auto Insurance Quotes
Steps to Gather Accurate Information for Quotes
Gathering accurate details before requesting quotes saves time and prevents misleading price comparisons. Start with your vehicle identification number, which insurers use to pull exact specifications affecting your rate. You’ll also need your driving history, including any accidents or violations from the past three to five years. Insurance companies weigh this heavily-an at-fault accident can increase premiums, with rates remaining increased for an average of three years.
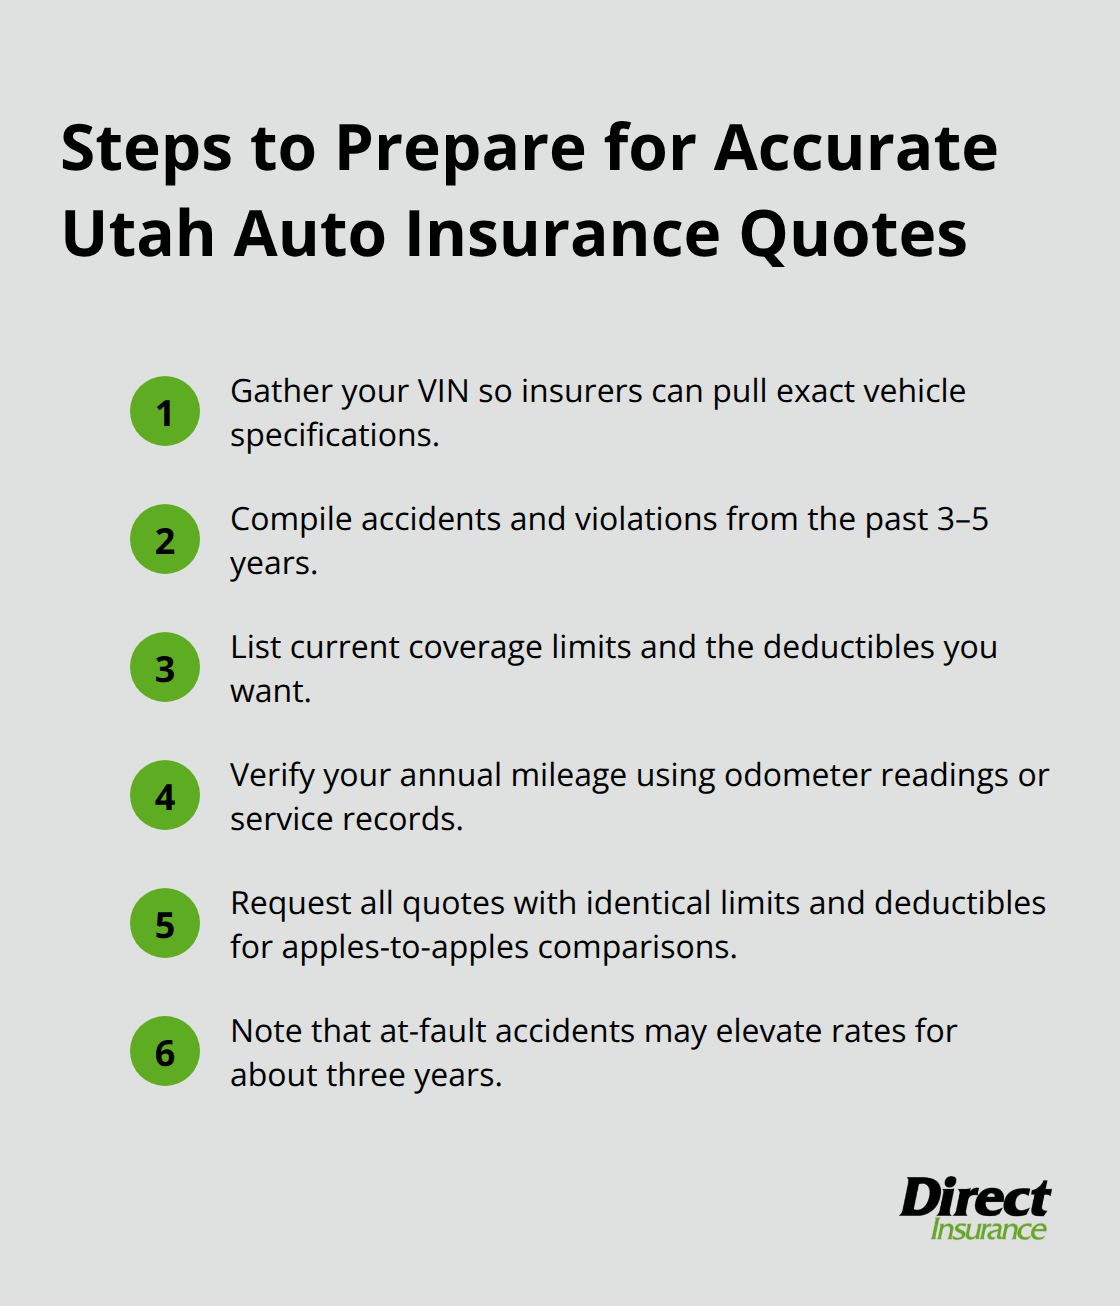
Have your current coverage limits ready if you’re switching policies, and know whether you want to keep the same deductibles or adjust them. Your annual mileage matters too; drivers who commute long distances pay more than those with shorter drives. Most people underestimate their mileage, so check your odometer readings or review past maintenance records for accuracy. Collecting this information upfront means quotes you receive actually reflect your situation instead of generic estimates that change when you apply.
Tools and Resources for Comparing Multiple Quotes
Getting three to five quotes from different insurers takes roughly 30 minutes and typically saves $500 to $1,000 annually compared to accepting the first quote. Prices vary dramatically between carriers-a 35-year-old driver might pay $1,200 with one company and $1,600 with another for identical coverage. Request quotes with the exact same coverage limits and deductibles across all insurers so you’re truly comparing apples to apples.
Online quote tools from major carriers work quickly, though independent agents can pull multiple quotes simultaneously and explain the differences without you repeating information five times. Direct Insurance Services, as a locally trusted independent agency, works with top-rated carriers to provide you access to multiple options without the pressure of a one-size-fits-all approach.
What to Look for Beyond Price When Comparing Policies
Don’t stop at the premium amount-check each insurer’s customer service ratings and claims handling reputation. J.D. Power data consistently shows significant gaps in satisfaction between top performers and struggling insurers, with some companies resolving claims 30 percent faster than competitors. Utah-specific factors matter here too; verify that each quote accounts for local accident rates and weather patterns rather than using generic national pricing.
After selecting a policy, call your agent directly to confirm no discounts were missed during the quote process, since many carriers offer bundling, safety feature, or low-mileage discounts that automated tools sometimes overlook. These hidden savings (often 10 to 25 percent off your base premium) frequently appear only when an agent reviews your full situation. With the right information gathered and quotes properly compared, you’re ready to explore the specific strategies that lower your premiums even further.
Money-Saving Strategies for Utah Auto Insurance
Discounts That Stack Up Fast
Most Utah drivers overpay for auto insurance simply because they haven’t explored what actually affects their premiums. The three biggest levers for lowering your costs are discounts you qualify for but don’t claim, deductible choices that most people get wrong, and policy bundling that carriers don’t always highlight automatically. Discount stacking alone can reduce premiums by 25 to 40 percent depending on your situation.
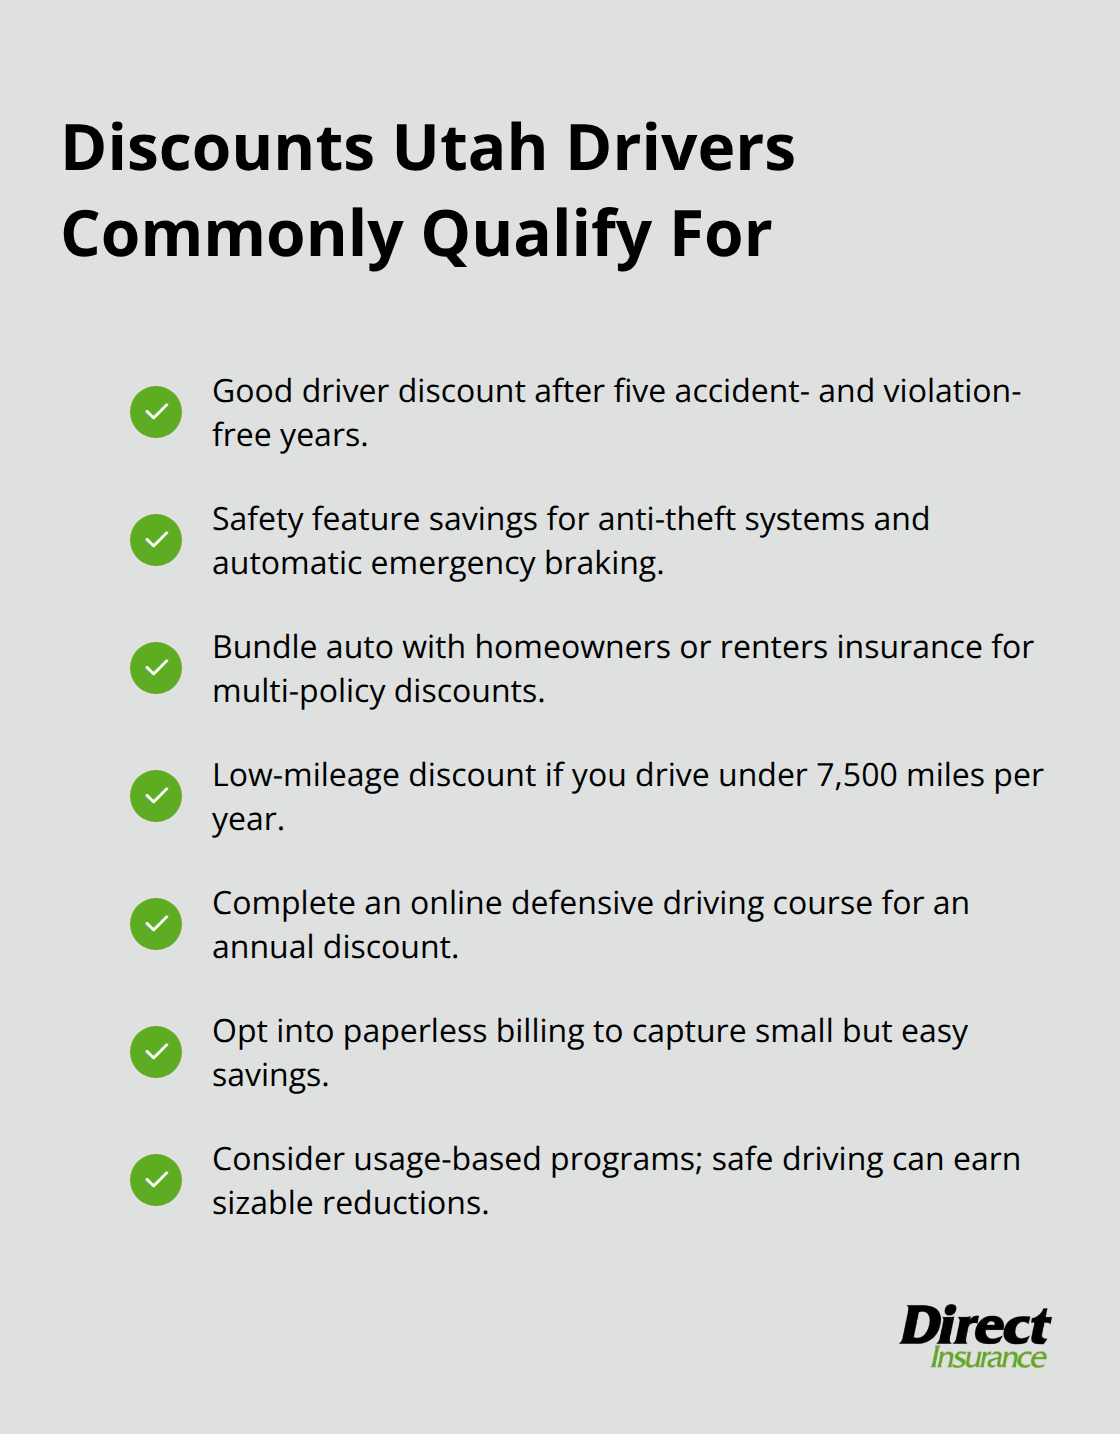
Common discounts include good driver discounts after five years without accidents or violations, safety feature discounts for vehicles with anti-theft systems or automatic emergency braking, bundling your auto policy with homeowners or renters insurance, low-mileage discounts if you drive under 7,500 miles annually, completion of defensive driving courses, and paperless billing. The defensive driving course discount typically saves $60 to $100 annually and takes just a few hours online. Many insurers also offer usage-based programs that monitor your actual driving habits-safe drivers often see 10 to 30 percent reductions.
The problem is that online quote tools frequently miss these discounts entirely. An agent reviewing your full situation catches what automated systems skip. When you work with an independent agency like Direct Insurance Services, we review your complete profile to identify every applicable discount before finalizing your quote.
How Deductibles Affect Your Premium
Your deductible choice dramatically shapes your annual cost, and most people make this decision wrong. Raising your deductible from $500 to $1,000 saves 15 to 30 percent on collision and comprehensive premiums, which means $200 to $400 annually on a typical Utah policy. The math works against keeping a low deductible unless you file claims frequently-statistically, most drivers file collision or comprehensive claims less than once every five to seven years.
If you have emergency savings covering $1,000, the higher deductible makes financial sense. This strategy transfers risk from the insurance company to you, and the premium savings reflect that shift. Test your comfort level with different deductible amounts before committing to a policy, since this single choice often determines whether your annual premium feels manageable or excessive.
Bundling Policies and Long-Term Savings Opportunities
Bundling policies creates the most overlooked savings opportunity. A driver combining auto and homeowners insurance typically saves 15 to 25 percent on both policies compared to purchasing them separately. Adding renters insurance or umbrella coverage to your bundle increases discounts further. Some carriers offer 30 to 35 percent total savings for three or more bundled policies.
Long-term loyalty also matters-staying with the same insurer for three or more years often qualifies you for retention discounts that newer customers don’t receive. The key is asking your agent specifically what discounts apply to your bundle and verifying the quote reflects every applicable reduction before you commit to a policy. These hidden savings (often 10 to 25 percent off your base premium) frequently appear only when an agent reviews your full situation rather than relying on automated quote systems.
Final Thoughts
Finding affordable auto insurance quotes in Utah requires three concrete actions: gathering accurate information about your vehicle and driving history, comparing quotes across multiple carriers with identical coverage limits, and claiming every discount you qualify for. Most Utah drivers leave $500 to $1,000 annually on the table simply by accepting the first quote or missing discounts that automated systems overlook. Your deductible choice and policy bundling decisions matter far more than most people realize, since raising your deductible from $500 to $1,000 typically saves 15 to 30 percent on collision and comprehensive coverage, while bundling auto insurance with homeowners or renters policies cuts 15 to 25 percent off both policies.
These two moves alone can reduce your annual premium by $400 to $600 without sacrificing meaningful protection. The difference between a mediocre rate and a genuinely competitive one often hinges on whether you work with an agent who reviews your complete situation rather than relying on generic online tools. An independent agency connects you with multiple carriers and identifies discounts that online quote tools consistently miss.
When you’re ready to get auto insurance quotes in Utah, contact Direct Insurance Services to receive personalized quotes tailored to your needs and budget. Our experienced team handles the comparison work so you get accurate quotes reflecting your actual situation, not generic estimates that change when you apply.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation


